

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Tank Cleaning Services Market to Reach USD 14.44 Billion by 2032 at 6.5% CAGR

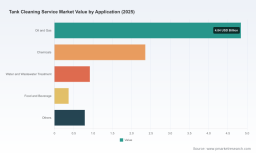
Tank Cleaning Service Market — Strategic Preview for 2026 Decision-Making
Executive summary
As companies plan capital allocations and go-to-market moves for 2026, the tank cleaning services sector presents a clear, accessible growth pathway underpinned by steady demand from energy, chemicals, water treatment and industrial manufacturing. Our analysis shows the global market expanding from an estimated USD 9.28 billion in 2025 toward roughly USD 14.44 billion by 2032, implying a mid-single-digit compounded annual growth rate (CAGR) of approximately 6.5% through the forecast window. That trajectory masks important structural shifts — consolidation among established environmental services players, accelerated adoption of automation and robotics in desludging operations, and a tightening regulatory and liability landscape that is reshaping service design and commercial terms.
Tank Cleaning Service Market
Why this research matters for 2026 planning
-
Portfolio allocation: The growth profile and earnings visibility of tank cleaning services make the segment an attractive defensive growth bet for industrial services investors — but returns will depend on operational discipline and margin capture in hazardous- vs. non-hazardous segments.
Tank Cleaning Service Market -
M&A and partnership timing: The market is at an inflection where strategic buyers can either buy scale to win larger industrial and municipal contracts or acquire specialized capability (robotics, PFAS treatment, advanced sludge recovery). Recent large-scale deals signal that scale plus niche capability is being rewarded in valuations.
Tank Cleaning Service Market -
Cost and insurance planning: Rising compliance scrutiny and high-profile safety incidents are increasing the importance of robust risk management — a material contributor to tender evaluation and insurance pricing in 2026 procurement cycles.
Market trajectory — the macro picture
The market’s expansion from the early 2020s into the mid-2020s reflects a combination of steady replacement demand (scheduled cleaning and desludging), episodic large projects (tank decommissioning, remediation), and an increasing share of work driven by environmental compliance and advanced waste treatment requirements. By 2025, global annual industry revenue reached the high single-digit billions (USD 9.28 billion), and the consensus forecast in our model points toward a roughly USD 14.44 billion market by 2032 at an approximate 6.5% CAGR. That pace is sufficient to sustain both organic investment cases and an active M&A market, but not so rapid as to obscure the need for operational rigor.
Key strategic implications for 2026
-
Invest in safe, automated capabilities now — and make them commercial: Robotics, remote monitoring, and online desludging technologies materially reduce confined-space risk and downtime. Companies that can commercialize automation through time-and-motion productivity gains and demonstrable HSE benefits will command premium contract terms in 2026.
-
Prioritize compliance and liability-proofing: Regulators and customers are tightening permit and entry requirements. High-profile enforcement actions — such as a multi-violation OSHA citation tied to failure to perform atmospheric testing inside tanks (and substantial proposed penalties) — illustrate how safety lapses can create existential cost shocks. Buyers and insurers will prefer vendors with documented confined-space programs, third-party certifications, and digital entry-permit systems.
-
Structure M&A to combine scale with specialty: The market exhibits moderate concentration at the top, making scale attractive for national and multinational procurement. However, buyers should layer on specialty capabilities (advanced contaminant management, PFAS solutions, sludge recovery) to protect margins and reduce cyclicality.
-
Design commercial models around total cost of ownership (TCO): Procurement is shifting from low-cost per-job pricing to TCO models that include environmental disposal, remediation risk, downtime, and reputational factors. Service providers must build and sell integrated TCO analyses to win longer-term agreements.
-
Capitalize on environmental tailwinds: Waste treatment and contaminant-specific remediation (notably PFAS and complex hydrocarbons) are driving incremental service spend. Vendors that integrate advanced treatment and recovery — rather than purely focusing on removal and transport — can capture higher-value scopes.
Competitive landscape — who matters and why
The vendor field contains a mix of global environmental services groups, regional specialists, and technology-focused entrants. Market concentration is meaningful but not prohibitive — the top three players control a significant share of industry revenues, and the top five an even larger slice, leaving space for specialized and regional players to outcompete on capability or cost.
-
Veolia — A global environmental services leader with a strategy of capability-led scale. Recent large acquisitions aimed at hazardous waste and advanced contaminant management underscore Veolia’s intent to broaden its North American footprint and advanced treatment capabilities. For corporate buyers, Veolia represents the archetype of the scale-specialist consolidator.
-
Clean Harbors — A principal North American hazardous-waste and industrial services platform. Its integrated model across treatment, transport and disposal is designed to capture end-to-end value on complex tank cleaning projects.
-
Tradebe and National Tank Services — Regional to continental players that blend full-service offerings with niche remediation projects. They are often preferred on contracts where local permitting and rapid response are determinants.
-
Dulsco and Arham Oil — Examples of regionally dominant firms innovating with service delivery models suited to local market dynamics; case in point, Arham Oil’s 2025 nationwide launch of upgraded robotic crude oil tank cleaning services signals growing market acceptance for automation-led service propositions in high-volume markets.
-
Evergreen Industrial Services , Thompson Industrial Services , SWS Environmental Services , and ARKOIL Technologies — Mid-market players that emphasize time-critical shutdown work, industrial cleaning contracts, and specialist technologies. They are potential acquisition targets for scale players or strategic partners for capability augmentation.
Operational and compliance dynamics shaping vendor selection
-
Confined-space safety and atmospheric testing regimes are now table-stakes. Buyers increasingly require documented permit-to-work systems, third-party auditability, and digital logs of atmospheric testing and PPE compliance. Failure to meet these expectations materially increases both bid rejection rates and insurance costs.
-
Environmental performance is pricing power: Disposal pathways, sludge recovery rates, and PFAS handling capabilities influence lifetime contract economics more than marginal cleaning price. Vendors that can demonstrate higher recovery rates and lower disposal liabilities will command longer contracts and higher margins.
-
Workforce and training are competitive differentiators. Skilled operator scarcity is real in many jurisdictions; firms that invest in upskilling, remote-operated platforms and predictive workforce planning will reduce labor cost volatility.
-
Technology and digital enablement are shifting cost structures. Remote monitoring, digital permits, and automated desludging reduce non-productive time and can be monetized through performance-based contracting.
What the full report delivers — an operational playbook
The PW Consulting Tank Cleaning Service Market report is structured to support executable decisions in 2026. It combines top-line market sizing and forward-looking scenarios with operational toolkits and commercial templates. Highlights include:
- Robust market-sizing methodology with base-year 2025 calibration and a 2026–2032 forecast scenario set; sensitivity testing for oil price, regulatory tightening, and municipal spend.
- Actionable M&A playbooks: target screening criteria, valuation multiples benchmarking, and integration checklists tailored for both scale buyers and capability acquirers.
- Vendor due-diligence templates and RFP evaluation rubrics that weight safety, environmental treatment capability, and TCO impact.
- Commercial models and sample contract language for performance-based and TCO-oriented deal structures.
- Operational levers: productivity-improvement roadmaps (automation adoption curves, crew productivity KPIs), and CapEx/Opex models for scaling robotics and advanced treatment lines.
- Regulatory and safety compendium: concise summaries of confined-space entry requirements, permit frameworks, and recent enforcement trends to inform compliance budgeting and insurance discussions.
Concrete near-term recommendations for 2026
-
Buyers: Tighten vendor pre-qualification on HSE and advanced treatment credentials; prefer multi-year TCO contracts that shift disposal and remediation risk back to vendors with demonstrated treatment capability.
-
Service providers: Prioritize investments in robotic desludging and online sludge-processing capability that demonstrably reduce confined-space exposure; use pilot projects to build commercial case studies for premium pricing.
-
Investors: Target carve-outs and bolt-on acquisitions that add contaminant-specific treatment or coverage in underpenetrated geographies, but require clear integration plans to capture cross-selling opportunities.
-
Risk managers: Reassess insurance programs and bonding capacity, incorporating recent regulatory actions and penalties into stress-testing models for potential operational lapses.
Concluding perspective — opportunity with discipline
The tank cleaning services market in 2026 offers predictable top-line growth and multiple strategic pathways for value creation — organic specialization, technology-driven productivity, and consolidation-led scale. Yet, the market prize will go to organizations that combine safety-first operational discipline with differentiated technical capability and commercially savvy contract design. Our full report equips executives with the diagnostic data, playbooks, and vendor intelligence needed to act decisively in 2026. For a deep dive into scenario-modeled forecasts, company profiles, and the full competitive dataset, access the complete PW Consulting Tank Cleaning Service Market study.
For detailed analysis of this topic, please visit the official page: Tank Cleaning Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com