

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Electrostatic Chucks for Wafer Market Poised for 8.45% CAGR through 2032

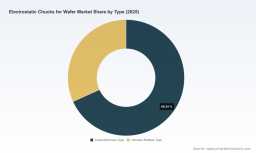
Electrostatic Chucks for Wafer Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
As semiconductor nodes compress and fabs push throughput, the electrostatic chuck (ESC) market is entering a sustained growth phase that demands proactive strategic responses. Our latest PW Consulting study, built on a 2020–2025 historical baseline and projecting to 2032, quantifies the sector’s momentum and decodes the operational, supply-chain, and regulatory inflection points that will shape supplier and end‑user strategies in 2026 and beyond. At a compound annual growth rate (CAGR) of 8.45% through the forecasting horizon, the market trajectory underscores both expanding demand and intensifying competitive dynamics. The global market expands notably from the 2025 base year into the 2032 horizon—an outcome that validates investment and reshoring conversations across the value chain.
Electrostatic Chucks for Wafer Market
Why this report matters for 2026 decisions
- Actionable foresight: The report converts macro growth projections into decision-ready scenarios for procurement, R&D prioritization, and capacity investments timed for 2026 capex cycles.
- Risk-informed planning: It overlays supply‑chain fragilities and export/regulatory noise onto demand forecasts to quantify exposure and recommend mitigation measures appropriate for near‑term contracting windows.
- Competitive advantage: By synthesizing technical trends (multi‑zone thermal control, RF‑optimized chucks, AI‑enabled sensing) with market structure metrics, the study helps executives select between organic product development, alliances, and M&A pathways to defend or expand market share.
Market trajectory — what the headline numbers reveal
Using 2025 as a base year, the ESC market exhibits a clear upward trajectory through 2032. Historical market development between 2020 and 2025 shows steady maturation, while the forecast period captures accelerated adoption driven by advanced node requirements and increased localized equipment spending. The reported CAGR of 8.45% reflects both unit demand growth and a premiumization effect as customers adopt high‑value ESC variants (e.g., multi‑zone thermal chucks, RF‑optimized solutions) that command higher average selling prices.
Electrostatic Chucks for Wafer Market
This growth picture is not uniform: technology migration (from legacy nodes to sub‑10nm processes), capacity expansions in leading foundry clusters, and non‑semiconductor usage (MEMS, sensors, specialty fabs) all create differentiated pockets of demand. Our analysis quantifies these dynamics in a way that is immediately usable for capacity planning, but, in line with our 'trailer' approach, detailed subsegment figures are reserved for the full report to ensure maximum commercial utility for subscribers.
Electrostatic Chucks for Wafer Market
Concentration and competitive dynamics
The industry exhibits high concentration among the top suppliers, with the three‑firm concentration and five‑firm concentration indicators signaling a market where scale, IP, and service footprint matter. This structure has strategic implications for pricing power, partnership approaches, and the speed at which new entrants can scale.
- Applied Materials, Inc. — Leveraging multi‑zone thermal control capabilities and recent moves into AI‑enabled wafer handling, Applied Materials is positioning ESCs as integrated subsystems within tool platforms. The firm’s M&A activity signals a push to embed predictive maintenance and process‑aware sensing into the ESC layer.
- Lam Research Corporation — Focused on etch and deposition applications, Lam’s ESC strategy centers on process optimization and tool‑level integration, reinforcing the importance of close OEM‑supplier collaboration for high‑throughput fabs.
- Japanese ceramic specialists (Shinko Electric, Kyocera, NGK, Sumitomo Osaka Cement, TOTO, NTK CERATEC) — These players emphasize materials engineering (e.g., aluminum nitride ceramics, rare earth doping) and production precision, maintaining a competitive edge in manufacturing quality and thermal management.
- Specialized component and regional suppliers (Entegris, II‑VI M Cubed, Calitech, Beijing U‑PRECISION) — These firms compete on niche performance attributes, service proximity to fabs, and cost flexibility, often serving as vital second‑source partners for major tool integrators.
Recent industry moves reinforce these trends: product launches optimized for advanced nodes, acquisitions integrating AI sensors into chuck systems, and partnerships to develop eco‑friendly ceramic solutions—each event illustrates the dual push for technical differentiation and supply resilience.
Supply‑chain and regulatory realities that will shape 2026 playbooks
We identify five interlocking sources of risk that require immediate incorporation into 2026 planning:
- Export controls and licensing complexity: New rules targeting advanced computing items with sophisticated ESC features (for example, systems with many independently controlled temperature zones) mean export licensing is now an integral part of go‑to‑market planning. Firms must integrate compliance and trade remediation costs into tender responses and subcontracting decisions.
- Raw‑material concentration: Key inputs—most notably high‑purity aluminum nitride powder and certain rare‑earth dopants—are concentrated among a few suppliers. The sector has already experienced delivery delays and has been compelled to hold extended safety stocks. Tactical playbooks must include multi‑sourcing, strategic inventory, and supplier development programs.
- Volatility in specialty materials pricing: Quarterly price swings for dopants and engineered ceramics can materially affect margins on high‑performance ESCs. Hedging policies, pass‑through clauses, and cost‑reduction roadmaps must be established before 2026 procurement cycles.
- Localized production incentives: U.S. and EU incentives are accelerating the establishment of near‑fab service hubs and manufacturing footprints. This is a two‑edged sword: proximity unlocks faster service, but it also raises the bar for fixed‑cost investments and drives consolidation among players that can absorb regional setups.
- Geopolitical supply constraints: Technology restrictions affecting cross‑border flows—particularly between the U.S. and China—create uncertainty for companies relying on integrated supply networks. Scenarios range from re‑routing procurement to building duplicate capacity in friendly jurisdictions.
What the PW Consulting report delivers (practical components)
The report is designed to be a practical toolkit for executives and program managers responsible for product roadmap, procurement, and M&A decisions in 2026. Key deliverables include:
- Top‑line and bottom‑line scenario modeling (2026–2032) calibrated to process node adoption curves and fab expansion schedules.
- Supply‑chain heat map highlighting single‑points‑of‑failure for critical materials and optional mitigations (second‑source, inventories, supplier co‑development).
- Regulatory impact assessment that translates current export control and incentive frameworks into commercially relevant constraints and opportunities by geography and product capability.
- Commercial playbooks for OEMs and ESC specialists covering pricing strategy, service‑network design, and aftermarket revenue levers.
- A competitive scorecard benchmarking product features (thermal uniformity, RF compatibility, sensing integration), service reach, and horizontal capabilities such as AI‑enabled predictive maintenance.
- M&A and alliance decision framework that maps capability gaps to likely targets and partnership archetypes—supporting both bolt‑on and platform plays.
How to translate insights into 2026 actions
For executives preparing 2026 budgets, the report suggests a prioritized sequence of actions:
- Immediate (0–6 months): Conduct a supplier concentration audit for critical materials; commence trade‑compliance scenario planning for advanced ESC features; and assess short‑term inventory strategies.
- Near‑term (6–18 months): Validate product roadmaps against node migration timelines; pilot AI‑enabled sensing in controlled lines to validate predictive maintenance ROI; negotiate strategic supply agreements with manufacturing‑grade clauses to lock in quality and lead times.
- Medium‑term (18–36 months): Decide on localized production investments informed by incentive programs; implement near‑fab service hubs where economics and customer proximity justify the cost; or form alliances with local manufacturers to secure market access.
Competitive bets and M&A signals
Given the market concentration and technological premiumization, we see three dominant strategic bets that will differentiate winners in 2026:
- Integration of intelligence: Embedding sensing and analytics into ESCs (as evidenced by recent acquisitions and product launches) yields superior uptime and total cost of ownership narratives for customers.
- Materials leadership: Control over high‑quality ceramics and dopants—either through vertical integration, strategic partnerships, or secured long‑term supply—reduces production variability and shortens qualification cycles.
- Service proximity: Near‑fab servicing and rapid spare availability convert into tangible revenue premiums for tool integrators and ESC specialists alike; investors should expect consolidation to accelerate around these capabilities.
Call to action — what to read next
This preview outlines the contours of a market that is both expanding and becoming more complex. The full PW Consulting report contains the granular segmentation, regional scenario models, detailed supplier matrices, and exact financial forecasts that procurement, product, and corporate development teams will need to craft binding 2026 strategies. We intentionally withhold detailed subsegment and region‑level figures here to preserve the actionable value of that intelligence for subscribers.
For companies preparing capital and operational plans for 2026, the report functions as a strategic playbook: quantify exposure, prioritize mitigations, and align investments with the node and geography‑specific demand signals that will determine who captures premium margins in the coming cycle.
Closing
Electrostatic chucks are no longer a commodity component: they sit at the intersection of materials science, precision manufacturing, and embedded intelligence. The market growth and structural signals highlighted herein make 2026 a pivotal planning year. PW Consulting’s full study equips decision‑makers with the data, risk maps, and playbooks required to convert an industry inflection into competitive advantage—while the accompanying dataset provides the fine‑grained insights necessary to operationalize those choices.
For detailed analysis of this topic, please visit the official page: Electrostatic Chucks for Wafer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com