

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: IT & Electronics
PW Consulting: All-Solid-State Battery Market to Reach USD 23.08B by 2032 at 13.2% CAGR
By pmarketresearch, 2026-07-08
All‑Solid‑State Battery Market: Strategic Outlook for 2026 Decision‑Makers
PW Consulting presents a focused strategic preview of the All‑Solid‑State Battery (ASSB) market intended to inform corporate, investor, and policy decisions through 2026 and beyond. Built on a base year of 2025, our market model — expressed in USD (Million) — captures a historical trajectory (2020–2025) and projects forward across a 2026–2032 forecast horizon at a compound annual growth rate of 13.2%. Under this central scenario the market expands materially over the forecast window, underscoring meaningful commercial opportunity as well as complex execution risk for stakeholders pursuing industrialization, OEM integration, and aftermarket safety compliance.
All-Solid-State Battery Market
Why this research matters in 2026
2026 is the inflection point at which laboratory advances and pilot demonstrations are converging with first‑wave industrial deployments. For executives making near‑term capital allocation, partnership, and product‑roadmap choices, a disciplined view of scale‑up timelines, supplier concentration risk, and regulatory trajectories is essential. Our study translates technical milestones and pilot‑line activity into commercial timelines and decision triggers so that management teams can prioritize investments, secure supply, and design entry or defense strategies that align with real manufacturing readiness.
All-Solid-State Battery Market
Core dynamics shaping the 2026 landscape
- Technology pathways and tradeoffs: Multiple chemistries (lithium‑metal anodes with thin solid electrolytes, sulfide electrolytes, oxide ceramics, and composite approaches) are now in pilot or early pre‑production. Each path has different performance, safety, manufacturability and IP characteristics; choosing a partner or in‑house route has long‑term strategic consequences.
- Manufacturing transition: Automated pilot lines and roll‑to‑roll processes are moving from demonstrations toward continuous production. Pilot throughput, yield improvement curves, and CAPEX cadence determine the timing of economically viable gigawatt‑scale supply.
- Supply chain bottlenecks: Solid electrolyte demand creates new upstream needs — industry presentations indicate very large tonnage requirements per gigawatt hour of capacity — producing potential sourcing and processing bottlenecks that will constrain early movers if not addressed proactively.
- Standards and safety: Global standards development and national standardization initiatives are accelerating. Advanced safety testing guidelines and harmonized protocols are being developed, but full international consensus remains under workstream activity, raising compliance timing risk for OEMs and tier‑1 suppliers.
- Policy and funding support: Public funding and small‑business innovation awards are directing capital toward manufacturing innovation, accelerating domestic capabilities in key markets, and shaping where early production footprints will be viable.
Strategic implications by value‑chain node
- Raw‑material and electrolyte sourcing: Secure long‑lead suppliers of solid electrolytes and precursor materials through multi‑year contracts, co‑investment, or equity stakes. Sourcing is a strategic bottleneck that can constrain capacity ramp.
- Cell design and intellectual property: Protect and license critical IP while evaluating cross‑licensing to accelerate OEM adoption. Some technology owners are pursuing licensing models tied to automated pilot lines; others are vertically integrating.
- Pilot‑to‑mass transition: Validate manufacturing yield and cycle‑life at pilot scale and build modular CAPEX plans that allow staged expansion tied to yield improvements rather than upfront oversized investments.
- OEM integration and timing: Align vehicle architecture roadmaps with realistic cell delivery windows; avoid aggressive launch dates that ignore validation and regulatory approval timelines.
- Regulatory readiness: Invest in compliance protocols and third‑party validation programs to accelerate certification, particularly where national standards are in the process of being finalized.
Competitive landscape: what to watch in 2026
The market is shaped by a mix of specialized start‑ups, industrial JV players, established battery OEMs and legacy automakers. Below are the strategic postures and near‑term triggers for leading actors that will influence competitive dynamics in 2026 and beyond.
All-Solid-State Battery Market
- QuantumScape Corporation (San Jose, CA) — Strengths: technology focused on lithium‑metal high‑energy anodes and an automated pilot facility designed to support OEM sampling and licensing. Strategic signal: the inauguration of an Eagle Line pilot indicates a licensing and OEM sampling playbook; watch for announcements on sampling schedules and licensing terms that could accelerate third‑party adoption.
- Ampcera Inc. (San Jose, CA) — Strengths: materials specialization in high‑performance sulfide electrolytes with scaling production. Strategic signal: suppliers of engineered electrolyte powders can become chokepoints; partnering or offtake agreements with cell makers will be pivotal.
- Argylium (France) — Strengths: a European JV combining industrial and research capabilities to commercialize sulfide electrolytes. Strategic signal: regional industrial alliances and state support can create locally advantaged supply clusters.
- Solid Power Inc. (Louisville, CO) — Strengths: demonstrated manufacture of multi‑Ah cells on continuous roll‑to‑roll lines and OEM relationships. Strategic signal: track cell qualification timelines with automotive partners and volume commitments from OEMs.
- Greater Bay Technology (China) — Strengths: recently rolled out A‑sample cells with robust energy density claims and safety testing milestones. Strategic signal: rapid domestic validation and local vehicle installation targets indicate China will be an early high‑volume market.
- ProLogium Technology (Taiwan) — Strengths: oxide ceramic‑based approach and gigafactory partnerships with OEMs. Strategic signal: roll‑to‑roll manufacturing partnerships with large automakers can shorten commercialization cycles for selected architectures.
- Ilika plc (UK) — Strengths: focused pilot production for electric mobility; small‑scale, high‑value applications can provide early cash flows and validation opportunities.
- Samsung SDI (Korea) — Strengths: established battery manufacturing capability and a stated target to move to mass production in the coming cycle. Strategic signal: incumbent cell producers with existing OEM relationships can leverage scale and system integration expertise to accelerate adoption.
- Toyota Motor Corporation (Japan) — Strengths: deep vehicle integration capability, regulatory approvals, and partnerships for sulfide electrolyte supply. Strategic signal: OEMs that own or control key elements of the stack can shape standards, safety protocols, and supplier ecosystems.
Report content — practical deliverables
Our full ASSB market study is built for commercial use and includes the following operational modules (excerpt):
- Integrated market model (2020–2032) with scenario‑sensitive forecasts and sensitivity levers for yield, cost, and adoption timing.
- Technology readiness roadmap and comparative TRL/CRL (technology and commercialization readiness level) analysis across electrolyte and anode chemistries.
- Supply‑chain maps and risk heatmaps highlighting material intensity, processing choke points and contingency sourcing strategies.
- Manufacturing playbooks covering pilot line KPIs, ramp‑ratio scenarios, CAPEX build profiles and yield‑improvement benchmarks.
- Company dossiers with strategic SWOTs, partnership architectures, and likely go‑to‑market pathways for the major technology owners and incumbents.
- Regulatory and standards tracker with compliance checklists, certification timelines and key policy decision points by jurisdiction.
- M&A and alliance target lists with commercial match‑making matrices and negotiation clout estimators.
Note: the report contains granular regional and application splits, proprietary price and volume curves, and downloadable model files. These detailed subsegment outputs are maintained behind our client portal to preserve competitive value and are intentionally summarized here to direct stakeholders to the full deliverable.
Actionable recommendations for 2026 decisions
- Near term (0–12 months): Conduct material supply audits, secure strategic offtake contracts, initiate pilot validations with at least two cell technology partners, and join standards working groups to influence test protocols.
- Medium term (12–36 months): Structure modular CAPEX plans, negotiate licensing terms that preserve optionality, and develop cross‑border logistics playbooks for critical electrolyte supply.
- Longer term (36+ months): Decide on vertical integration versus partner‑based models based on pilot yields and regulatory alignment; prepare for second‑wave scaling contingent on yield and cost breakpoints.
How PW Consulting can help
We support manufacturers, OEMs, investors and governments with tailored advisory across commercial due diligence, site selection, joint‑venture structuring, and regulatory strategy. Our engagements combine the forecast models and risk frameworks from this report with hands‑on negotiation support and technical validation protocols to accelerate safe, commercially viable launches.
To access the full market model, subsegment breakdowns, proprietary supplier scoring and executable playbooks — including downloadable financial templates and scenario models — visit our report page or contact PW Consulting for a briefing. The granular insights required to convert pilot progress into profitable industrial capacity are in the full report; this preview outlines the strategic levers and decision points that will define success in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: All-Solid-State Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: OBD Telematics to Hit USD 1,190M by 2032 at 11.4% CAGR
By pmarketresearch, 2026-07-08
OBD Telematics Market 2026: Strategic Imperatives for Decision-Makers
As PW Consulting’s Senior Strategy Consultant and Chief Industry Analyst, I present a concise yet rigorous framing of the OBD telematics market and the decisions it forces on corporate leaders in 2026. This article previews the actionable intelligence and scenario-grade foresight you will find in our full market study. We surface the levers that matter for strategy, highlight the competitive movements reshaping the landscape, and signal the regulatory and technical traps that separate winners from stragglers — while deliberately reserving the granular segment-level tables that are available in the full report.
OBD Telematics Market
Market trajectory: why this is a critical moment
Between 2020 and 2025 the OBD telematics market expanded substantially, and our model — anchored to a 2025 base year — projects sustained, double-digit growth through the coming decade. Concretely, the market rose from a mid-three-hundred million USD base in 2020 to roughly USD 580.0 Million by 2025; under the central-case scenario the market is forecast to reach about USD 1,190.0 Million by 2032, representing an approximate compound annual growth rate (CAGR) of 11.4% across the forecast window.
OBD Telematics Market
Those headline dynamics make clear two strategic implications for 2026: (1) this is no longer a niche retrofit play — it is a scale market where platform economics, data strategies, and regulatory compliance will materially determine margin capture; and (2) timing matters: near-term investments in integration and product modularity will compound into substantial strategic advantage as adoption accelerates.
OBD Telematics Market
What the full report delivers — practical, board-level tools
- Proven market sizing and forecasting model (base year 2025) with scenario toggles (conservative / central / accelerated) so executives can stress-test investment cases under alternate macro and regulatory assumptions.
- Decision-oriented playbooks: M&A screening criteria, partnership frameworks, and go-to-market sequencing for carriers, OEMs, fleet operators, insurers, and aftermarket vendors.
- Competitive scorecards and supplier maturity maps that rank product, platform, data, and service capabilities across the vendor set — enabling prioritized vendor shortlists for pilots and procurements.
- Technology architecture blueprints (hardware + edge compute + cloud + APIs), TCO templates, and integration checklists for OEM-connected and retrofit strategies.
- Regulatory compliance matrix and risk heatmap including emission diagnostics standards, regional tamper/anti-tampering policies, and practical actions for legal mitigation.
- Commercial models for subscription pricing, hardware-as-a-service, and data monetization scenarios, including sensitivity analysis for churn, ARPU, and device lifecycle costs.
The above are built to be operational: CFOs get ROI calculators; CTOs get integration milestones and bill-of-materials inputs; business development leaders get partner scorecards and negotiation levers.
Competitive landscape — categories, capabilities, and recent shifts
The market sits at the intersection of device OEMs, telematics platform providers, fleet management specialists, and systems integrators. Market concentration metrics indicate a market that is neither a monopoly nor highly fragmented — the top three players capture a meaningful share of revenue, and the top five together control a clear majority. That concentration creates an environment where scale-driven platform advantages and established channel relationships materially affect entrant economics.
- Device-first leaders (e.g., Geotab, CalAmp, Xirgo): These firms anchor their value with robust, field-proven OBD-II hardware and iterative firmware improvements. Recent product updates show a push to higher compute at the edge (faster processors, more memory, IMU/gyro sensors) to support richer telemetry and local pre-processing. Expect device vendors to emphasize plug-and-play reliability, rapid OTA capability, and expanded sensor fusion as differentiators.
- Platform and software integrators (e.g., Samsara, Verizon Connect, Mojio, Danlaw): Platform providers compete on analytics depth, ease of integrations, and verticalized workflows (fleet ops, insurance telematics, maintenance scheduling). Their winning plays emphasize API ecosystems and purpose-built apps, plus bundling of AI-enabled driver safety features with diagnostics and maintenance workflows.
- Tier-1 automotive suppliers (e.g., Continental, Robert Bosch): These incumbents bridge OEM-grade engineering with telematics services for commercial vehicle OEMs and large fleets. Their strength lies in deep vehicle systems integration, regulatory know-how, and scale manufacturing — making them natural partners for OEM-first strategies and for fleets requiring high-assurance solutions.
- Specialists and IP licensors (e.g., OBD Experts): Companies that own protocol stacks, software toolkits, and diagnostic IP are increasingly valuable as telematics systems decouple into hardware, software stacks, and cloud platforms. Licensing and co-development are growing engagement pathways.
Notable near-term events illustrate shifting competitive dynamics: a major device vendor announced next‑generation hardware with increased processing and sensing capability, and that same vendor has deepened OEM integrations allowing mixed-fleet analytics without wholesale hardware retrofits. Separately, OEMs have begun offering cloud-based diagnostic access to third parties—an inflection that alters the retrofit economics for some use cases. These trends increase the value of flexible integration strategies that can span both OBD plug-in and OEM-native data channels.
Market dynamics and regulatory friction points
- Standards and harmonization: ISO-level diagnostic frameworks are progressing, creating clearer expectations for interoperability of diagnostic services across platforms. Companies that design to harmonized standards reduce integration friction and accelerate fleet rollouts.
- Compliance and anti-tampering: Jurisdictional rules around aftermarket installations and port relocation are evolving. Some regulatory pathways explicitly exempt certain aftermarket solutions when compliance is demonstrable, meaning a regulatory-savvy compliance program is a market enabler rather than a cost center.
- OEM data access: Direct cloud access to vehicle diagnostic data by OEMs changes the retrofit calculus. In some fleets, OEM-provided telematics will obviate the need for plug‑in devices; in others, retrofits remain the fastest path to uniform data across mixed fleets. A hybrid strategy is therefore a practical necessity for many enterprise buyers.
- Legal and policy volatility: Shifts in how key communications services are regulated can affect connectivity economics and service provider contracts. Firms must build contractual flexibility and alternative connectivity plans into multi‑year procurement agreements.
- Cybersecurity and privacy: As device compute and data aggregation increase, so does the attack surface. Security-by-design, certificate management, and privacy-preserving analytic patterns are now procurement table stakes.
Recommended 2026 strategic playbook
For executive teams deciding where to place bets in 2026, we recommend a balanced portfolio approach that combines near-term commercial expansion with mid-term architectural positioning:
- Prioritize integration breadth: Build dual-path data ingestion capabilities — OEM APIs and OBD plug-in — so you can serve both greenfield OEM-aligned clients and retrofit-heavy mixed fleets.
- Invest in modular hardware and edge intelligence: New device generations reward local preprocessing (reducing connectivity costs), richer sensor fusion, and OTA flexibility. Plan hardware roadmaps that decouple compute from radio and sensor modules to shorten update cycles.
- Productize outcomes not just telemetry: Customers buy reduced downtime, lower fuel spend, and lower insurance loss ratios. Translate raw diagnostic streams into verticalized outcomes (predictive maintenance, fuel optimization, safety scoring) with clear KPIs, SLAs, and ROI proofs.
- Make compliance a commercial differentiator: Be prepared to demonstrate standards conformance and anti-tampering mitigation — in some markets this accelerates procurement approval and reduces installation friction.
- Use M&A tactically: Target acquisitions that close gaps in API access, enrich data assets, or embed you into critical fleet workflows. Small bolt-on buys can be more accretive than capex-heavy greenfield buildouts.
- Run staged pilots with measurable gates: Short, KPI-driven pilots that move to commercial rollouts on clear success criteria keep deployments low-risk and fundable.
- Lock in long-term partnerships with connectivity and cloud providers: Negotiate flexible connectivity packages and cloud compute commitments that tolerate volatility in data volumes and regulation.
How to use the full PW Consulting study
This article previews the strategic framing, competitive nuances, and practical playbooks you need to act in 2026. The full OBD Telematics Market report supplies the missing operational detail — including the granular regional, application, and product splits; interactive forecast models; supplier-by-feature scoring; and downloadable financial templates. Those tables and segment-level breakdowns are intentionally reserved for the full study because they are the inputs CFOs and corporate strategy teams will plug directly into investment memos and board materials.
If your 2026 capital allocation, product roadmap, partnership strategy, or M&A pipeline intersects with connected vehicle data, the full report (with its scenario models, vendor diagnostics, and compliance checklists) will materially shorten your decision cycle and reduce execution risk. In a market growing at an approximate 11.4% CAGR from our 2025 base, the decisions you make this year about integrations, hardware roadmaps, and regulatory positioning will define revenue capture and margin trajectory for the next five years.
PW Consulting — Senior Strategy Consultant & Chief Industry Analyst
For detailed analysis of this topic, please visit the official page: OBD Telematics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 25G Optical Chip Market Set to Reach USD 2.9 Billion by 2032, Expanding at a 7.5% CAGR
By pmarketresearch, 2026-07-07
PW Consulting Strategic Brief: 25G Optical Chip Market — What Every Executive Must Know Heading into 2026
As demand for higher bandwidth and lower latency accelerates across cloud, carrier and edge networks, 25G optical chipsets have moved from a tactical upgrade to a strategic infrastructure decision. PW Consulting’s latest market study (base year 2025; historical series 2020–2025; forecast 2026–2032) provides executives with the foresight and practical toolset needed to make high-stakes procurement, investment and partnership decisions in 2026. The global 25G optical chip market, having grown from roughly 1,225 Million USD in 2020 to 1,750 Million USD in 2025, is projected to expand at a compound annual growth rate (CAGR) of 7.5% over the 2026–2032 forecast window, reaching approximately 2,903 Million USD by 2032.
25G Optical Chip Market
Why 25G Is a Strategic Inflection Point in 2026
-
Cost-per-bit economics: As hyperscalers and carriers balance capex and operational power budgets, 25G solutions offer an attractive inflection between legacy 10G links and emerging 50/100G architectures. The near-term optimization of link speeds, power envelope and module complexity is now central to network architecture decisions.
25G Optical Chip Market -
Demand tailwinds from cloud and 5G: Continued densification of data center fabrics and 5G fronthaul/midhaul upgrades underpin steady demand growth, while new enterprise and industrial optical use cases are expanding non-traditional adoption vectors.
25G Optical Chip Market -
Supply-side constraints and bottlenecks: Our sector supply-chain workstream finds leading producers of critical 25G laser technologies (EML/CW) operating near full utilization, with backlogs extending beyond two years at top suppliers. Alongside this, precision optical subcomponents and advanced packaging—areas concentrated in a few geographies—represent persistent bottlenecks that materially influence time-to-market and margin realization.
-
Standards and interoperability: Industry bodies such as the OIF are actively publishing interoperability metrics and test frameworks relevant to 25G and higher interfaces. Companies that align early to these specifications will shorten qualification cycles and reduce field failures.
-
Geopolitical and regulatory risk: Export controls and regional tensions are increasing the cost and complexity of resilient sourcing strategies. For organizations with global footprints, supplier diversification and near-shore contingency plans are no longer optional.
What PW Consulting’s 25G Report Delivers — Practical, Executable Outputs
This is not a high-level narrative. The report was built for decision-makers who must convert insight into action in 2026. Key practical deliverables include:
-
Transparent market-sizing and forecasting methodology — reproducible models that trace demand drivers, adoption timelines and unit economics across the 2026–2032 horizon.
-
A buyer’s playbook — procurement frameworks for tendering, long-term contracting templates, supplier qualification checklists and negotiation levers tailored to optical chip supply dynamics.
-
Supplier benchmarking and risk scoring — a multi-dimensional scorecard covering technology depth, capacity posture, geographic concentration, qualification lead times and commercial flexibility.
-
Technology trade-off matrices — side-by-side evaluation of laser types and photodetector approaches aligned to reach, power, cost and manufacturability trade-offs to support SKU rationalization or new product definition.
-
CapEx and supply-chain scenario tools — sensitivity models that quantify the impact of capacity constraints, material shortages and tariff/embargo scenarios on unit cost, lead time and margin.
-
M&A and partnership screening playbooks — criteria and valuation heuristics for bolt-on acquisitions, joint development agreements and foundry partnerships.
-
Field qualification acceleration templates — test-plan blueprints, interoperability checkpoints, and sample size recommendations to compress qualification cycles without increasing rollout risk.
-
Executive dashboard — a one-page impact summary linking macro forecasts, supplier exposure and recommended 90/180/360-day actions to support board-level decisions in 2026.
Competitive Landscape — Who Matters and Why
The 25G supplier ecosystem combines multi-national incumbents with regional specialists. Market concentration remains meaningful: our CR3 and CR5 metrics indicate a moderately consolidated market (CR3 approximately 38.5%, CR5 approximately 52.2%), which has direct implications for bargaining power, availability and strategic partnership choices.
-
MACOM — Strong in DFB laser diodes optimized for direct modulation and uncooled operation; well-positioned for 5G fronthaul and certain data-center link designs. Their continued presence at leading industry forums signals an emphasis on product-portfolio depth and channel engagement.
-
Lumentum — A leader in InP EMLs and wafer-foundry capabilities. For buyers requiring high-performance long-reach or temperature-stable modules, Lumentum’s vertically integrated supply model shortens lead times but can command premium commercial terms.
-
Broadcom — Deep integration with data center networking ecosystems and expertise in VCSEL and laser link technologies. Broadcom’s platform position makes it a preferred partner for OEMs seeking tight hardware-software co-optimization.
-
Coherent Corp. (formerly II-VI / Finisar) — Broad portfolio across transceivers and lasers, substantial manufacturing footprint and a track record of rapid scale-up for telecom and datacom segments. Their channel reach supports rapid qualification for large customers.
-
Accelink, InnoLight, GLSUN — Regional champions with strong manufacturability and competitive cost positions for mainstream 25G modules. For firms seeking supply affordability and scale in Asia, these players are critical but require careful qualification and IP diligence.
-
NEC Corporation — Notable for recent product launches in 2025 that extend reach and bidirectional transmission capabilities, demonstrating an emphasis on enabling low-power upgrades from legacy systems. NEC’s portfolio can be attractive for operators managing phased migration strategies.
Recent Market Signals that Change the Playbook
-
Product launches in 2025 from established players (including extended-reach and BiDi transceivers) show a push to capture migration spend from 10G to 25G while minimizing infrastructure changes.
-
Supply-chain reports in 2026 flag near-full utilization for certain laser technologies and multi-year backlogs at leading fabs — a clear signal that procurement cycles and multi-source strategies must be planned well in advance.
-
Standardization work from industry forums is reducing interoperability risk, enabling faster time-to-deployment for vendors that conform early to published test matrices.
-
Geopolitical pressure on advanced packaging and certain substrate materials is prompting buyers to quantify nationality-of-origin risk and to consider near-shoreized capabilities as part of resilience planning.
Scenario Planning: What to Watch in 2026
Our report presents three pragmatic scenarios with trigger-based actions:
-
Baseline (CAGR 7.5%): Steady adoption driven by cloud and 5G, with supply-side frictions managed via longer lead times and prioritized allocation. Recommended action: secure rolling 12–24 month supply agreements with pricing floors tied to clear volume bands.
-
Accelerated adoption: If AI-driven interconnect density or a faster-than-expected 5G upgrade cycle materializes, demand could outstrip forecasted capacity in 2026–2027. Recommended action: fast-track strategic investments in capacity co-funding or exclusive short-term supply arrangements.
-
Constrained supply / geopolitical disruption: Material export controls or a packaging shortage could create sharp localized shortages and price volatility. Recommended action: activate dual-sourcing playbooks, release buffer inventory thresholds and reassign critical traffic to alternative top-of-rack architectures temporarily.
Immediate 90-Day Actions for 2026
-
Run supplier exposure mapping against the report’s supplier scorecards to identify single-source risks and prioritize dual-qualification of at least two alternative vendors for every critical optical chip family.
-
Initiate joint forecasting cadences with strategic suppliers to secure allocation and to reduce market-driven lead-time variability.
-
Embed interoperability test requirements into procurement contracts, referencing OIF-aligned test metrics to accelerate rollouts and reduce integration cost overruns.
-
Model short-term capex for modular assembly or localized packaging to hedge against near-term supply-chain disruptions where unit economics justify the investment.
Conclusion — The Strategic Value of PW Consulting’s 25G Study
Entering 2026, the 25G optical chip market presents a composite opportunity: strong and steady market growth (7.5% CAGR to 2032) alongside real operational risks rooted in supply concentration, component bottlenecks and evolving standards. PW Consulting’s 25G report translates these macro dynamics into executable commercial playbooks, supplier-risk tools and scenario models. It is designed for procurement chiefs, product leaders, CTOs and corporate strategists who must convert market forecasts into defensible, time-sensitive decisions.
To access the full dataset, proprietary supplier scorecards, interactive scenario models and the actionable templates referenced in this brief, please visit the PW Consulting report page or reach out to our industry team for a tailored executive briefing.
For detailed analysis of this topic, please visit the official page: 25G Optical Chip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Metaverse in Manufacturing Market Poised to Grow at a 28.5% CAGR, Revolutionizing Factory Operations
By pmarketresearch, 2026-07-07
Metaverse in Manufacturing Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
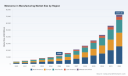
As manufacturers shift from exploratory pilots to enterprise-grade deployments, the industrial metaverse is transitioning from blue-sky promise to boardroom priority. Our new PW Consulting report — Metaverse in Manufacturing Market (base year 2025) — synthesizes five years of historical market movement and a seven-year forecast to deliver actionable guidance for executives planning 2026 investments. The market has expanded rapidly (from a small base in 2020 to approximately USD 12.5 billion in 2025) and is projected to continue at a double‑digit pace (CAGR 28.5%), reaching well into the tens of billions by the early 2030s. This brief highlights the strategic value of the full report for decision-makers while preserving the proprietary segmentation detail contained in the complete study.
Metaverse In Manufacturing Market
Why this report matters for 2026 decisions
-
Timing: 2026 is the inflection point where infrastructure readiness (GPU compute, real‑time physics engines), standards convergence, and vendor maturity align to enable scalable industrial metaverse deployments. Our forecast shows meaningful market acceleration in 2026, making the next 12–18 months decisive for capability-building versus vendor lock‑in.
Metaverse In Manufacturing Market -
Risk‑to‑reward optimization: The report provides a structured approach to prioritize proofs‑of‑value that de‑risk full-scale rollouts. We map tactical pilots to enterprise objectives (throughput improvement, downtime reduction, time‑to‑market compression) and quantify investment horizons so leaders can make defensible capital allocation decisions in 2026.
Metaverse In Manufacturing Market -
Vendor and ecosystem plays: Rapid strategic partnerships and platform integrations from major technology vendors are reshaping procurement choices. Our analysis reveals how platform-led alliances and open‑standards adoption will determine integration cost and future optionality—key considerations for procurement teams and CIOs evaluating 2026 roadmaps.
High‑level market dynamics (what the numbers tell us)
The industrial metaverse market has moved beyond isolated proofs and is now scaling across manufacturing value chains. Growth across 2020–2025 demonstrates strong market validation; the forecast period (2026–2032) reflects continued compound growth driven by three structural forces: (1) persistent productivity pressure across manufacturing tiers, (2) maturity of real‑time 3D and physics simulation platforms, and (3) expanding enterprise adoption of AI‑enabled digital twins. While we intentionally withhold detailed splits in this summary, the full report dissects demand by technology families, application clusters and regional adoption patterns to help leaders prioritize 2026 investments.
Practical, decision‑ready content in the full report
-
Actionable adoption playbooks: End‑to‑end pilot templates for manufacturing use cases (e.g., digital twin simulation, immersive training, collaborative product development, remote maintenance) that specify scope, success metrics, data requirements, tooling, and sample budgets tailored for 2026 procurement cycles.
-
Vendor evaluation matrix: A comparative framework that evaluates platform providers across technology maturity, integration readiness, partner ecosystems, compute dependency and commercial models—designed to accelerate vendor shortlisting without requiring proprietary RFP redesign.
-
Integration & infrastructure blueprint: Guidance on hybrid cloud/edge architectures, high‑performance GPU requirements, real‑time synchronization, security and data governance patterns that are important for scaling from pilot to plant‑wide deployments.
-
ROI and total cost of ownership models: Financial templates and sensitivity analyses that quantify productivity, uptime and training cost benefits under conservative, mid and aggressive adoption scenarios so CFOs can compare metaverse investments against alternate digitalization projects.
-
Change management and workforce pathways: Practical programs to re‑skill frontline workers, integrate metaverse workflows into standard operating procedures, and design governance for cross‑discipline collaboration between IT, OT and engineering functions.
Competitive landscape — platform makers, system integrators and industrial champions
The competitive picture is evolving fast. Leading platform vendors and industrial incumbents are moving beyond standalone products to ecosystem plays, combining real‑time 3D engines, simulation cores, and industrial IT integration.
-
Siemens AG (Munich) is positioning its Xcelerator suite and new Digital Twin Composer (announced for broader availability in 2026) as a backbone for large‑scale, physics‑based factory digital twins. Siemens’ strategy emphasizes lifecycle integration from planning through adaptive manufacturing—targeting customers that need enterprise coherence across engineering and operations.
-
NVIDIA Corporation (Santa Clara) has catalyzed an industrial metaverse stack through Omniverse, focusing on photorealistic, physics‑accurate real‑time simulation and GPU performance. Recent 2026 partnership activity underscores NVIDIA’s role as the computational platform enabler and a convenor of industrial software partners.
-
Dassault Systèmes (France) leverages 3DEXPERIENCE for virtual twins and immersive collaboration, emphasizing design‑to‑manufacture continuity and spatial computing partnerships—appealing to complex engineering organizations.
-
PTC Inc. (Boston) brings AR/MR and the digital thread narrative, with Vuforia and integrated lifecycle capabilities that suit manufacturers seeking rapid field‑worker augmentation and traceable change management.
-
Microsoft Corporation (Redmond) combines Mesh and HoloLens for collaborative use cases at scale, offering cloud and identity services that can simplify enterprise deployment, especially for companies already standardized on Microsoft stacks.
-
Unity Technologies (San Francisco) provides a developer‑friendly real‑time 3D engine tuned for simulation and training, attractive to teams requiring high‑fidelity interactions and rapid content iteration.
-
ABB Ltd (Zurich) is integrating robotics, AI and digital twins to deliver practical, plant‑level solutions—particularly where automation hardware and process control converge.
These vendors are not discrete choices but nodes in an ecosystem. The most successful industrial metaverse deployments in our study combine platform integrators with domain specialists and hardware suppliers. Recent product announcements and partnerships during late 2025 and early 2026 underscore a move toward interoperable stacks and co‑innovation engagements, with several platform vendors seeking industrial anchor customers to validate scale and operational governance models.
Standards, regulation and infrastructure — the backbone of scale
-
Standards activity is accelerating. Bodies such as IEEE, IEC and ISO are advancing terminology, multimedia guidance, and digital twin interoperability specifications that will materially lower integration friction as they are codified. Executives should plan for compliance and interoperability testing as part of 2026 project definitions.
-
Infrastructure constraints—primarily high‑performance GPU compute and real‑time physics simulation—remain the principal technical gating factor for large‑scale, multi‑site deployments. Strategic vendor collaborations that combine platform software with specialized compute and edge orchestration are emerging as the pragmatic path to manage cost and latency.
How to use this report in your 2026 planning cycle
-
Prioritize pilot objectives by business value: Use the report’s ROI models to rank use cases and sequence pilots that deliver immediate operational benefits while preserving future integration flexibility.
-
Design procurements for modularity: Tender for interoperable building blocks (simulation engine, digital twin ontology, synchronization layer, edge compute) rather than monolithic solutions to avoid vendor lock‑in during the nascent phase of standards convergence.
-
Invest in internal capability accelerators: Establish cross‑functional metaverse centers of excellence and partner with neutral system integrators to compress the learning curve and capture reuse across facilities.
-
Govern for safety and IP: Formalize data governance, security baselines and IP frameworks early—these disciplines materially affect speed of adoption and contractual exposure when moving from pilot to production.
Final note — what to expect from the full intelligence package
This press brief maps the strategic landscape and identifies the decision levers that should shape 2026 programs. The full PW Consulting report contains the granular vendor scoring, use‑case financials, deployment playbooks and an interactive decision toolkit that senior leaders and program managers will find indispensable for operationalizing industrial metaverse strategies. To preserve competitive value for our clients, we intentionally reserve the core segmentation tables and proprietary scenario models for the complete report.
Access the full Metaverse in Manufacturing Market report and the executive toolkit on PW Consulting’s report portal to get the detailed breakdowns, vendor matrices and implementation templates you need to move from pilot to production in 2026.
For detailed analysis of this topic, please visit the official page: Metaverse In Manufacturing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Optical Circuit Switches Market Poised to Expand at a 20.5% CAGR Through 2032
By pmarketresearch, 2026-07-07
Optical Circuit Switches (OCS) Market: Strategic Imperatives for 2026 — PW Consulting
PW Consulting’s newly released market study on Optical Circuit Switches (OCS) is built to inform the strategic choices that will define networking architectures across AI-driven and hyperscale infrastructures in 2026. Using 2025 as the base year, the study traces the market’s rapid expansion from an estimated USD 295.2 million in 2020 to USD 750.0 million in 2025 and models a high-growth trajectory through a 2026–2032 forecast window. At a compound annual growth rate (CAGR) of 20.5%, the OCS market is projected to reach roughly USD 2.77 billion by 2032—evidence of a technology moving from niche experiment to core fabric for large-scale computing.
Optical Circuit Switches Ocs Market
Why this matters for enterprise decision‑makers in 2026
-
Acceleration of AI workloads. The intensity and topology of AI training and inference are reshaping how interconnects are specified and evaluated. OCS promises protocol-agnostic, low-power, and low-latency optical fabrics that can displace or complement electrical switching in rack- and pod-level fabrics.
Optical Circuit Switches Ocs Market -
Capital and operating trade-offs. With electricity costs and cooling now a fundamental line-item for data center operators—electricity can represent roughly 40% of a large data center’s operating budget—OCS offers an efficiency lever that materially affects TCO modeling and site selection decisions.
Optical Circuit Switches Ocs Market -
Standards and interoperability. Industry projects such as the Open Compute Project’s OCS sub-project are maturing the ecosystem’s ability to integrate multi-vendor optical fabrics at scale—making standards roadmaps a procurement risk to manage in 2026.
-
Regulatory dynamics. Regional policy moves (for example, rules that tie grid access to renewable sourcing) change the economics of new deployments and shift the relative value of power‑efficient network technologies.
What the PW Consulting report delivers (practical, implementable content)
-
Executive playbooks that translate OCS capability into procurement requirements, KPI scorecards, and test plans for lab and field pilots.
-
Scenario-based TCO and ROI models (capex, opex, energy, and latency trade-offs) calibrated to multiple deployment archetypes, from hyperscale GPU clusters to enterprise AI pods.
-
A vendor selection framework and due-diligence checklist covering manufacturability, roadmap transparency, serviceability, and integration risk.
-
Integration blueprints showing common staging, orchestration, and failure-domain strategies for combining optical switching with existing electrical fabrics.
-
Regulatory and energy-impact matrices that map near-term policy risks and utility constraints against deployment timetables and site strategy.
-
Supply chain and sourcing playbooks, including contract negotiation levers and strategies to mitigate single-sourced components or long lead times.
Competitive landscape: who matters (concise profiles and implications)
-
Lumentum Holdings Inc. (San Jose) — A leading MEMS-based OCS supplier with high-radix products targeted at AI/cloud fabrics. Lumentum’s R300 and R64 offerings position it as a partner for rack-level integration and low-power interconnect strategies.
-
Coherent Corp. (Saxonburg) — Provides liquid crystal (LCoS) OCS platforms targeted at low-latency, reliable switching suited to AI data center architectures where deterministic behaviour matters.
-
Molex (Lisle) — Advancing high-radix MEMS platforms with roadmaps to exceed 500+ port matrices, signaling intent to serve hyperscalers needing very large, reconfigurable fabrics.
-
DiCon Fiberoptics (Richmond) — Focuses on value-tier MEMS OCS models with proven reliability and low insertion loss—an option for operators balancing cost and performance.
-
HUBER+SUHNER Polatis (Swiss) — Offers beam-steering all-optical platforms for larger matrices and automation-focused hyperscale deployments.
-
Telescent Inc. (Irvine) — Specializes in robotic all-fiber switching and automated patching for very high fiber-count reconfiguration, attractive for environments prioritizing minimal optical loss.
-
Calient.AI (Calient Technologies) — Delivers MEMS-based all-optical systems aimed at dynamic interconnects for test automation and scalable data center fabrics.
-
iPronics (Valencia) — Silicon photonics approach to programmable OCS, offering low-power, low-latency alternatives that could influence future dense integration strategies.
-
Omnitron Sensors — Supplies core MEMS mirror technology that enables very high channel counts for hyperscale applications.
Our analysis finds the vendor landscape to be consolidated around a few firms with differentiated technology bets—MEMS, liquid crystal (LCoS), silicon photonics, and robotic all-fiber systems—each carrying distinct integration, cost, and roadmap implications.
Recent industry moves and near-term implications
-
March 2026 product launches by multiple vendors signaled a readiness to commercialize higher‑radix and value-focused systems. These introductions compress the product‑validation timeline for adopters considering 2026 pilot programs.
-
Live system demonstrations with optics and OCS vendors at industry events (e.g., rack-level integrations showcased in early 2026) confirm that vendors are moving from component to system delivery models—heightening the importance of systems integration capability in procurement criteria.
-
Partnerships to manufacture PIC-based OCS using silicon photonics indicate a maturing supply chain for integrated photonics, which can drive down power and increase switch programmability but requires new validation processes.
Five priority actions for leaders planning OCS adoption in 2026
-
Run staged pilots with clear success gates. Design experiments that isolate energy, latency, and manageability metrics. Use lab pilots to validate failure modes, orchestration hooks, and maintenance cycles before fleet-wide rollouts.
-
Insist on integration and service SLAs. As vendors transition to system-level offers, contractual clarity on software APIs, firmware update paths, and spares provisioning will materially reduce operational risk.
-
Model energy and site risks explicitly. Incorporate forward-looking utility and regulatory scenarios into capex scheduling—energy efficiency gains from OCS can be materially devalued or amplified by regional grid access rules and renewable sourcing mandates.
-
Prioritize standards alignment. Participation in OCP and similar interoperability efforts is now a procurement consideration: prefer vendors with clear conformance roadmaps and open API strategies.
-
Plan for multi-technology fabrics. Expect hybrid deployments—electrical switching where cost or latency profiles favor it; optical circuit switching where high‑radix, low‑power reconfiguration is critical. Design orchestration layers that abstract these choices.
Study methodology and market posture
The PW Consulting study uses a base year of 2025 with historical analysis spanning 2020–2025 and a forecast window of 2026–2032. Market sizing is expressed in USD (Million) and incorporates vendor shipment data, supplier roadmaps, price erosion curves, and scenario-based adoption timelines for hyperscale and enterprise segments. While this executive summary highlights the overall market trajectory and strategic consequences, the full report contains detailed segmentation, pricing ladders, vendor scorecards, and regional adoption models (note: granular segment figures are intentionally withheld from this summary to preserve commercial sensitivity and to encourage direct engagement with the report).
How to use the full report
Leaders evaluating OCS for 2026 project planning should use the full report to: (1) quantify site‑level TCO impact across realistic deployment timelines; (2) identify vendor risk and integration readiness; (3) construct procurement RFPs and test acceptance criteria; and (4) map regulatory and energy constraints against expansion roadmaps. For teams that need to move from evaluation to execution within 12 months, the report includes templated RFP language, lab test scripts, and a procurement negotiation playbook.
PW Consulting’s OCS market study is designed as a decision‑acceleration tool: it surfaces the structural drivers, commercial players, and practical implementation levers that will determine winners and losers in next‑generation data center fabrics. For access to the complete dataset, detailed segmentation, and interactive TCO models, visit the official report page or contact PW Consulting to schedule a briefing and custom drilldown session.
For detailed analysis of this topic, please visit the official page: Optical Circuit Switches Ocs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aerial Inspections Market to Expand at 13.5% CAGR, Rising from USD 14,500M in 2025 to USD 35,183.5M by 2032 — UAV & Drone Services Lead with USD 9,383.6M
By pmarketresearch, 2026-07-07
Aerial Inspections Service Market: Strategic Outlook for 2026 Decisions
PW Consulting’s latest market research—built on a 2025 base year and a 2026–2032 forecast horizon—provides decision-grade intelligence for executives who must act in 2026. The Global Aerial Inspections Service Market has more than doubled in five years, rising from approximately USD 7.45 billion in 2020 to USD 14.5 billion in 2025, and is projected to continue at a robust compound annual growth rate (CAGR) of 13.5% through 2032, reaching roughly USD 35.2 billion by the end of the forecast period. This growth trajectory is reshaping capital allocation, procurement strategies, and technology roadmaps across energy, utilities, infrastructure, and industrial verticals.
Aerial Inspections Service Market
Why this report matters for 2026
- Actionable timing: 2026 is the inflection year for several regulatory and operational changes—FAA initiatives on BVLOS, new enforcement pathways, and accelerated platform capability releases—that will materially affect implementation feasibility and unit economics.
- Investment prioritization: With a predictable macro growth rate, boards and strategy teams must distinguish between platform play, service scale, and analytics-first propositions; the report provides prioritization frameworks tuned for 2026 budgeting cycles.
- Procurement clarity: Buyers face a fragmented supplier landscape. Our work decodes vendor capabilities into procurement-ready criteria so buyers can reduce time-to-deployment while managing risk.
Market trajectory and macro drivers
The market’s acceleration is driven by a confluence of forces: sensor miniaturization and multispectral maturity, cloud-native data management, AI analytics for anomaly detection, and cost-justifying returns on safety and operational uptime. The report quantifies the historical run-rate (2020–2025) and projects forward under multiple regulatory and technology adoption scenarios for 2026–2032. At the aggregate level, stakeholders should plan against a central case CAGR of 13.5% while stress-testing portfolios against faster automated BVLOS adoption and slower regulatory approvals.
Aerial Inspections Service Market
Operational economics continue to favor aerial approaches: industry benchmarking indicates drone-based industrial inspections can reduce operating costs by 30–70% and compress inspection time by 75–85% relative to traditional rope-access or scaffold-based methods. Those savings, combined with improved inspection cadence and data repeatability, are the primary levers feeding ROI models in our financial templates.
Aerial Inspections Service Market
Competitive landscape — what to watch in 2026
The market remains lightly concentrated (CR3 ≈ 22.5%, CR5 ≈ 31.4%), indicating a vibrant ecosystem where differentiated capability—software platforms, specialized vertical expertise, and integrated data services—matters more than scale alone. Key provider archetypes and representative players covered in the report include:
- Platform-centric leaders: Companies offering end-to-end data platforms and analytics (e.g., DroneDeploy) are pushing enterprise standardization through software features, strategic partnerships, and faster capture-to-insight times.
- Vertical specialists: Firms focused on wind, solar, or LNG (e.g., SkySpecs for wind blade autonomy; Raptor Maps for solar analytics; Cyberhawk for energy-sector operations) continue to capture premium pricing through domain-specific IP and regulatory know-how.
- Global operators: Providers with geographically distributed service delivery and local regulatory footprints (e.g., Terra Drone) are converting multinational maintenance contracts into multi-year recurring revenue.
- Integrated service firms: Surveying and LiDAR specialists (e.g., SAM) and enterprise drone integrators (e.g., Measure) are combining hardware, geospatial engineering, and data pipelines to serve infrastructure and utilities customers.
Recent visible moves emphasize the market’s dual track: platform enhancement and enterprise partnerships. Notable developments tracked in the report include a multi-year expansion of DroneDeploy’s enterprise footprint with large construction clients and sequential software releases that significantly improve capture performance and BIM integration; Cyberhawk’s contract extensions in energy markets; and new offshore-focused divisions launched to address subsea and maritime inspection needs. These transactions and product cycles signal that 2026 procurement conversations will center not only on flight capability but on enterprise-scale data flows and long-term SLAs.
What the report contains — practical, implementable content
Beyond headline sizing and competitive maps, the report is organized to be operational from day one. Highlights include:
- Deployment playbooks: step-by-step templates for internal pilots, scale-up, and integration with existing maintenance management systems (CMMS/EAM).
- Procurement and vendor-selection frameworks: weighted criteria matrices covering safety compliance, data fidelity, analytics maturity, and commercial terms.
- Unit-economics models: modular TCO templates that let users compare CapEx vs. OpEx options, insourcing vs. managed services, and sensor-suite trade-offs.
- Regulatory risk matrices: scenario planning for FAA rule changes (e.g., BVLOS approval pathways, DETER enforcement processes) and recommended mitigations by jurisdiction.
- Technology roadmaps: timelines for key capability adoptions—autonomy, AI anomaly detection, multisensor fusion, and satellite-data integration—and how each impacts inspection cadence and accuracy.
- Case studies and contract clauses: anonymized client engagements that surface structure, pricing dynamics, and SLA language that procurement teams can adapt immediately.
We intentionally structured deliverables for 90-day, 12-month, and three-year implementation windows so C-suite owners and program managers can align tactical steps with strategic outcomes.
Strategic implications and recommended actions for 2026
- For asset owners (energy, utilities, infrastructure): Move from single-point pilots to portfolio-level pilots that prioritize asset classes with the fastest payback and regulatory permissibility. Embed analytics SLAs in contracts to ensure actionable outputs, not merely imagery.
- For integrators and vendors: Differentiate through analytics IP and domain expertise. Pursue enterprise partnerships that lock in standardized reality-capture workflows—invest in platform API maturity and BIM/CMMS connectors.
- For investors and private equity: Seek consolidation plays where software and data assets can be stacked on service operations to drive recurring revenue and margin expansion. Fragmentation indicates attractive roll-up opportunities, but due diligence must surface regulatory compliance capabilities.
- For regulators and policy teams: Prioritize flexible proof-of-concept corridors and clearer BVLOS certification paths to maintain safety without stifling commercial adoption. The FAA’s DETER program and proposed BVLOS rules will be critical to monitor and engage with in 2026.
Risks and downside scenarios
No growth thesis is unconditionally secure. Our downside scenarios focus on three categories:
- Regulatory headwinds: Delays or restrictive BVLOS policies would slow the most capital-efficient use cases and keep inspection costs higher for longer.
- Operational and labor constraints: Specialized inspection labor and certified pilots remain a bottleneck; typical drone roof and building inspection pricing ranges in the market reflect this scarcity. Enforcement actions under new regulator programs can temporarily disrupt provider capacity.
- Data governance and cyber risk: As inspection platforms become operationally critical, vendors and buyers must harden data chains and ownership contracts to prevent downstream liability.
How to use this report in boardroom decisions
- Use our scenario-based financial models to stress-test CAPEX approvals and OPEX conversions scheduled in 2026 budgets.
- Adopt the vendor-selection scorecard for RFPs issued in 2026 to accelerate procurement cycles and reduce sourcing risk.
- Leverage our regulatory matrix to sequence pilots where approvals are most likely in 2026, de-risking capital commitments for scale-up phases.
Conclusion — the strategic window for 2026
2026 represents a decisive year: technology capability and regulatory evolution will either synchronize to unlock widespread BVLOS and automated inspections or produce a more gradual migration where fleet economics take longer to materialize. PW Consulting’s Aerial Inspections Service Market research synthesizes the quantitative trajectory—from USD 14.5 billion in 2025 to a projected USD 35.2 billion by 2032 at a 13.5% CAGR—with the qualitative playbooks organizations need to convert market potential into operational value.
For executives planning capital deployment, vendor selection, or M&A activity in 2026, the report functions as both a strategic compass and a tactical toolkit. For full subsegment tables, regional scenarios, vendor scorecards, and downloadable financial models that underpin our recommendations, please visit the full report landing page to access the complete dataset and supplementary materials.
For detailed analysis of this topic, please visit the official page: Aerial Inspections Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Audit Management Software Systems Market Poised for 11.2% CAGR Through 2032
By pmarketresearch, 2026-07-07
Audit Management Software Systems Market 2026: Strategic Imperatives for Decision-Makers — PW Consulting Insight Brief
As organizations confront accelerating regulatory complexity, mounting auditor shortages, and the rapid maturation of AI-enabled governance tools, the Audit Management Software Systems market is entering a phase of structurally higher demand and strategic re‑positioning. PW Consulting’s latest market study, with a 2025 base year and a forecast horizon to 2032, synthesizes five years of historical performance (2020–2025) with scenario-driven forecasting through 2032. The market expanded to roughly USD 2.8 billion in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 11.2%—crossing the USD 3.1 billion threshold in 2026—underscoring the accelerating shift from manual, point-solution approaches to integrated, risk‑centric audit platforms.
Audit Management Software Systems Market
Why this report matters for 2026 decisions
-
Actionable timing: With enforcement milestones (notably the EU AI Act coming into full force in mid-2026) and a wave of vendor product launches and partnerships already reshaping capabilities, 2026 is a pivotal year for procurement cycles, architecture decisions, and compliance roadmaps. The report translates regulatory timelines into procurement and implementation windows—helping buyers avoid costly rework and choose solutions that are enforceable‑ready.
Audit Management Software Systems Market -
Economics and priority-setting: Rising labor costs and shortages in audit talent make automation and evidence orchestration business imperatives. Our analysis quantifies productivity inflection points where automation materially reduces audit cycle time and total cost of ownership—critical input for finance, IT and internal audit leaders preparing 2026 budgets.
Audit Management Software Systems Market -
Vendor and platform strategy: The market is moderately concentrated (top-three and top-five firm concentration metrics demonstrate meaningful but not prohibitive concentration), creating both incumbent advantages and attack vectors for innovative challengers. The report provides layered vendor assessment to inform shortlists and negotiation strategies.
-
Risk‑informed investment: For investors and private equity teams, our forecast scenarios identify segments with accelerated monetization potential linked to SaaS subscription expansion, embedded AI feature monetization, and cross-sell into adjacent GRC modules.
What the PW Consulting report contains — practical, executable content
-
Proprietary market model and forecast engine: A transparent, traceable model spanning 2020–2032 with sensitivity scenarios (base, upside, downside) tied to regulatory shock events, macroeconomic variance, and AI adoption curves.
-
Buyer playbooks: Step‑by‑step templates for RFP design, vendor scorecards, TCO calculators (license, implementation, change management, and ongoing maintenance), and a migration decision tree for legacy on‑premise versus cloud adoption.
-
Implementation blueprints: Minimum viable architecture for integrating audit platforms with ERP, data warehouses and identity systems; phased rollouts designed to deliver measurable audit KPIs in 90‑ and 180‑day milestones.
-
Benchmarked KPIs: Practical metrics and dashboards for measuring audit program maturity, automation uplift, evidence traceability, and compliance remediation velocity.
-
Vendor evaluation matrix: Multi‑dimensional scoring covering product functionality, AI governance readiness, data residency and privacy posture, ecosystem integrations, professional services maturity, and pricing transparency.
-
Case studies and savings models: Real-world adoption scenarios that illustrate ROI pathways for finance-led, risk-led, and compliance-led procurement initiatives.
Competitive landscape: positioning and strategic moves
The competitive map shows established GRC and enterprise software vendors advancing along different vectors—platform breadth, domain specialization, AI‑infused productivity, and ecosystem partnerships. Key strategic observations:
-
Specialist innovators (e.g., modern audit-native platforms) are doubling down on connected risk workflows and AI-driven evidence orchestration. These vendors excel at purpose-built audit processes and fast time‑to‑value for internal audit teams.
-
Integrated GRC incumbents and enterprise suites are leveraging cross‑module synergies—bundling governance, risk, compliance, and audit capabilities into unified platforms. Such breadth supports enterprise consolidation strategies but may require careful evaluation of depth in audit-specific workflows.
-
Pure-play enterprise software providers are focusing on integration within broader financial and ERP ecosystems, offering seamless data flows and strong controls for organizations with large SAP/ERP footprints.
Representative vendor profiles analyzed in the report include market leaders and rapidly growing challengers. PW Consulting examines their strategic positioning—product strengths, roadmap momentum, go‑to‑market motion, AI readiness, and professional services capability—providing decision‑grade intelligence for 2026 shortlists.
Recent ecosystem developments and implications
-
Partnership acceleration: Strategic alliances and partnerships announced late‑2025 and early‑2026 are expanding capabilities around automated data ingestion and audit evidence readiness. Buyers should treat partner depth (integration maturity, shared SLAs) as a procurement gating factor.
-
Vendor product launches: Several vendors rolled out embedded AI suites and data privacy modules in 2025–2026. These features reduce manual triage work, but buyers must validate AI governance controls, explainability, and human-in-the-loop safeguards—especially with imminent AI regulation.
-
Regulatory inflection points: The full enforcement of the EU AI Act in August 2026 and expanding U.S. state privacy laws increase compliance complexity. Platforms that can demonstrate rigorous model documentation, data lineage, and auditable decision trails will be preferred in regulated industries.
-
Market concentration dynamics: Measured concentration indicates leading vendors hold meaningful share without forming a dominant oligopoly—an environment that encourages both consolidation and continued innovation. Procurement teams can extract value through competitive sourcing while planning for multi‑vendor coexistence.
Technology and regulatory dynamics to watch in 2026
-
AI governance will be a procurement filter. Beyond flashy copilots, auditors and compliance officers will prioritize platforms with policy engines, bias mitigation, model monitoring, and documented human oversight workflows.
-
Data privacy and residency constraints will drive architectural choices. Expect hybrid deployment patterns—some workloads remaining on-premise or in constrained cloud enclaves to satisfy local privacy regimes.
-
Interoperability over monoliths: Organizations increasingly favor platforms that provide robust APIs and packaged connectors to ERPs, contract systems, and evidence repositories, enabling composable audit ecosystems.
-
Automation maturity differentiators: Vendors that convert raw data into audit‑ready evidence (structured mapping, linkage to controls, time‑stamped trails) will win engagement and justify premium pricing.
Recommended strategic moves for 2026
-
For enterprise buyers: Run a two‑track procurement—(1) a short‑term tactical procurement to automate immediate high‑volume audit tasks, and (2) a medium‑term architectural program to consolidate audit, risk and compliance data flows across the enterprise. Insist on proof‑of‑concepts that demonstrate measurable cycle time and remediation velocity improvements.
-
For mid-market and SME buyers: Prioritize platforms that offer pre‑built connectors and packaged workflows to minimize implementation lift. Consider SaaS subscriptions with staged rollouts to control cash flow and deliver early wins.
-
For vendors: Differentiate through verifiable AI governance, domain templates, and close partnerships with ERP and data providers. Invest in verticalized content (industry control frameworks, regulatory mappings) to accelerate buyer time‑to‑value.
-
For investors: Look for companies with high gross retention and strong professional services margins, especially those that can demonstrate composable architectures and platform‑driven monetization beyond seat licenses.
How PW Consulting’s analysis reduces execution risk
Our report minimizes implementation risk by combining quantitative forecasting with practical execution artifacts. The market model quantifies demand trajectories and identifies sensitivity to regulatory and macro drivers; the implementation playbooks reduce time‑to‑value; the vendor scorecards cut vendor selection cycles by providing reproducible evaluation criteria. Collectively, these deliverables turn market insight into executable decisions that align procurement cadence with compliance deadlines and ROI thresholds.
Where this leaves decision‑makers
2026 will separate organizations that treat audit modernization as a tactical cost play from those that view it as a strategic capability—integral to risk management, control assurance, and sustainable compliance. With the market already exhibiting mid‑double‑digit growth and vendors accelerating AI and privacy capabilities, the window to secure advantageous pricing, integration priority, and transformation momentum is narrow but actionable.
PW Consulting’s Audit Management Software Systems Market report equips boards, CFOs, CIOs, CAEs, procurement teams, and investors with the context, tools, and vendor intelligence required to make confident 2026 decisions. To preserve the utility of this briefing as a strategic “trailer,” detailed regional and segment-level breakdowns, full vendor scorecards, and granular financial matrices have been reserved for the full report.
Next steps
-
Download the full dossier and supporting spreadsheets for procurement-ready artifacts, scenario models, and vendor profiles (available via PW Consulting’s report portal).
-
Schedule a briefing with our advisory team for a tailored session: alignment to your audit maturity, mapping of integration points, and a 90-day pilot plan.
Contact PW Consulting to convert the market momentum into a defensible, measurable audit modernization program in 2026.
For detailed analysis of this topic, please visit the official page: Audit Management Software Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Wafer-Level Burn‑In System Market to Expand at a 13.55% CAGR (2026–2032), Surpassing USD 3,456 Million by 2032
By pmarketresearch, 2026-07-07
Wafer Level Burn-In System Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting’s latest market research on Wafer Level Burn-In (WLTBI) systems, with a 2025 base year and a forecast running through 2032, surfaces actionable insights that will shape capital allocation, supplier strategy, and product roadmaps in 2026. The market is demonstrating sustained, above-market growth: from under USD 800 Million in 2020 to roughly USD 1.42 Billion in 2025, and a projected expansion to approximately USD 3.46 Billion by 2032—equating to a compound annual growth rate of 13.55% across the forecast window. For executives weighing factory investments, alliances, or vertical integration in the semiconductor test ecosystem, the findings in this report convert macro momentum into operational priorities.
Wafer Level Burn In System Market
Why this report matters to decision-makers in 2026
-
Timing of capital deployment — The WLTBI market’s growth trajectory signals both opportunity and a narrow window for advantage. Our base-year analysis (2025) captures the inflection where demand for multi-wafer, high-power and automation-enabled WLBI configurations becomes mainstream. Boards and investors need clear guidance on whether to accelerate capacity buildouts in 2026 or adopt a staged approach that protects margins while preserving optionality.
Wafer Level Burn In System Market -
Technology selection and product design — As device complexity escalates (wide-bandgap power, silicon photonics, advanced memory and AI SoC test needs), the choice of burn-in architecture—full-wafer parallel systems vs. selective approaches, high-temperature capabilities, contactor technology, and automation protocols—will determine yield uplift and total cost of test. Our report provides the performance trade-offs and scenario-based ROI models executives require to set 24–36 month product and equipment roadmaps.
Wafer Level Burn In System Market -
Supply-chain and service economics — Consumables and contactor lifetime economics, equipment lead times, and aftermarket service models are increasingly decisive for factory throughput. The report translates market growth into practical run-rate models, showing how consumable replacement frequency, service contracts, and automation sophistication interact to drive tested-die cost per unit.
What’s in the report: practical, operational content
-
Executive playbook for 2026: A prioritized checklist for CEOs, plant directors, and procurement leads covering CapEx phasing, pilot-to-scale timelines, and vendor selection criteria tied to reliability, automation compatibility, and lifecycle cost.
-
Scenario-based TCO and ROI models: Built for capital planners, these models span conservative to aggressive demand captures, quantify time-to-payback under different automation levels, and include sensitivity analyses for lead-time shocks and consumable price stress.
-
Operations readiness and factory integration blueprints: Practical guidance on integration with SECS/GEM factory automation, thermal management best practices for multi-wafer parallelism, and maintenance/service planning to optimize uptime during scale-up.
-
Vendor scorecards and procurement negotiation frameworks: A repeatable assessment template mapping suppliers across capability, roadmap alignment, spare parts availability, and aftermarket economics—designed to accelerate vendor qualification without overexposure to a single supplier.
-
Risk-mitigation playbook: Actionable strategies to manage export-control impact, supplier concentration, and common bottlenecks including component and consumable shortages—complete with contingency timelines for alternate sourcing and inventory buffering.
Competitive landscape: who matters and why
The WLTBI vendor ecosystem is a mix of specialized equipment companies and major test-equipment incumbents. Our report profiles the full competitive set and synthesizes strategic positioning, technology differentiators, and go-to-market approaches. Key players include:
-
Aehr Test Systems — Recognized for scalable wafer-level platforms and specialized contactor technology, with recent customer wins that underline traction in high-power silicon photonics and AI-related optical I/O applications. Aehr’s multi-wafer parallel systems and focus on automation make it a pivotal vendor for hyperscale-oriented customers seeking throughput and repeatability.
-
Semight Instruments — A regionally strong supplier with offerings targeting wide-bandgap devices and high-temperature reliability testing, emphasizing multi-wafer capacity and automated flow for volume operations.
-
4JMSolutions — Focused on optoelectronic and power-device burn-in with systems designed for VCSEL, Micro LED, and SiC applications; their multi-wafer handling and thermal capabilities align with manufacturers pushing new form factors.
-
Delta V Instruments, Pentamaster, Advantest, Teradyne, Abrel Products, Robson Technologies, and Electron Test Equipment — Each brings complementary strengths: patented wafer-level approaches, integrated automation, global service footprints, configurable burn-in boards, and high-precision single/multi-wafer solutions. Incumbents with broad test portfolios can bundle wafer-level offerings with package-level and system-level solutions, while specialists compete on thermal density, contactor longevity, and automation fit.
Strategic takeaway: buyers must weigh the benefits of specialized WLBI suppliers (deep expertise, focused roadmaps) against larger vendors (integration breadth, global service). Our vendor matrices in the full report translate those trade-offs into procurement scorecards tailored to customer profiles—hyperscalers, IDMs, OSATs, and foundries.
Recent market signals and what they mean
-
Large-scale customer orders and follow-on purchases from leading device manufacturers are validating WLBI as a production-stage reliability step rather than a niche validation tool—particularly where multi-wafer, high-power burn-in directly mitigates field failures in power and optical interconnect applications.
-
Shipment patterns show simultaneous momentum at wafer and package levels, underscoring a broader shift toward integrated reliability strategies across test stages.
-
Requests for higher automation standards (SECS/GEM compatibility and 300mm workflows) are increasing, signaling that factory integration and data-driven process control are priorities for the next generation of WLBI deployments.
Market dynamics, constraints, and strategic risks
-
Policy and trade controls — Ongoing export-control regimes continue to create uncertainty for cross-border equipment flows and component procurement. Strategic sourcing and compliance frameworks are now critical parts of any acquisition plan.
-
Tariff and logistics pressures — Tariff actions and rising logistical complexity are driving companies to diversify suppliers and regionalize inventories. Expect elongated lead times for some equipment families unless mitigated through early ordering and dual-sourcing strategies.
-
Consumable economics — Full-wafer contactors and high-power interface components have high recurring replacement rates relative to test equipment lifecycles. These consumable dynamics materially affect per-die test economics and should be central to procurement total-cost analyses.
-
Component and subassembly shortages — Recent operational disruptions have shown how sensitive WLBI programs are to a narrow set of components. Manufacturing leaders need proven contingency plans and validated alternate suppliers to avoid throughput shortfalls.
Actionable recommendations for 2026
-
Adopt a staged capital deployment with optionality: Prioritize pilot lines that validate multi-wafer burn-in efficacy for critical device families before committing to full-line conversions.
-
Score vendors on lifecycle economics, not just equipment price: Include consumable replacement cadence, spare parts logistics, and service-level agreements in vendor selection matrices.
-
Invest in SECS/GEM and factory-data integration early: Automation readiness will determine how effectively WLBI can scale without producing bottlenecks in thermal management and wafer handling.
-
Formalize compliance and dual-sourcing strategies: Build procurement playbooks that incorporate export-control adherence, alternate supply routes, and regional inventory buffers to protect ramp timelines.
-
Negotiate for bundled lifecycle services: Look for suppliers willing to offer extended maintenance, consumable supply agreements, and in-line diagnostics to reduce total cost of ownership and improve uptime predictability.
Next steps — where to get the full intelligence
This preview highlights the strategic contours that will shape WLTBI decisions in 2026, but it intentionally omits granular subsegment and regional share tables to preserve the value of the full study. PW Consulting’s complete report contains the detailed breakouts, vendor scorecards, downloadable financial models, and playbooks necessary to operationalize these recommendations. For procurement teams, product leaders, and C-suite executives preparing capital and manufacturing plans next year, the full dataset and executable templates are available on the PW Consulting report page.
Contact PW Consulting to schedule a briefing or to obtain the full Wafer Level Burn-In System Market report and the accompanying decision-support toolkit for 2026 planning.
For detailed analysis of this topic, please visit the official page: Wafer Level Burn In System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 7.5% CAGR for 25G Optical Chip Market — Rising from USD 1,750 Million in 2025 to USD 2,903.34 Million by 2032
By pmarketresearch, 2026-07-06
25G Optical Chip Market — Strategic Insights for 2026 Decision-Makers
PW Consulting’s latest 25G Optical Chip Market briefing frames the commercial and technological inflection points that will shape procurement, R&D, and M&A choices in 2026. Built on a rigorous base year of 2025 with historical analysis across 2020–2025 and forward-looking scenarios to 2032, this release is a strategic preview designed to demonstrate the report’s analytical depth while reserving detailed segment-level data for subscribers. Below we summarize the macro trajectory, practical contents, competitive dynamics, and the immediate actions executives should prioritize as they plan for the year ahead.
25G Optical Chip Market
Key market trajectory: scale, momentum, and concentration
The 25G optical chip market has moved from early recovery into broad industrial adoption. Measured in USD (revenues reported in USD million), the market expanded from USD 1,225 million in 2020 to USD 1,750 million by 2025, reflecting material technology adoption across cloud fabrics, telco upgrades, and high-speed enterprise networking. Our base-case forecast projects a compound annual growth rate (CAGR) of 7.5% for 2026–2032, taking the market to roughly USD 2,903 million by 2032 under current assumptions.
25G Optical Chip Market
Market structure is neither fully fragmented nor highly consolidated: the top three suppliers account for a meaningful minority share of global revenues, while the top five collectively control slightly more than half the market. That middle-ground concentration creates windows for both scale players to exercise supplier power and for nimbler regional vendors to defend niches. Supply-side realities — including near-full utilization at leading EML and CW laser fabs and multi-year backlogs reported at top suppliers — will shape pricing, lead times, and contract structuring in 2026.
25G Optical Chip Market
What the full report delivers: practical, decision-focused modules
- Executive snapshot and investment thesis — concise implications for OEMs, hyperscalers, tier-1 carriers, and private equity investors.
- Market sizing & methodology — transparent models using historical 2020–2025 data, base year 2025, and scenario-driven forecasts for 2026–2032 (revenues in USD million).
- Demand-driver decomposition — end-market demand vectors (data center interconnects, telecom fronthaul/backhaul, and industrial/consumer endpoints), adoption curves, and technology substitution pathways.
- Technology deep dives — comparative evaluation of DFB lasers, EMLs, VCSELs and photodetectors across performance, cost-to-deploy, thermal behavior, and qualification timelines (practical guidance, no vendor spin).
- Supply-side & capacity analysis — wafer, die, packaging and test bottlenecks; foundry vs captive production economics; and material constraints that matter in 2026 procurement cycles.
- Competitive landscape & vendor scorecards — strategic profiles, routing of technology stacks, customer footprints, and partnership/opportunity maps for leading suppliers.
- Risk & compliance matrix — geopolitics, export-control sensitivities, standardization/interop risks (including OIF activities), and mitigation levers for procurement and compliance teams.
- Scenario playbooks & financial models — stress-tested forecasts, sensitivity analyses, and decision thresholds for capex, M&A, and strategic partnerships.
The report is intentionally operational: each module concludes with “so what / now what” checklists and a one-page action matrix customized for different buyer archetypes.
Competitive landscape: who shapes outcomes in 25G
The competitive set is a mix of semiconductor specialists, component incumbents, and vertically integrated transceiver houses. The following companies represent the strategic range of capabilities and commercial postures that buyers and investors must benchmark against.
- MACOM (Lowell, Massachusetts): A portfolio player with a strong technical orientation in DFB laser diodes engineered for direct modulation in uncooled operation up to 25 Gb/s. Their product focus aligns with 5G fronthaul and data center connectivity where low-power, direct-modulation solutions are prioritized. For buyers, MACOM represents a high-performance, component-level partner well-suited to optical sub-assemblies and custom designs.
- Lumentum Operations LLC (San Jose): A leader in high-performance InP EMLs and DFB-based lasers, with internal wafer foundry capabilities. Lumentum’s vertically integrated model supports shorter design-to-production paths for high-reliability telecom and hyperscale applications, making them a natural counterparty for customers prioritizing performance and supplier continuity.
- Broadcom Inc. (San Jose): Strong in VCSEL and laser technologies embedded within broader networking ecosystems. Broadcom’s strategic advantage is ecosystem integration—where transceiver ASICs, optics, and firmware are co-designed—resulting in velocity-to-market for hyperscalers and OEMs focused on total-link optimization.
- Coherent Corp. (formerly II-VI / Finisar) (Saxonburg): A broad supplier of 25G-capable optical components and transceivers. Coherent’s strength is in breadth, with product lines spanning transceiver assemblies and optical chips, which supports diversified buyer needs and long-term service agreements.
- Accelink & InnoLight (China-based): Domestic champions with strong manufacturing scale and growing R&D investments. They play a defensive and offensive role: supplying regional OEMs, participating in cost-competitive tenders, and scaling production for global customers seeking alternative sourcing routes.
- NEC Corporation (Tokyo): Noteworthy for recent product introductions in 2025 extending reach and power efficiency profiles (including 80 km BiDi and tunable extended-reach SFP variants). NEC exemplifies how system vendors continue to translate chip-level innovation into transceiver-level differentiation.
- GLSUN (Guilin): A specialist supplier of 25G DFB diode chips focused on transceiver and PON/5G markets. Small- to mid-cap suppliers like GLSUN often provide cost-competitive chips and can serve as strategic second sources for high-volume buyers.
Recent industry signals are instructive: NEC’s product launches in 2025 underscored the priority on extended reach and bi-directional upgrade paths from 10G, while exhibition showcases from MACOM at OFC 2025 reinforced ongoing innovation at the component level. Behind the product noise, supply-chain intelligence indicates leading suppliers are operating at near-full utilization with multi-year order backlogs — a dynamic that will materially affect lead times and contract terms in 2026.
Industry dynamics shaping strategic choices
- Supply bottlenecks: Critical items — including laser epitaxy capacity, precision packaging, and certain substrate materials — remain bottlenecks. Buyers should assume tighter lead times for EMLs and CW lasers unless pre-contracted capacity is secured.
- Standards and interoperability: The OIF’s interoperability testing and white papers are reducing technical risk but accelerating qualification expectations; interoperability compliance will be table stakes in procurement negotiations.
- Geopolitical risk: Export controls and regional policy shifts add cost and redistribution risks to supply chains, especially where advanced packaging and optical assembly are concentrated in specific geographies.
Strategic implications for 2026 — what decision-makers should prioritize
For C-suite and executive teams, the 2026 imperative is to convert macro visibility into executable procurement, R&D, and M&A decisions. Key implications:
- Hedge capacity through contracts: Long-term supply agreements and capacity reservations (or equity-linked off-take arrangements) will be necessary to mitigate multi-year lead times reported across the sector.
- Diversify supplier mix while maintaining qualification rigor: Dual-sourcing and systematic qualification of regional suppliers reduce single-source risk without compromising interoperability requirements driven by standards bodies.
- Re-evaluate vertical integration economics: For large hyperscalers and tier-1 carriers, in-sourcing wafer-level production or packaging capabilities may yield strategic control over supply and cost over a multi-year horizon.
- Prioritize standards-compliant design: Embracing OIF-driven interoperability metrics will reduce time-to-adoption and avoid costly requalification cycles with end customers.
- Stress-test M&A and partnership targets: Given mid-level concentration (the top five providers control just over half the market), acquisition strategies should target capability gaps (packaging, test, foundry access) rather than scale alone.
Operational playbook — six immediate actions
- Run a 12–36 month supplier stress test to identify single points of failure across wafer, die, and packaging layers.
- Initiate long-term capacity negotiations with leading suppliers and include price-adaptive clauses tied to material costs and geopolitical indices.
- Accelerate in-house qualification programs mapped to OIF interoperability guidelines and reduce qualification lead times by parallelizing lab and field tests.
- Secure critical substrate and specialty optical components through early purchases or strategic inventory hubs to mitigate upstream shortages.
- Establish a targeted scouting process for regional manufacturers offering cost-competitive chips as contingency second sources.
- Calibrate R&D roadmaps toward thermal-efficient, lower-power modulation solutions and packaging innovations that reduce total system cost-of-ownership.
How to access the full intelligence
This briefing is a strategic preview: it communicates the macro sizing (reported in USD million), market trajectory (CAGR 7.5% across 2026–2032), competitive dynamics, and high-conviction plays for 2026. Detailed, granular intelligence — including regional and application-level splits, vendor-specific revenue estimates, downloadable financial models, and full vendor scorecards — is reserved for subscribers to the full PW Consulting 25G Optical Chip Market Report.
For procurement directors, product strategy leads, and investors who require the complete dataset and executable templates, the full report includes downloadable models, scenario toggles, and tailored recommendations for buyer archetypes. Visit our report page to access sample extracts and subscription options, or contact our insights team to schedule a strategy briefing.
PW Consulting’s analysis is built for leaders who need to convert market clarity into executable advantage. As the 25G cycle shifts from adoption to optimization, the right combination of supply-side discipline, standards alignment, and targeted investment will define winners in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: 25G Optical Chip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Metaverse in Manufacturing Market Set to Surge at 28.5% CAGR Through 2032
By pmarketresearch, 2026-07-06
Metaverse in Manufacturing Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
Executive summary
PW Consulting’s new Metaverse in Manufacturing Market report (base year 2025, forecast period 2026–2032) quantifies a fast-maturing industry that is shifting from experimentation to production-scale deployment. Our top‑line modelling places the global market at approximately USD 12,500 Million in 2025 and growing at a compound annual growth rate (CAGR) of 28.5% through 2032, reaching an estimated USD 72,315.58 Million by 2032. This trajectory reflects accelerating adoption of digital twins, immersive training, collaborative engineering environments, and GPU‑driven simulation across discrete and process manufacturing.
Metaverse In Manufacturing Market
This release follows a “trailer” principle: we surface the strategic conclusions and practical implications that matter to 2026 decision-makers while intentionally withholding the granular segment-by-segment tables and select proprietary indices available in the full report. Use the insights below to validate executive priorities and to shape investment conversations — and visit the full report page to access the detailed tables, regional and application splits, vendor scorecards and financial models that informed our guidance.
Metaverse In Manufacturing Market
What the full report delivers (practical capabilities)
- Robust market sizing and forecasting methodology (historical 2020–2025, base 2025, forecast 2026–2032), including sensitivity scenarios tied to compute availability and standards adoption.
- Actionable use‑case playbooks: step‑by‑step templates for Digital Twin Simulation, Virtual Training & Operations, Collaborative Product Development, and Remote Maintenance — each with KPI frameworks and cost/benefit mapping.
- Vendor assessment framework and procurement checklist: independent scoring across technical interoperability, cloud/edge readiness, ecosystem partnerships, and enterprise supportability.
- Implementation roadmaps for pilots to scale (0→1→N), with milestone templates, organizational change guidance, and vendor contracting considerations tailored to CAPEX vs OPEX models.
- Financial impact models and executive dashboards: multi-year ROI templates that link metaverse initiatives to productivity, lead-time reduction, quality improvement, and maintenance cost avoidance.
- Case studies and validated reference deployments from industry leaders and early-adopter manufacturers, with concrete lessons for transfer to mid‑market firms.
Macro dynamics shaping 2026 decisions
Three structural forces are converging to make 2026 a pivotal year for industrial metaverse investments:
Metaverse In Manufacturing Market
- Hardware and simulation capability: real‑time physics and photorealistic rendering — enabled by high‑performance GPUs and platforms such as NVIDIA Omniverse — have removed a key technical barrier to realistic digital twins at factory scale. This compute layer shifts projects from proof‑of‑concepts to mission‑critical workflows.
- Standards and regulatory clarity: convergence around standards (including workstreams under ISO and IEC, and IEEE initiatives) is improving interoperability and procurement confidence for IT/OT leaders. Compliance with emerging guidance for multimedia and twin definitions materially de‑risks integrations.
- Ecosystem consolidation: a mix of large industrial software providers, real‑time 3D engine vendors, and systems integrators is forming multi‑party stacks. Strategic partnerships — rather than single‑vendor dominance — are the dominant route to scale in 2026.
Taken together, these dynamics justify accelerated pilot funding for manufacturing firms that want to secure first‑mover advantages in productivity and sustainability metrics. The market’s high CAGR both signals upside for strategic investors and underscores the need for disciplined vendor and standards governance to avoid rework and stranded assets.
Competitive landscape — who matters in 2026
The industrial metaverse value chain is populated by a small set of platform leaders and a broad field of specialist integrators. Market concentration metrics indicate a moderately concentrated environment, with a handful of major players accounting for a meaningful share of market revenues while a vigorous long tail pursues niche solutions.
- Siemens AG (Munich, Germany) — Strengths: deep PLM and shop‑floor integration via Xcelerator, coupled with a deliberate pathway to Omniverse‑enabled Digital Twin Composer. Strategic posture in 2026: industrial‑grade, enterprise‑scale deployments tied to factory planning and adaptive manufacturing. Implication: Siemens is the partner of choice where tight PLM‑to‑production integration matters most.
- NVIDIA Corporation (Santa Clara, USA) — Strengths: Omniverse as the computational substrate for photoreal, multi‑user digital twins and real‑time physics. Recent 2026 partnership activity demonstrates NVIDIA’s role as an enabler rather than a direct systems integrator. Implication: manufacturers should treat NVIDIA as a foundational infrastructure partner and build vendor neutrality into procurement specs.
- Dassault Systèmes (France) — Strengths: 3DEXPERIENCE’s virtual twin and immersive collaboration capabilities for complex engineering lifecycles. Implication: strong fit where design‑centric digital continuity is required across global engineering teams.
- PTC Inc. (USA) — Strengths: Vuforia and digital thread assets for AR/MR and field operations. Implication: highly relevant for companies prioritizing frontline worker augmentation and rapid serviceability improvements.
- Microsoft Corporation (USA) — Strengths: Mesh and HoloLens for collaborative mixed reality experiences, with deep cloud and enterprise platform integrations. Implication: attractive where integration with enterprise identity, security, and Azure cloud services is a procurement priority.
- Unity Technologies (USA) — Strengths: Unity Industry for real‑time 3D and simulation fidelity optimized for manufacturing scenarios. Implication: preferred when bespoke interactive experiences and simulation extensibility are required.
- ABB Ltd (Switzerland) — Strengths: robotics and automation expertise blended with digital twin capabilities for operations and predictive maintenance. Implication: a natural ally for robotics‑centric factories seeking closed‑loop digital/physical workflows.
Recent industry moves reinforce ecosystem dynamics: NVIDIA’s March 2026 partnership wave with Siemens, Dassault and PTC accelerates platform integration; Siemens’ announced Digital Twin Composer readies enterprise marketplaces for mid‑2026 shipments; and industry forums such as ARENA2036 are translating laboratory learning into reproducible factory transfers. These developments mean that by the second half of 2026, procurement windows for platform and compute commitments will become firmer.
Practical strategic guidance for 2026 decision-makers
Based on cross‑industry interviews, financial modelling and technical assessments in our report, PW Consulting recommends the following priorities for 2026:
- Prioritize value-driven pilots — Select 2–3 use cases from operations, training, or product engineering that promise measurable outcomes within 9–15 months. Use pilots to validate data flows, latency constraints, and interoperability with PLM/ERP systems.
- Design for interoperability — Specify standards compliance and open data contracts up front. Require vendors to demonstrate alignment with emerging ISO/IEC/IEEE metaverse standards in RFPs to reduce lock‑in risk.
- Secure compute capacity strategically — GPUs and edge‑to‑cloud orchestration are gating factors. Structure procurement to allow phased capacity expansion and explore shared compute consortium models if capital is constrained.
- Adopt a platform + integrator model — Separate platform licensing (simulation/engine/infrastructure) from systems integration and domain consulting. This reduces vendor coupling and preserves flexibility for future innovation.
- Embed governance and cyber risk controls — Treat metaverse environments as extensions of OT estates. Define identity, asset ownership, and incident response playbooks before scaling to production.
- Invest in workforce transition — Combine technical upskilling for systems engineers with change programs for production supervisors and frontline maintenance teams to accelerate adoption and capture benefits.
Implementation playbook — from pilot to scale
Our stepwise blueprint for 2026 starts with “minimum viable digital twin” pilots and progresses to enterprise rollouts. Key checkpoints:
- Define business KPIs and acceptance tests (throughput, mean time to repair, training transfer metrics).
- Map data sources and latency budgets; pilot with a single production line or asset family.
- Choose a reference platform (engine + physics layer + interoperability stack) and negotiate clear IP and data rights.
- Execute a 3‑phase scaling plan: stabilize → standardize → industrialize; each phase links to budget gates and architecture reviews.
- Measure and communicate benefits centrally to maintain executive sponsorship and to fund scale‑up investments.
Why 2026 is a decision inflection point
The combination of rapid market growth, maturing platform partnerships, and clearer standards makes 2026 a year when strategic commitments will produce wide separations in operational performance. The market’s projected trajectory — a near‑quadrupling from 2025 to the 2032 horizon in our central scenario — favors organizations that align technology choices with business outcomes and that secure platform interoperability early.
Next steps — where to find the full analysis
This preview highlights the strategic framing and operational playbooks contained in PW Consulting’s full Metaverse in Manufacturing Market report. If you are preparing capital and strategic plans for 2026, the full report provides the withheld granular analytics: regional and application splits, vendor scorecards, CR‑based concentration analyses, and the financial models required for board‑level approvals.
Contact PW Consulting or visit our report page to download the complete dataset and to schedule a bespoke briefing with our lead analysts. For executive teams, we offer tailored workshops that map the report’s findings directly onto your factory footprints, supplier relationships, and transformation roadmaps.
— PW Consulting, Advanced Industries Practice & Chief Industry Analyst
For detailed analysis of this topic, please visit the official page: Metaverse In Manufacturing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com