

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: All-Solid-State Battery Market to Reach USD 23.08B by 2032 at 13.2% CAGR

All‑Solid‑State Battery Market: Strategic Outlook for 2026 Decision‑Makers
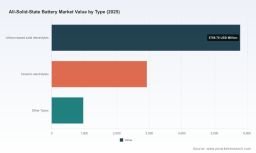
PW Consulting presents a focused strategic preview of the All‑Solid‑State Battery (ASSB) market intended to inform corporate, investor, and policy decisions through 2026 and beyond. Built on a base year of 2025, our market model — expressed in USD (Million) — captures a historical trajectory (2020–2025) and projects forward across a 2026–2032 forecast horizon at a compound annual growth rate of 13.2%. Under this central scenario the market expands materially over the forecast window, underscoring meaningful commercial opportunity as well as complex execution risk for stakeholders pursuing industrialization, OEM integration, and aftermarket safety compliance.
All-Solid-State Battery Market
Why this research matters in 2026
2026 is the inflection point at which laboratory advances and pilot demonstrations are converging with first‑wave industrial deployments. For executives making near‑term capital allocation, partnership, and product‑roadmap choices, a disciplined view of scale‑up timelines, supplier concentration risk, and regulatory trajectories is essential. Our study translates technical milestones and pilot‑line activity into commercial timelines and decision triggers so that management teams can prioritize investments, secure supply, and design entry or defense strategies that align with real manufacturing readiness.
All-Solid-State Battery Market
Core dynamics shaping the 2026 landscape
- Technology pathways and tradeoffs: Multiple chemistries (lithium‑metal anodes with thin solid electrolytes, sulfide electrolytes, oxide ceramics, and composite approaches) are now in pilot or early pre‑production. Each path has different performance, safety, manufacturability and IP characteristics; choosing a partner or in‑house route has long‑term strategic consequences.
- Manufacturing transition: Automated pilot lines and roll‑to‑roll processes are moving from demonstrations toward continuous production. Pilot throughput, yield improvement curves, and CAPEX cadence determine the timing of economically viable gigawatt‑scale supply.
- Supply chain bottlenecks: Solid electrolyte demand creates new upstream needs — industry presentations indicate very large tonnage requirements per gigawatt hour of capacity — producing potential sourcing and processing bottlenecks that will constrain early movers if not addressed proactively.
- Standards and safety: Global standards development and national standardization initiatives are accelerating. Advanced safety testing guidelines and harmonized protocols are being developed, but full international consensus remains under workstream activity, raising compliance timing risk for OEMs and tier‑1 suppliers.
- Policy and funding support: Public funding and small‑business innovation awards are directing capital toward manufacturing innovation, accelerating domestic capabilities in key markets, and shaping where early production footprints will be viable.
Strategic implications by value‑chain node
- Raw‑material and electrolyte sourcing: Secure long‑lead suppliers of solid electrolytes and precursor materials through multi‑year contracts, co‑investment, or equity stakes. Sourcing is a strategic bottleneck that can constrain capacity ramp.
- Cell design and intellectual property: Protect and license critical IP while evaluating cross‑licensing to accelerate OEM adoption. Some technology owners are pursuing licensing models tied to automated pilot lines; others are vertically integrating.
- Pilot‑to‑mass transition: Validate manufacturing yield and cycle‑life at pilot scale and build modular CAPEX plans that allow staged expansion tied to yield improvements rather than upfront oversized investments.
- OEM integration and timing: Align vehicle architecture roadmaps with realistic cell delivery windows; avoid aggressive launch dates that ignore validation and regulatory approval timelines.
- Regulatory readiness: Invest in compliance protocols and third‑party validation programs to accelerate certification, particularly where national standards are in the process of being finalized.
Competitive landscape: what to watch in 2026
The market is shaped by a mix of specialized start‑ups, industrial JV players, established battery OEMs and legacy automakers. Below are the strategic postures and near‑term triggers for leading actors that will influence competitive dynamics in 2026 and beyond.
All-Solid-State Battery Market
- QuantumScape Corporation (San Jose, CA) — Strengths: technology focused on lithium‑metal high‑energy anodes and an automated pilot facility designed to support OEM sampling and licensing. Strategic signal: the inauguration of an Eagle Line pilot indicates a licensing and OEM sampling playbook; watch for announcements on sampling schedules and licensing terms that could accelerate third‑party adoption.
- Ampcera Inc. (San Jose, CA) — Strengths: materials specialization in high‑performance sulfide electrolytes with scaling production. Strategic signal: suppliers of engineered electrolyte powders can become chokepoints; partnering or offtake agreements with cell makers will be pivotal.
- Argylium (France) — Strengths: a European JV combining industrial and research capabilities to commercialize sulfide electrolytes. Strategic signal: regional industrial alliances and state support can create locally advantaged supply clusters.
- Solid Power Inc. (Louisville, CO) — Strengths: demonstrated manufacture of multi‑Ah cells on continuous roll‑to‑roll lines and OEM relationships. Strategic signal: track cell qualification timelines with automotive partners and volume commitments from OEMs.
- Greater Bay Technology (China) — Strengths: recently rolled out A‑sample cells with robust energy density claims and safety testing milestones. Strategic signal: rapid domestic validation and local vehicle installation targets indicate China will be an early high‑volume market.
- ProLogium Technology (Taiwan) — Strengths: oxide ceramic‑based approach and gigafactory partnerships with OEMs. Strategic signal: roll‑to‑roll manufacturing partnerships with large automakers can shorten commercialization cycles for selected architectures.
- Ilika plc (UK) — Strengths: focused pilot production for electric mobility; small‑scale, high‑value applications can provide early cash flows and validation opportunities.
- Samsung SDI (Korea) — Strengths: established battery manufacturing capability and a stated target to move to mass production in the coming cycle. Strategic signal: incumbent cell producers with existing OEM relationships can leverage scale and system integration expertise to accelerate adoption.
- Toyota Motor Corporation (Japan) — Strengths: deep vehicle integration capability, regulatory approvals, and partnerships for sulfide electrolyte supply. Strategic signal: OEMs that own or control key elements of the stack can shape standards, safety protocols, and supplier ecosystems.
Report content — practical deliverables
Our full ASSB market study is built for commercial use and includes the following operational modules (excerpt):
- Integrated market model (2020–2032) with scenario‑sensitive forecasts and sensitivity levers for yield, cost, and adoption timing.
- Technology readiness roadmap and comparative TRL/CRL (technology and commercialization readiness level) analysis across electrolyte and anode chemistries.
- Supply‑chain maps and risk heatmaps highlighting material intensity, processing choke points and contingency sourcing strategies.
- Manufacturing playbooks covering pilot line KPIs, ramp‑ratio scenarios, CAPEX build profiles and yield‑improvement benchmarks.
- Company dossiers with strategic SWOTs, partnership architectures, and likely go‑to‑market pathways for the major technology owners and incumbents.
- Regulatory and standards tracker with compliance checklists, certification timelines and key policy decision points by jurisdiction.
- M&A and alliance target lists with commercial match‑making matrices and negotiation clout estimators.
Note: the report contains granular regional and application splits, proprietary price and volume curves, and downloadable model files. These detailed subsegment outputs are maintained behind our client portal to preserve competitive value and are intentionally summarized here to direct stakeholders to the full deliverable.
Actionable recommendations for 2026 decisions
- Near term (0–12 months): Conduct material supply audits, secure strategic offtake contracts, initiate pilot validations with at least two cell technology partners, and join standards working groups to influence test protocols.
- Medium term (12–36 months): Structure modular CAPEX plans, negotiate licensing terms that preserve optionality, and develop cross‑border logistics playbooks for critical electrolyte supply.
- Longer term (36+ months): Decide on vertical integration versus partner‑based models based on pilot yields and regulatory alignment; prepare for second‑wave scaling contingent on yield and cost breakpoints.
How PW Consulting can help
We support manufacturers, OEMs, investors and governments with tailored advisory across commercial due diligence, site selection, joint‑venture structuring, and regulatory strategy. Our engagements combine the forecast models and risk frameworks from this report with hands‑on negotiation support and technical validation protocols to accelerate safe, commercially viable launches.
To access the full market model, subsegment breakdowns, proprietary supplier scoring and executable playbooks — including downloadable financial templates and scenario models — visit our report page or contact PW Consulting for a briefing. The granular insights required to convert pilot progress into profitable industrial capacity are in the full report; this preview outlines the strategic levers and decision points that will define success in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: All-Solid-State Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com