

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
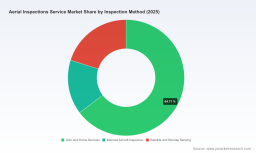
PW Consulting: Aerial Inspections Market to Expand at 13.5% CAGR, Rising from USD 14,500M in 2025 to USD 35,183.5M by 2032 — UAV & Drone Services Lead with USD 9,383.6M

Aerial Inspections Service Market: Strategic Outlook for 2026 Decisions
PW Consulting’s latest market research—built on a 2025 base year and a 2026–2032 forecast horizon—provides decision-grade intelligence for executives who must act in 2026. The Global Aerial Inspections Service Market has more than doubled in five years, rising from approximately USD 7.45 billion in 2020 to USD 14.5 billion in 2025, and is projected to continue at a robust compound annual growth rate (CAGR) of 13.5% through 2032, reaching roughly USD 35.2 billion by the end of the forecast period. This growth trajectory is reshaping capital allocation, procurement strategies, and technology roadmaps across energy, utilities, infrastructure, and industrial verticals.
Aerial Inspections Service Market
Why this report matters for 2026
- Actionable timing: 2026 is the inflection year for several regulatory and operational changes—FAA initiatives on BVLOS, new enforcement pathways, and accelerated platform capability releases—that will materially affect implementation feasibility and unit economics.
- Investment prioritization: With a predictable macro growth rate, boards and strategy teams must distinguish between platform play, service scale, and analytics-first propositions; the report provides prioritization frameworks tuned for 2026 budgeting cycles.
- Procurement clarity: Buyers face a fragmented supplier landscape. Our work decodes vendor capabilities into procurement-ready criteria so buyers can reduce time-to-deployment while managing risk.
Market trajectory and macro drivers
The market’s acceleration is driven by a confluence of forces: sensor miniaturization and multispectral maturity, cloud-native data management, AI analytics for anomaly detection, and cost-justifying returns on safety and operational uptime. The report quantifies the historical run-rate (2020–2025) and projects forward under multiple regulatory and technology adoption scenarios for 2026–2032. At the aggregate level, stakeholders should plan against a central case CAGR of 13.5% while stress-testing portfolios against faster automated BVLOS adoption and slower regulatory approvals.
Aerial Inspections Service Market
Operational economics continue to favor aerial approaches: industry benchmarking indicates drone-based industrial inspections can reduce operating costs by 30–70% and compress inspection time by 75–85% relative to traditional rope-access or scaffold-based methods. Those savings, combined with improved inspection cadence and data repeatability, are the primary levers feeding ROI models in our financial templates.
Aerial Inspections Service Market
Competitive landscape — what to watch in 2026
The market remains lightly concentrated (CR3 ≈ 22.5%, CR5 ≈ 31.4%), indicating a vibrant ecosystem where differentiated capability—software platforms, specialized vertical expertise, and integrated data services—matters more than scale alone. Key provider archetypes and representative players covered in the report include:
- Platform-centric leaders: Companies offering end-to-end data platforms and analytics (e.g., DroneDeploy) are pushing enterprise standardization through software features, strategic partnerships, and faster capture-to-insight times.
- Vertical specialists: Firms focused on wind, solar, or LNG (e.g., SkySpecs for wind blade autonomy; Raptor Maps for solar analytics; Cyberhawk for energy-sector operations) continue to capture premium pricing through domain-specific IP and regulatory know-how.
- Global operators: Providers with geographically distributed service delivery and local regulatory footprints (e.g., Terra Drone) are converting multinational maintenance contracts into multi-year recurring revenue.
- Integrated service firms: Surveying and LiDAR specialists (e.g., SAM) and enterprise drone integrators (e.g., Measure) are combining hardware, geospatial engineering, and data pipelines to serve infrastructure and utilities customers.
Recent visible moves emphasize the market’s dual track: platform enhancement and enterprise partnerships. Notable developments tracked in the report include a multi-year expansion of DroneDeploy’s enterprise footprint with large construction clients and sequential software releases that significantly improve capture performance and BIM integration; Cyberhawk’s contract extensions in energy markets; and new offshore-focused divisions launched to address subsea and maritime inspection needs. These transactions and product cycles signal that 2026 procurement conversations will center not only on flight capability but on enterprise-scale data flows and long-term SLAs.
What the report contains — practical, implementable content
Beyond headline sizing and competitive maps, the report is organized to be operational from day one. Highlights include:
- Deployment playbooks: step-by-step templates for internal pilots, scale-up, and integration with existing maintenance management systems (CMMS/EAM).
- Procurement and vendor-selection frameworks: weighted criteria matrices covering safety compliance, data fidelity, analytics maturity, and commercial terms.
- Unit-economics models: modular TCO templates that let users compare CapEx vs. OpEx options, insourcing vs. managed services, and sensor-suite trade-offs.
- Regulatory risk matrices: scenario planning for FAA rule changes (e.g., BVLOS approval pathways, DETER enforcement processes) and recommended mitigations by jurisdiction.
- Technology roadmaps: timelines for key capability adoptions—autonomy, AI anomaly detection, multisensor fusion, and satellite-data integration—and how each impacts inspection cadence and accuracy.
- Case studies and contract clauses: anonymized client engagements that surface structure, pricing dynamics, and SLA language that procurement teams can adapt immediately.
We intentionally structured deliverables for 90-day, 12-month, and three-year implementation windows so C-suite owners and program managers can align tactical steps with strategic outcomes.
Strategic implications and recommended actions for 2026
- For asset owners (energy, utilities, infrastructure): Move from single-point pilots to portfolio-level pilots that prioritize asset classes with the fastest payback and regulatory permissibility. Embed analytics SLAs in contracts to ensure actionable outputs, not merely imagery.
- For integrators and vendors: Differentiate through analytics IP and domain expertise. Pursue enterprise partnerships that lock in standardized reality-capture workflows—invest in platform API maturity and BIM/CMMS connectors.
- For investors and private equity: Seek consolidation plays where software and data assets can be stacked on service operations to drive recurring revenue and margin expansion. Fragmentation indicates attractive roll-up opportunities, but due diligence must surface regulatory compliance capabilities.
- For regulators and policy teams: Prioritize flexible proof-of-concept corridors and clearer BVLOS certification paths to maintain safety without stifling commercial adoption. The FAA’s DETER program and proposed BVLOS rules will be critical to monitor and engage with in 2026.
Risks and downside scenarios
No growth thesis is unconditionally secure. Our downside scenarios focus on three categories:
- Regulatory headwinds: Delays or restrictive BVLOS policies would slow the most capital-efficient use cases and keep inspection costs higher for longer.
- Operational and labor constraints: Specialized inspection labor and certified pilots remain a bottleneck; typical drone roof and building inspection pricing ranges in the market reflect this scarcity. Enforcement actions under new regulator programs can temporarily disrupt provider capacity.
- Data governance and cyber risk: As inspection platforms become operationally critical, vendors and buyers must harden data chains and ownership contracts to prevent downstream liability.
How to use this report in boardroom decisions
- Use our scenario-based financial models to stress-test CAPEX approvals and OPEX conversions scheduled in 2026 budgets.
- Adopt the vendor-selection scorecard for RFPs issued in 2026 to accelerate procurement cycles and reduce sourcing risk.
- Leverage our regulatory matrix to sequence pilots where approvals are most likely in 2026, de-risking capital commitments for scale-up phases.
Conclusion — the strategic window for 2026
2026 represents a decisive year: technology capability and regulatory evolution will either synchronize to unlock widespread BVLOS and automated inspections or produce a more gradual migration where fleet economics take longer to materialize. PW Consulting’s Aerial Inspections Service Market research synthesizes the quantitative trajectory—from USD 14.5 billion in 2025 to a projected USD 35.2 billion by 2032 at a 13.5% CAGR—with the qualitative playbooks organizations need to convert market potential into operational value.
For executives planning capital deployment, vendor selection, or M&A activity in 2026, the report functions as both a strategic compass and a tactical toolkit. For full subsegment tables, regional scenarios, vendor scorecards, and downloadable financial models that underpin our recommendations, please visit the full report landing page to access the complete dataset and supplementary materials.
For detailed analysis of this topic, please visit the official page: Aerial Inspections Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com