

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: 25G Optical Chip Market Set to Reach USD 2.9 Billion by 2032, Expanding at a 7.5% CAGR

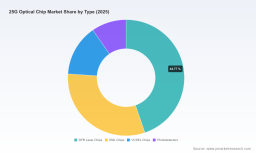
PW Consulting Strategic Brief: 25G Optical Chip Market — What Every Executive Must Know Heading into 2026
As demand for higher bandwidth and lower latency accelerates across cloud, carrier and edge networks, 25G optical chipsets have moved from a tactical upgrade to a strategic infrastructure decision. PW Consulting’s latest market study (base year 2025; historical series 2020–2025; forecast 2026–2032) provides executives with the foresight and practical toolset needed to make high-stakes procurement, investment and partnership decisions in 2026. The global 25G optical chip market, having grown from roughly 1,225 Million USD in 2020 to 1,750 Million USD in 2025, is projected to expand at a compound annual growth rate (CAGR) of 7.5% over the 2026–2032 forecast window, reaching approximately 2,903 Million USD by 2032.
25G Optical Chip Market
Why 25G Is a Strategic Inflection Point in 2026
-
Cost-per-bit economics: As hyperscalers and carriers balance capex and operational power budgets, 25G solutions offer an attractive inflection between legacy 10G links and emerging 50/100G architectures. The near-term optimization of link speeds, power envelope and module complexity is now central to network architecture decisions.
25G Optical Chip Market -
Demand tailwinds from cloud and 5G: Continued densification of data center fabrics and 5G fronthaul/midhaul upgrades underpin steady demand growth, while new enterprise and industrial optical use cases are expanding non-traditional adoption vectors.
25G Optical Chip Market -
Supply-side constraints and bottlenecks: Our sector supply-chain workstream finds leading producers of critical 25G laser technologies (EML/CW) operating near full utilization, with backlogs extending beyond two years at top suppliers. Alongside this, precision optical subcomponents and advanced packaging—areas concentrated in a few geographies—represent persistent bottlenecks that materially influence time-to-market and margin realization.
-
Standards and interoperability: Industry bodies such as the OIF are actively publishing interoperability metrics and test frameworks relevant to 25G and higher interfaces. Companies that align early to these specifications will shorten qualification cycles and reduce field failures.
-
Geopolitical and regulatory risk: Export controls and regional tensions are increasing the cost and complexity of resilient sourcing strategies. For organizations with global footprints, supplier diversification and near-shore contingency plans are no longer optional.
What PW Consulting’s 25G Report Delivers — Practical, Executable Outputs
This is not a high-level narrative. The report was built for decision-makers who must convert insight into action in 2026. Key practical deliverables include:
-
Transparent market-sizing and forecasting methodology — reproducible models that trace demand drivers, adoption timelines and unit economics across the 2026–2032 horizon.
-
A buyer’s playbook — procurement frameworks for tendering, long-term contracting templates, supplier qualification checklists and negotiation levers tailored to optical chip supply dynamics.
-
Supplier benchmarking and risk scoring — a multi-dimensional scorecard covering technology depth, capacity posture, geographic concentration, qualification lead times and commercial flexibility.
-
Technology trade-off matrices — side-by-side evaluation of laser types and photodetector approaches aligned to reach, power, cost and manufacturability trade-offs to support SKU rationalization or new product definition.
-
CapEx and supply-chain scenario tools — sensitivity models that quantify the impact of capacity constraints, material shortages and tariff/embargo scenarios on unit cost, lead time and margin.
-
M&A and partnership screening playbooks — criteria and valuation heuristics for bolt-on acquisitions, joint development agreements and foundry partnerships.
-
Field qualification acceleration templates — test-plan blueprints, interoperability checkpoints, and sample size recommendations to compress qualification cycles without increasing rollout risk.
-
Executive dashboard — a one-page impact summary linking macro forecasts, supplier exposure and recommended 90/180/360-day actions to support board-level decisions in 2026.
Competitive Landscape — Who Matters and Why
The 25G supplier ecosystem combines multi-national incumbents with regional specialists. Market concentration remains meaningful: our CR3 and CR5 metrics indicate a moderately consolidated market (CR3 approximately 38.5%, CR5 approximately 52.2%), which has direct implications for bargaining power, availability and strategic partnership choices.
-
MACOM — Strong in DFB laser diodes optimized for direct modulation and uncooled operation; well-positioned for 5G fronthaul and certain data-center link designs. Their continued presence at leading industry forums signals an emphasis on product-portfolio depth and channel engagement.
-
Lumentum — A leader in InP EMLs and wafer-foundry capabilities. For buyers requiring high-performance long-reach or temperature-stable modules, Lumentum’s vertically integrated supply model shortens lead times but can command premium commercial terms.
-
Broadcom — Deep integration with data center networking ecosystems and expertise in VCSEL and laser link technologies. Broadcom’s platform position makes it a preferred partner for OEMs seeking tight hardware-software co-optimization.
-
Coherent Corp. (formerly II-VI / Finisar) — Broad portfolio across transceivers and lasers, substantial manufacturing footprint and a track record of rapid scale-up for telecom and datacom segments. Their channel reach supports rapid qualification for large customers.
-
Accelink, InnoLight, GLSUN — Regional champions with strong manufacturability and competitive cost positions for mainstream 25G modules. For firms seeking supply affordability and scale in Asia, these players are critical but require careful qualification and IP diligence.
-
NEC Corporation — Notable for recent product launches in 2025 that extend reach and bidirectional transmission capabilities, demonstrating an emphasis on enabling low-power upgrades from legacy systems. NEC’s portfolio can be attractive for operators managing phased migration strategies.
Recent Market Signals that Change the Playbook
-
Product launches in 2025 from established players (including extended-reach and BiDi transceivers) show a push to capture migration spend from 10G to 25G while minimizing infrastructure changes.
-
Supply-chain reports in 2026 flag near-full utilization for certain laser technologies and multi-year backlogs at leading fabs — a clear signal that procurement cycles and multi-source strategies must be planned well in advance.
-
Standardization work from industry forums is reducing interoperability risk, enabling faster time-to-deployment for vendors that conform early to published test matrices.
-
Geopolitical pressure on advanced packaging and certain substrate materials is prompting buyers to quantify nationality-of-origin risk and to consider near-shoreized capabilities as part of resilience planning.
Scenario Planning: What to Watch in 2026
Our report presents three pragmatic scenarios with trigger-based actions:
-
Baseline (CAGR 7.5%): Steady adoption driven by cloud and 5G, with supply-side frictions managed via longer lead times and prioritized allocation. Recommended action: secure rolling 12–24 month supply agreements with pricing floors tied to clear volume bands.
-
Accelerated adoption: If AI-driven interconnect density or a faster-than-expected 5G upgrade cycle materializes, demand could outstrip forecasted capacity in 2026–2027. Recommended action: fast-track strategic investments in capacity co-funding or exclusive short-term supply arrangements.
-
Constrained supply / geopolitical disruption: Material export controls or a packaging shortage could create sharp localized shortages and price volatility. Recommended action: activate dual-sourcing playbooks, release buffer inventory thresholds and reassign critical traffic to alternative top-of-rack architectures temporarily.
Immediate 90-Day Actions for 2026
-
Run supplier exposure mapping against the report’s supplier scorecards to identify single-source risks and prioritize dual-qualification of at least two alternative vendors for every critical optical chip family.
-
Initiate joint forecasting cadences with strategic suppliers to secure allocation and to reduce market-driven lead-time variability.
-
Embed interoperability test requirements into procurement contracts, referencing OIF-aligned test metrics to accelerate rollouts and reduce integration cost overruns.
-
Model short-term capex for modular assembly or localized packaging to hedge against near-term supply-chain disruptions where unit economics justify the investment.
Conclusion — The Strategic Value of PW Consulting’s 25G Study
Entering 2026, the 25G optical chip market presents a composite opportunity: strong and steady market growth (7.5% CAGR to 2032) alongside real operational risks rooted in supply concentration, component bottlenecks and evolving standards. PW Consulting’s 25G report translates these macro dynamics into executable commercial playbooks, supplier-risk tools and scenario models. It is designed for procurement chiefs, product leaders, CTOs and corporate strategists who must convert market forecasts into defensible, time-sensitive decisions.
To access the full dataset, proprietary supplier scorecards, interactive scenario models and the actionable templates referenced in this brief, please visit the PW Consulting report page or reach out to our industry team for a tailored executive briefing.
For detailed analysis of this topic, please visit the official page: 25G Optical Chip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com