

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Wafer-Level Burn‑In System Market to Expand at a 13.55% CAGR (2026–2032), Surpassing USD 3,456 Million by 2032

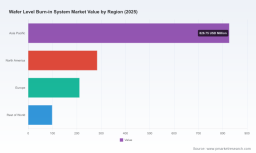
Wafer Level Burn-In System Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting’s latest market research on Wafer Level Burn-In (WLTBI) systems, with a 2025 base year and a forecast running through 2032, surfaces actionable insights that will shape capital allocation, supplier strategy, and product roadmaps in 2026. The market is demonstrating sustained, above-market growth: from under USD 800 Million in 2020 to roughly USD 1.42 Billion in 2025, and a projected expansion to approximately USD 3.46 Billion by 2032—equating to a compound annual growth rate of 13.55% across the forecast window. For executives weighing factory investments, alliances, or vertical integration in the semiconductor test ecosystem, the findings in this report convert macro momentum into operational priorities.
Wafer Level Burn In System Market
Why this report matters to decision-makers in 2026
-
Timing of capital deployment — The WLTBI market’s growth trajectory signals both opportunity and a narrow window for advantage. Our base-year analysis (2025) captures the inflection where demand for multi-wafer, high-power and automation-enabled WLBI configurations becomes mainstream. Boards and investors need clear guidance on whether to accelerate capacity buildouts in 2026 or adopt a staged approach that protects margins while preserving optionality.
Wafer Level Burn In System Market -
Technology selection and product design — As device complexity escalates (wide-bandgap power, silicon photonics, advanced memory and AI SoC test needs), the choice of burn-in architecture—full-wafer parallel systems vs. selective approaches, high-temperature capabilities, contactor technology, and automation protocols—will determine yield uplift and total cost of test. Our report provides the performance trade-offs and scenario-based ROI models executives require to set 24–36 month product and equipment roadmaps.
Wafer Level Burn In System Market -
Supply-chain and service economics — Consumables and contactor lifetime economics, equipment lead times, and aftermarket service models are increasingly decisive for factory throughput. The report translates market growth into practical run-rate models, showing how consumable replacement frequency, service contracts, and automation sophistication interact to drive tested-die cost per unit.
What’s in the report: practical, operational content
-
Executive playbook for 2026: A prioritized checklist for CEOs, plant directors, and procurement leads covering CapEx phasing, pilot-to-scale timelines, and vendor selection criteria tied to reliability, automation compatibility, and lifecycle cost.
-
Scenario-based TCO and ROI models: Built for capital planners, these models span conservative to aggressive demand captures, quantify time-to-payback under different automation levels, and include sensitivity analyses for lead-time shocks and consumable price stress.
-
Operations readiness and factory integration blueprints: Practical guidance on integration with SECS/GEM factory automation, thermal management best practices for multi-wafer parallelism, and maintenance/service planning to optimize uptime during scale-up.
-
Vendor scorecards and procurement negotiation frameworks: A repeatable assessment template mapping suppliers across capability, roadmap alignment, spare parts availability, and aftermarket economics—designed to accelerate vendor qualification without overexposure to a single supplier.
-
Risk-mitigation playbook: Actionable strategies to manage export-control impact, supplier concentration, and common bottlenecks including component and consumable shortages—complete with contingency timelines for alternate sourcing and inventory buffering.
Competitive landscape: who matters and why
The WLTBI vendor ecosystem is a mix of specialized equipment companies and major test-equipment incumbents. Our report profiles the full competitive set and synthesizes strategic positioning, technology differentiators, and go-to-market approaches. Key players include:
-
Aehr Test Systems — Recognized for scalable wafer-level platforms and specialized contactor technology, with recent customer wins that underline traction in high-power silicon photonics and AI-related optical I/O applications. Aehr’s multi-wafer parallel systems and focus on automation make it a pivotal vendor for hyperscale-oriented customers seeking throughput and repeatability.
-
Semight Instruments — A regionally strong supplier with offerings targeting wide-bandgap devices and high-temperature reliability testing, emphasizing multi-wafer capacity and automated flow for volume operations.
-
4JMSolutions — Focused on optoelectronic and power-device burn-in with systems designed for VCSEL, Micro LED, and SiC applications; their multi-wafer handling and thermal capabilities align with manufacturers pushing new form factors.
-
Delta V Instruments, Pentamaster, Advantest, Teradyne, Abrel Products, Robson Technologies, and Electron Test Equipment — Each brings complementary strengths: patented wafer-level approaches, integrated automation, global service footprints, configurable burn-in boards, and high-precision single/multi-wafer solutions. Incumbents with broad test portfolios can bundle wafer-level offerings with package-level and system-level solutions, while specialists compete on thermal density, contactor longevity, and automation fit.
Strategic takeaway: buyers must weigh the benefits of specialized WLBI suppliers (deep expertise, focused roadmaps) against larger vendors (integration breadth, global service). Our vendor matrices in the full report translate those trade-offs into procurement scorecards tailored to customer profiles—hyperscalers, IDMs, OSATs, and foundries.
Recent market signals and what they mean
-
Large-scale customer orders and follow-on purchases from leading device manufacturers are validating WLBI as a production-stage reliability step rather than a niche validation tool—particularly where multi-wafer, high-power burn-in directly mitigates field failures in power and optical interconnect applications.
-
Shipment patterns show simultaneous momentum at wafer and package levels, underscoring a broader shift toward integrated reliability strategies across test stages.
-
Requests for higher automation standards (SECS/GEM compatibility and 300mm workflows) are increasing, signaling that factory integration and data-driven process control are priorities for the next generation of WLBI deployments.
Market dynamics, constraints, and strategic risks
-
Policy and trade controls — Ongoing export-control regimes continue to create uncertainty for cross-border equipment flows and component procurement. Strategic sourcing and compliance frameworks are now critical parts of any acquisition plan.
-
Tariff and logistics pressures — Tariff actions and rising logistical complexity are driving companies to diversify suppliers and regionalize inventories. Expect elongated lead times for some equipment families unless mitigated through early ordering and dual-sourcing strategies.
-
Consumable economics — Full-wafer contactors and high-power interface components have high recurring replacement rates relative to test equipment lifecycles. These consumable dynamics materially affect per-die test economics and should be central to procurement total-cost analyses.
-
Component and subassembly shortages — Recent operational disruptions have shown how sensitive WLBI programs are to a narrow set of components. Manufacturing leaders need proven contingency plans and validated alternate suppliers to avoid throughput shortfalls.
Actionable recommendations for 2026
-
Adopt a staged capital deployment with optionality: Prioritize pilot lines that validate multi-wafer burn-in efficacy for critical device families before committing to full-line conversions.
-
Score vendors on lifecycle economics, not just equipment price: Include consumable replacement cadence, spare parts logistics, and service-level agreements in vendor selection matrices.
-
Invest in SECS/GEM and factory-data integration early: Automation readiness will determine how effectively WLBI can scale without producing bottlenecks in thermal management and wafer handling.
-
Formalize compliance and dual-sourcing strategies: Build procurement playbooks that incorporate export-control adherence, alternate supply routes, and regional inventory buffers to protect ramp timelines.
-
Negotiate for bundled lifecycle services: Look for suppliers willing to offer extended maintenance, consumable supply agreements, and in-line diagnostics to reduce total cost of ownership and improve uptime predictability.
Next steps — where to get the full intelligence
This preview highlights the strategic contours that will shape WLTBI decisions in 2026, but it intentionally omits granular subsegment and regional share tables to preserve the value of the full study. PW Consulting’s complete report contains the detailed breakouts, vendor scorecards, downloadable financial models, and playbooks necessary to operationalize these recommendations. For procurement teams, product leaders, and C-suite executives preparing capital and manufacturing plans next year, the full dataset and executable templates are available on the PW Consulting report page.
Contact PW Consulting to schedule a briefing or to obtain the full Wafer Level Burn-In System Market report and the accompanying decision-support toolkit for 2026 planning.
For detailed analysis of this topic, please visit the official page: Wafer Level Burn In System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com