

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: OBD Telematics to Hit USD 1,190M by 2032 at 11.4% CAGR

OBD Telematics Market 2026: Strategic Imperatives for Decision-Makers
As PW Consulting’s Senior Strategy Consultant and Chief Industry Analyst, I present a concise yet rigorous framing of the OBD telematics market and the decisions it forces on corporate leaders in 2026. This article previews the actionable intelligence and scenario-grade foresight you will find in our full market study. We surface the levers that matter for strategy, highlight the competitive movements reshaping the landscape, and signal the regulatory and technical traps that separate winners from stragglers — while deliberately reserving the granular segment-level tables that are available in the full report.
OBD Telematics Market
Market trajectory: why this is a critical moment
Between 2020 and 2025 the OBD telematics market expanded substantially, and our model — anchored to a 2025 base year — projects sustained, double-digit growth through the coming decade. Concretely, the market rose from a mid-three-hundred million USD base in 2020 to roughly USD 580.0 Million by 2025; under the central-case scenario the market is forecast to reach about USD 1,190.0 Million by 2032, representing an approximate compound annual growth rate (CAGR) of 11.4% across the forecast window.
OBD Telematics Market
Those headline dynamics make clear two strategic implications for 2026: (1) this is no longer a niche retrofit play — it is a scale market where platform economics, data strategies, and regulatory compliance will materially determine margin capture; and (2) timing matters: near-term investments in integration and product modularity will compound into substantial strategic advantage as adoption accelerates.
OBD Telematics Market
What the full report delivers — practical, board-level tools
- Proven market sizing and forecasting model (base year 2025) with scenario toggles (conservative / central / accelerated) so executives can stress-test investment cases under alternate macro and regulatory assumptions.
- Decision-oriented playbooks: M&A screening criteria, partnership frameworks, and go-to-market sequencing for carriers, OEMs, fleet operators, insurers, and aftermarket vendors.
- Competitive scorecards and supplier maturity maps that rank product, platform, data, and service capabilities across the vendor set — enabling prioritized vendor shortlists for pilots and procurements.
- Technology architecture blueprints (hardware + edge compute + cloud + APIs), TCO templates, and integration checklists for OEM-connected and retrofit strategies.
- Regulatory compliance matrix and risk heatmap including emission diagnostics standards, regional tamper/anti-tampering policies, and practical actions for legal mitigation.
- Commercial models for subscription pricing, hardware-as-a-service, and data monetization scenarios, including sensitivity analysis for churn, ARPU, and device lifecycle costs.
The above are built to be operational: CFOs get ROI calculators; CTOs get integration milestones and bill-of-materials inputs; business development leaders get partner scorecards and negotiation levers.
Competitive landscape — categories, capabilities, and recent shifts
The market sits at the intersection of device OEMs, telematics platform providers, fleet management specialists, and systems integrators. Market concentration metrics indicate a market that is neither a monopoly nor highly fragmented — the top three players capture a meaningful share of revenue, and the top five together control a clear majority. That concentration creates an environment where scale-driven platform advantages and established channel relationships materially affect entrant economics.
- Device-first leaders (e.g., Geotab, CalAmp, Xirgo): These firms anchor their value with robust, field-proven OBD-II hardware and iterative firmware improvements. Recent product updates show a push to higher compute at the edge (faster processors, more memory, IMU/gyro sensors) to support richer telemetry and local pre-processing. Expect device vendors to emphasize plug-and-play reliability, rapid OTA capability, and expanded sensor fusion as differentiators.
- Platform and software integrators (e.g., Samsara, Verizon Connect, Mojio, Danlaw): Platform providers compete on analytics depth, ease of integrations, and verticalized workflows (fleet ops, insurance telematics, maintenance scheduling). Their winning plays emphasize API ecosystems and purpose-built apps, plus bundling of AI-enabled driver safety features with diagnostics and maintenance workflows.
- Tier-1 automotive suppliers (e.g., Continental, Robert Bosch): These incumbents bridge OEM-grade engineering with telematics services for commercial vehicle OEMs and large fleets. Their strength lies in deep vehicle systems integration, regulatory know-how, and scale manufacturing — making them natural partners for OEM-first strategies and for fleets requiring high-assurance solutions.
- Specialists and IP licensors (e.g., OBD Experts): Companies that own protocol stacks, software toolkits, and diagnostic IP are increasingly valuable as telematics systems decouple into hardware, software stacks, and cloud platforms. Licensing and co-development are growing engagement pathways.
Notable near-term events illustrate shifting competitive dynamics: a major device vendor announced next‑generation hardware with increased processing and sensing capability, and that same vendor has deepened OEM integrations allowing mixed-fleet analytics without wholesale hardware retrofits. Separately, OEMs have begun offering cloud-based diagnostic access to third parties—an inflection that alters the retrofit economics for some use cases. These trends increase the value of flexible integration strategies that can span both OBD plug-in and OEM-native data channels.
Market dynamics and regulatory friction points
- Standards and harmonization: ISO-level diagnostic frameworks are progressing, creating clearer expectations for interoperability of diagnostic services across platforms. Companies that design to harmonized standards reduce integration friction and accelerate fleet rollouts.
- Compliance and anti-tampering: Jurisdictional rules around aftermarket installations and port relocation are evolving. Some regulatory pathways explicitly exempt certain aftermarket solutions when compliance is demonstrable, meaning a regulatory-savvy compliance program is a market enabler rather than a cost center.
- OEM data access: Direct cloud access to vehicle diagnostic data by OEMs changes the retrofit calculus. In some fleets, OEM-provided telematics will obviate the need for plug‑in devices; in others, retrofits remain the fastest path to uniform data across mixed fleets. A hybrid strategy is therefore a practical necessity for many enterprise buyers.
- Legal and policy volatility: Shifts in how key communications services are regulated can affect connectivity economics and service provider contracts. Firms must build contractual flexibility and alternative connectivity plans into multi‑year procurement agreements.
- Cybersecurity and privacy: As device compute and data aggregation increase, so does the attack surface. Security-by-design, certificate management, and privacy-preserving analytic patterns are now procurement table stakes.
Recommended 2026 strategic playbook
For executive teams deciding where to place bets in 2026, we recommend a balanced portfolio approach that combines near-term commercial expansion with mid-term architectural positioning:
- Prioritize integration breadth: Build dual-path data ingestion capabilities — OEM APIs and OBD plug-in — so you can serve both greenfield OEM-aligned clients and retrofit-heavy mixed fleets.
- Invest in modular hardware and edge intelligence: New device generations reward local preprocessing (reducing connectivity costs), richer sensor fusion, and OTA flexibility. Plan hardware roadmaps that decouple compute from radio and sensor modules to shorten update cycles.
- Productize outcomes not just telemetry: Customers buy reduced downtime, lower fuel spend, and lower insurance loss ratios. Translate raw diagnostic streams into verticalized outcomes (predictive maintenance, fuel optimization, safety scoring) with clear KPIs, SLAs, and ROI proofs.
- Make compliance a commercial differentiator: Be prepared to demonstrate standards conformance and anti-tampering mitigation — in some markets this accelerates procurement approval and reduces installation friction.
- Use M&A tactically: Target acquisitions that close gaps in API access, enrich data assets, or embed you into critical fleet workflows. Small bolt-on buys can be more accretive than capex-heavy greenfield buildouts.
- Run staged pilots with measurable gates: Short, KPI-driven pilots that move to commercial rollouts on clear success criteria keep deployments low-risk and fundable.
- Lock in long-term partnerships with connectivity and cloud providers: Negotiate flexible connectivity packages and cloud compute commitments that tolerate volatility in data volumes and regulation.
How to use the full PW Consulting study
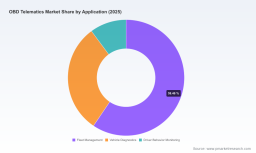
This article previews the strategic framing, competitive nuances, and practical playbooks you need to act in 2026. The full OBD Telematics Market report supplies the missing operational detail — including the granular regional, application, and product splits; interactive forecast models; supplier-by-feature scoring; and downloadable financial templates. Those tables and segment-level breakdowns are intentionally reserved for the full study because they are the inputs CFOs and corporate strategy teams will plug directly into investment memos and board materials.
If your 2026 capital allocation, product roadmap, partnership strategy, or M&A pipeline intersects with connected vehicle data, the full report (with its scenario models, vendor diagnostics, and compliance checklists) will materially shorten your decision cycle and reduce execution risk. In a market growing at an approximate 11.4% CAGR from our 2025 base, the decisions you make this year about integrations, hardware roadmaps, and regulatory positioning will define revenue capture and margin trajectory for the next five years.
PW Consulting — Senior Strategy Consultant & Chief Industry Analyst
For detailed analysis of this topic, please visit the official page: OBD Telematics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com