

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 7.5% CAGR for 25G Optical Chip Market — Rising from USD 1,750 Million in 2025 to USD 2,903.34 Million by 2032

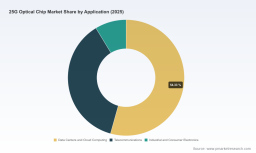
25G Optical Chip Market — Strategic Insights for 2026 Decision-Makers
PW Consulting’s latest 25G Optical Chip Market briefing frames the commercial and technological inflection points that will shape procurement, R&D, and M&A choices in 2026. Built on a rigorous base year of 2025 with historical analysis across 2020–2025 and forward-looking scenarios to 2032, this release is a strategic preview designed to demonstrate the report’s analytical depth while reserving detailed segment-level data for subscribers. Below we summarize the macro trajectory, practical contents, competitive dynamics, and the immediate actions executives should prioritize as they plan for the year ahead.
25G Optical Chip Market
Key market trajectory: scale, momentum, and concentration
The 25G optical chip market has moved from early recovery into broad industrial adoption. Measured in USD (revenues reported in USD million), the market expanded from USD 1,225 million in 2020 to USD 1,750 million by 2025, reflecting material technology adoption across cloud fabrics, telco upgrades, and high-speed enterprise networking. Our base-case forecast projects a compound annual growth rate (CAGR) of 7.5% for 2026–2032, taking the market to roughly USD 2,903 million by 2032 under current assumptions.
25G Optical Chip Market
Market structure is neither fully fragmented nor highly consolidated: the top three suppliers account for a meaningful minority share of global revenues, while the top five collectively control slightly more than half the market. That middle-ground concentration creates windows for both scale players to exercise supplier power and for nimbler regional vendors to defend niches. Supply-side realities — including near-full utilization at leading EML and CW laser fabs and multi-year backlogs reported at top suppliers — will shape pricing, lead times, and contract structuring in 2026.
25G Optical Chip Market
What the full report delivers: practical, decision-focused modules
- Executive snapshot and investment thesis — concise implications for OEMs, hyperscalers, tier-1 carriers, and private equity investors.
- Market sizing & methodology — transparent models using historical 2020–2025 data, base year 2025, and scenario-driven forecasts for 2026–2032 (revenues in USD million).
- Demand-driver decomposition — end-market demand vectors (data center interconnects, telecom fronthaul/backhaul, and industrial/consumer endpoints), adoption curves, and technology substitution pathways.
- Technology deep dives — comparative evaluation of DFB lasers, EMLs, VCSELs and photodetectors across performance, cost-to-deploy, thermal behavior, and qualification timelines (practical guidance, no vendor spin).
- Supply-side & capacity analysis — wafer, die, packaging and test bottlenecks; foundry vs captive production economics; and material constraints that matter in 2026 procurement cycles.
- Competitive landscape & vendor scorecards — strategic profiles, routing of technology stacks, customer footprints, and partnership/opportunity maps for leading suppliers.
- Risk & compliance matrix — geopolitics, export-control sensitivities, standardization/interop risks (including OIF activities), and mitigation levers for procurement and compliance teams.
- Scenario playbooks & financial models — stress-tested forecasts, sensitivity analyses, and decision thresholds for capex, M&A, and strategic partnerships.
The report is intentionally operational: each module concludes with “so what / now what” checklists and a one-page action matrix customized for different buyer archetypes.
Competitive landscape: who shapes outcomes in 25G
The competitive set is a mix of semiconductor specialists, component incumbents, and vertically integrated transceiver houses. The following companies represent the strategic range of capabilities and commercial postures that buyers and investors must benchmark against.
- MACOM (Lowell, Massachusetts): A portfolio player with a strong technical orientation in DFB laser diodes engineered for direct modulation in uncooled operation up to 25 Gb/s. Their product focus aligns with 5G fronthaul and data center connectivity where low-power, direct-modulation solutions are prioritized. For buyers, MACOM represents a high-performance, component-level partner well-suited to optical sub-assemblies and custom designs.
- Lumentum Operations LLC (San Jose): A leader in high-performance InP EMLs and DFB-based lasers, with internal wafer foundry capabilities. Lumentum’s vertically integrated model supports shorter design-to-production paths for high-reliability telecom and hyperscale applications, making them a natural counterparty for customers prioritizing performance and supplier continuity.
- Broadcom Inc. (San Jose): Strong in VCSEL and laser technologies embedded within broader networking ecosystems. Broadcom’s strategic advantage is ecosystem integration—where transceiver ASICs, optics, and firmware are co-designed—resulting in velocity-to-market for hyperscalers and OEMs focused on total-link optimization.
- Coherent Corp. (formerly II-VI / Finisar) (Saxonburg): A broad supplier of 25G-capable optical components and transceivers. Coherent’s strength is in breadth, with product lines spanning transceiver assemblies and optical chips, which supports diversified buyer needs and long-term service agreements.
- Accelink & InnoLight (China-based): Domestic champions with strong manufacturing scale and growing R&D investments. They play a defensive and offensive role: supplying regional OEMs, participating in cost-competitive tenders, and scaling production for global customers seeking alternative sourcing routes.
- NEC Corporation (Tokyo): Noteworthy for recent product introductions in 2025 extending reach and power efficiency profiles (including 80 km BiDi and tunable extended-reach SFP variants). NEC exemplifies how system vendors continue to translate chip-level innovation into transceiver-level differentiation.
- GLSUN (Guilin): A specialist supplier of 25G DFB diode chips focused on transceiver and PON/5G markets. Small- to mid-cap suppliers like GLSUN often provide cost-competitive chips and can serve as strategic second sources for high-volume buyers.
Recent industry signals are instructive: NEC’s product launches in 2025 underscored the priority on extended reach and bi-directional upgrade paths from 10G, while exhibition showcases from MACOM at OFC 2025 reinforced ongoing innovation at the component level. Behind the product noise, supply-chain intelligence indicates leading suppliers are operating at near-full utilization with multi-year order backlogs — a dynamic that will materially affect lead times and contract terms in 2026.
Industry dynamics shaping strategic choices
- Supply bottlenecks: Critical items — including laser epitaxy capacity, precision packaging, and certain substrate materials — remain bottlenecks. Buyers should assume tighter lead times for EMLs and CW lasers unless pre-contracted capacity is secured.
- Standards and interoperability: The OIF’s interoperability testing and white papers are reducing technical risk but accelerating qualification expectations; interoperability compliance will be table stakes in procurement negotiations.
- Geopolitical risk: Export controls and regional policy shifts add cost and redistribution risks to supply chains, especially where advanced packaging and optical assembly are concentrated in specific geographies.
Strategic implications for 2026 — what decision-makers should prioritize
For C-suite and executive teams, the 2026 imperative is to convert macro visibility into executable procurement, R&D, and M&A decisions. Key implications:
- Hedge capacity through contracts: Long-term supply agreements and capacity reservations (or equity-linked off-take arrangements) will be necessary to mitigate multi-year lead times reported across the sector.
- Diversify supplier mix while maintaining qualification rigor: Dual-sourcing and systematic qualification of regional suppliers reduce single-source risk without compromising interoperability requirements driven by standards bodies.
- Re-evaluate vertical integration economics: For large hyperscalers and tier-1 carriers, in-sourcing wafer-level production or packaging capabilities may yield strategic control over supply and cost over a multi-year horizon.
- Prioritize standards-compliant design: Embracing OIF-driven interoperability metrics will reduce time-to-adoption and avoid costly requalification cycles with end customers.
- Stress-test M&A and partnership targets: Given mid-level concentration (the top five providers control just over half the market), acquisition strategies should target capability gaps (packaging, test, foundry access) rather than scale alone.
Operational playbook — six immediate actions
- Run a 12–36 month supplier stress test to identify single points of failure across wafer, die, and packaging layers.
- Initiate long-term capacity negotiations with leading suppliers and include price-adaptive clauses tied to material costs and geopolitical indices.
- Accelerate in-house qualification programs mapped to OIF interoperability guidelines and reduce qualification lead times by parallelizing lab and field tests.
- Secure critical substrate and specialty optical components through early purchases or strategic inventory hubs to mitigate upstream shortages.
- Establish a targeted scouting process for regional manufacturers offering cost-competitive chips as contingency second sources.
- Calibrate R&D roadmaps toward thermal-efficient, lower-power modulation solutions and packaging innovations that reduce total system cost-of-ownership.
How to access the full intelligence
This briefing is a strategic preview: it communicates the macro sizing (reported in USD million), market trajectory (CAGR 7.5% across 2026–2032), competitive dynamics, and high-conviction plays for 2026. Detailed, granular intelligence — including regional and application-level splits, vendor-specific revenue estimates, downloadable financial models, and full vendor scorecards — is reserved for subscribers to the full PW Consulting 25G Optical Chip Market Report.
For procurement directors, product strategy leads, and investors who require the complete dataset and executable templates, the full report includes downloadable models, scenario toggles, and tailored recommendations for buyer archetypes. Visit our report page to access sample extracts and subscription options, or contact our insights team to schedule a strategy briefing.
PW Consulting’s analysis is built for leaders who need to convert market clarity into executable advantage. As the 25G cycle shifts from adoption to optimization, the right combination of supply-side discipline, standards alignment, and targeted investment will define winners in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: 25G Optical Chip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com