

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Optical Films Market to Grow at 7.1% CAGR Through 2032

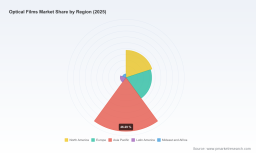
Optical Films Market — Strategic Preview for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, forward-looking briefing on the optical films market that translates technical market intelligence into boardroom-ready actions for 2026. This preview highlights the structural drivers, competitive dynamics, and near-term strategic levers that will determine winners and laggards across display OEMs, advanced materials suppliers, and tiered component manufacturers. It intentionally demonstrates analytical depth while withholding granular segmentation tables and proprietary model outputs — the latter are available in the full report for subscribers.
Optical Films Market
Market trajectory and strategic context
The optical films market has shown resilient expansion through the post-pandemic recovery period and is on a steady growth path into the next decade. Using 2025 as our base year, the market is valued in the mid-hundreds of millions (USD, revenue basis) and is forecast to grow at a compound annual growth rate (CAGR) of 7.1% over the 2026–2032 forecast window. This trajectory reflects a convergence of display innovation (flexible OLEDs, mini-LED and micro-LED backlights, AR/ HUD integration), increased per-unit complexity in consumer devices, and rising content and safety requirements in automotive and industrial displays.
Optical Films Market
Historical performance through 2020–2025 demonstrates both the resilience and volatility of this sector. Supply-side shocks and raw-material swings depressed margins intermittently, while product innovation and recycling mandates have opened higher-margin, differentiated opportunities. For 2026, executives must read this as a market in which steady top-line expansion coexists with heightened operational and regulatory risks — a classic environment where strategy execution and supply-chain choices trump static market-share plays.
Optical Films Market
What is changing now — five dynamics to watch
-
Technology-driven demand composition: Display manufacturers are increasing requirements for thinner, higher-transmittance, and multi-functional films (e.g., polarizers integrated with brightness enhancement or anti-reflection properties). Novel form factors (foldables, rollables) are accelerating adoption of ultra-thin and flexible optical films.
-
Sustainability and regulatory pressure: Recyclable and low-environmental-impact chemistries are rapidly moving from “nice-to-have” to procurement prerequisites for major OEMs. Suppliers that can demonstrate circularity and reduced life-cycle impact will secure preferential sourcing and command premium pricing.
-
Supply-chain localization and capacity shifts: Manufacturers are responding to labor cost volatility, material shortages, and tariff uncertainty by selectively localizing production and reconfiguring inventory strategies. Recent greenfield expansions in Asia and targeted capacity upgrades in Korea and Japan create regional capacity pockets that change lead-time economics.
-
Tariff and trade-policy tail risks: Specialty chemicals used in film production face variable export controls and tariffs. These policies can rapidly reconfigure competitive advantages among global suppliers and alter sourcing decisions for display OEMs.
-
Automotive and AR use-cases scaling: Head-up displays, in-cabin infotainment, and augmented-reality overlays are driving bespoke film requirements (optical clarity, polarization control, durability). Co-development agreements between chemical suppliers and automotive OEMs are emerging as strategic anchors.
Competitive landscape — what the market structure means for 2026 moves
The market is moderately concentrated among several global players, with a handful of firms capturing a material share of advanced optical film demand. That concentration creates both supplier power and opportunity: leading players can invest in specialized R&D, while mid-tier suppliers can carve resilient niches through partnerships and tailored product stacks.
-
3M Company — continues to push ultra-thin polarizers and flexible-film innovation tailored to next-gen OLED form factors. Recent product introductions signal an emphasis on extending portfolio depth for foldable and flexible devices.
-
LG Chem — positions itself on sustainable materials, launching recyclable optical film families that meet increasingly exacting OEM sustainability requirements. This is a defensive and offensive play: defend existing relationships while opening new procurement pathways where ESG is a criterion.
-
Samsung SDI — integrates display-facing film capabilities with panel technologies, leveraging close OEM relationships to co-develop film composites for both LCD and OLED stacks.
-
Zeon, Toray, Nitto, Toyobo — these specialists are focused on high-transmittance substrates, low-haze films, and material science upgrades for touch and polarizer stacks. Their depth in polymer chemistry and substrate processing is a key competitive barrier.
-
Eastman Chemical — recently expanded manufacturing capacity in Asia, which materially alters the cost and lead-time calculus in certain regional supply chains.
Recent industry actions — a new ultra-thin polarizer launch, capacity expansions in Asia, and OEM-supplier partnerships for automotive HUD/AR — underscore a bifurcation: larger suppliers are investing in scale and premium innovation; specialist firms are protecting margin via targeted material differentiation and collaboration with OEMs.
Practical contents — what the full PW Consulting report delivers
The full study offers executive-ready, operational guidance designed for 2026 planning cycles. Highlights include:
-
Robust market-sizing and forecast model (base year 2025; 2026–2032 forecasts) with scenario layers for technology adoption, trade-policy shocks, and raw-material price regimes.
-
Competitive benchmarking with strategic profiles for each major supplier, innovation roadmaps, and capability heatmaps to identify partnership and acquisition targets.
-
Supply-chain resilience playbook: a prioritized set of actions covering capacity localization, dual-sourcing, strategic inventory sizing, and contract structures to mitigate tariff and raw-material volatility.
-
Commercial go-to-market playbooks for suppliers and OEMs: tiered pricing strategies, co-development contracting templates, procurement scorecards, and channel optimization guidance.
-
Capex and ROI toolkits: sensitivity matrices and break-even analyses for greenfield lines, product conversion investments, and recycling-enhancement retrofits.
-
Regulatory and compliance checklist tailored to chemical export controls and environmental mandates, with recommended mitigation steps and timeline impact assessments.
-
Investor and M&A intelligence: target screening criteria, valuation benchmarks, and post-merger integration risks specific to optical-film technology and production footprints.
Strategic recommendations for 2026 corporate planning
For boards and C-level teams, the following strategic priorities should be operationalized in 2026 planning cycles to capture upside and insulate downside risk.
-
Prioritize differentiated product roadmaps: Invest in ultra-thin, multifunctional films and recyclable chemistries. Incremental manufacturing efficiency is necessary but insufficient — differentiation will drive margin expansion.
-
Lock in OEM co-development partnerships: Move from transactional sales to integrated development agreements with major panel and device manufacturers to secure long-term demand visibility and co-fund innovation risk.
-
Reassess manufacturing footprint defensively: Use scenario modeling to determine which assets to localize, expand, or decommission — prioritize proximity to strategic OEMs and access to stable input streams rather than lowest labor cost alone.
-
Hedge raw-material and tariff exposure: Deploy commodity hedging where possible, negotiate long-term supply agreements with pricing collars, and structure sales contracts to share tariff risk with customers in clearly defined triggers.
-
Pursue bolt-on M&A and strategic alliances: Acquire niche material innovators or processing specialists to shorten time-to-market for next-generation films. Target assets that plug directly into existing supply relationships with panel OEMs.
-
Embed sustainability into procurement and product specification: Make recyclability and end-of-life processing part of your product spec for new contracts; this reduces future retrofit costs and strengthens negotiation positions with ESG-focused OEMs.
Decision triggers and KPIs to include in 2026 execution plans
-
Volume and revenue mix against scenario buckets (baseline, upside, downside) for product families tied to flexible OLEDs and automotive AR.
-
Gross margin differential from recycled/eco-friendly product lines versus legacy films; milestone-based R&D expenditure tracking.
-
Weighted lead-time and fill-rate metrics across primary production nodes to trigger capacity shifts or inventory builds.
-
Tariff exposure quantified as a percentage of cost of goods sold, with defined contractual triggers for price pass-through or mitigation actions.
Closing — the strategic value of this research for 2026
For executives planning capital allocation, product strategy, or M&A in 2026, this market represents a growth opportunity tempered by operational and policy risk. The sector’s 7.1% projected CAGR and the mid-hundreds million USD market base (2025) suggest healthy expansion, but realizing attractive returns requires precision in technology roadmaps, supply-chain positioning, and regulatory strategy. PW Consulting’s full Optical Films Market report supplies the models, scenario analyses, and playbooks that translate market forecasts into executable corporate strategy — enabling decision-makers to prioritize investments, secure long-term OEM relationships, and hedge the structural risks that will define 2026 outcomes.
To access the complete dataset, granular regional and application segmentation, and downloadable decision-support models, please consult the full PW Consulting report online. The comprehensive package contains appendices with vendor scorecards, capex calculators, and contract templates not published in this preview.
For detailed analysis of this topic, please visit the official page: Optical Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com