

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Rubidium Atomic Clock Market to Reach USD 845.41M by 2032 (7.02% CAGR)

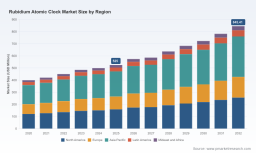
Rubidium Atomic Clock Market — Strategic Preview for 2026 Decision-Making
Atomic timing is no longer a niche engineering discipline; it is a strategic enabler across telecommunications, navigation, defense and space systems, and critical infrastructure. Our Rubidium Atomic Clock Market study synthesizes five years of historical performance and a seven-year forward view to deliver a decision-grade perspective for corporate leaders planning in 2026. This preview highlights the study’s strategic value, the market dynamics shaping near-term choices, and the competitive posture of incumbent and emerging suppliers — while reserving the granular segment datapoints for the full report to preserve its commercial utility.
Rubidium Atomic Clock Market
Why this study matters in 2026
-
Clear, investable growth trajectory — The market has expanded from a firmly established base in 2020 and reached an estimated USD 525.0 Million in 2025. Our baseline forecast anticipates continuation of growth into the next planning cycle, reaching roughly USD 574.56 Million in 2026 and accelerating toward an estimated USD 845.41 Million by 2032 at a compound annual growth rate of 7.02% (USD Million basis). For product planners, M&A teams and procurement leaders, those dynamics change how you prioritize R&D, capital allocation and supplier strategies for 2026.
Rubidium Atomic Clock Market -
Decision-focused deliverables — This study is built to be actionable: it combines bottom-up sizing, technology roadmaps, go-to-market playbooks and supplier risk matrices so that boardrooms and program teams can convert market intelligence into executable plans within weeks rather than months.
Rubidium Atomic Clock Market -
Timing-sensitive regulatory and procurement constraints — The market’s growth is tightly coupled to regulatory shifts and procurement cycles (notably in telecom and defense), which makes early alignment on certification, interoperability and sustainability a competitive advantage in 2026.
What the full report delivers (practical, operational content)
-
Robust market model: historical 2020–2025 reconciliation and scenario-driven forecasts for 2026–2032 (base, upside, downside) with sensitivity to price, volume and substitution effects.
-
Go-to-market playbooks tailored by buyer type (telecom OEMs, satellite prime contractors, defense integrators, research institutions) including recommended commercial terms, bundling strategies and aftermarket support models.
-
Competitive benchmarking and product scorecards: performance, SWaP (size, weight, and power), qualification status, mean time between failures (MTBF) estimates, and typical lifecycle costs — presented in a format you can apply directly to supplier selection and RFPs.
-
Technology and R&D roadmap: miniaturization pathways, cell-based rubidium advances, frequency stability improvement levers, and plausible substitution threats across the forecast horizon.
-
Regulatory and certification tracker: a prioritized playbook of compliance activities required by major regulators and defense certification bodies, including energy efficiency and hazardous-substance constraints that affect manufacturing and sourcing.
-
Supply chain heatmaps and resilience playbook: single-source exposures, critical component lead times, sample dual-sourcing strategies, and practical inventory policies for mitigating geopolitical and component shocks.
-
M&A and partner screening: scored lists of potential acquisition or JV targets, with pro forma valuation ranges, integration risk assessment and potential synergies for product line expansion or geographic access.
-
Operational tools: downloadable models (Excel), executive slide decks and a one-week workshop agenda for rapid alignment with senior stakeholders.
Market dynamics and inflection points to track in 2026
-
Demand drivers are diversifying. High-capacity telecom networks (including backhaul and edge synchronization), expanding satellite constellations, defense modernization and critical infrastructure hardening are creating parallel demand streams. These drivers are changing procurement cadences and introducing new timeliness expectations for product qualification and delivery.
-
Miniaturization and cost-per-performance competition. The product development race is focused on reducing size, power and cost while preserving stability. New miniature models introduced across suppliers are beginning to compress price bands and open adjacent applications, but they also increase pressure on legacy unit economics.
-
Regulatory tightening — case in point: a series of updates to radio-frequency, interoperability and defense certification rules (notably in jurisdictions with advanced telecom and defense ecosystems) raise the bar for timing accuracy, interference mitigation and cybersecurity hardening. Environmental and energy-efficiency constraints are increasingly part of procurement specifications, forcing manufacturers to redesign production and to document lifecycle impacts.
-
Concentration with room for disruption. The vendor landscape is consolidated among a handful of established players with specialized capabilities, yet innovation from smaller, focused entrants is capable of reshaping niches if incumbents fail to scale miniaturized, low-cost solutions quickly.
Competitive landscape — strategic posture of core suppliers
The competitive field is occupied by established aerospace and defense suppliers, frequency-specialist manufacturers, semiconductor and systems companies, and high-performance laboratory vendors. A few high-level strategic takes on representative players:
-
Safran Electronics & Defense — A leading global supplier with a comprehensive product family spanning full-size to miniature rubidium clocks. Safran is executing on a product modernization cadence that emphasizes space and defense qualifications and moves to secure long-term prime-supplier positions in sensitive programs.
-
IQD Frequency Products — A frequency specialist with strong capabilities in crystal and oscillator technologies. IQD’s portfolio and manufacturing experience provide a stable platform for incremental innovation in timing modules that are compatible with telecom and industrial integrators.
-
AccuBeat — A supplier focused on ruggedized and miniature oscillators for military and space applications. AccuBeat’s modular approaches and GPS-integrated systems make it an attractive partner for programs requiring hybrid timing solutions.
-
Excelitas Technologies — Known for space-qualified standards and a strong track record in satellite timing products. Excelitas is positioned to win constellation-level supply contracts where flight heritage and qualification depth matter.
-
Frequency Electronics — Focused on high-precision products for defense and space, with digital rubidium systems that appeal to integrators prioritizing software-driven timing control and remote calibration capabilities.
-
Microchip Technology — A strategic entrant from the semiconductor side, pushing miniaturized embedded atomic oscillators that can be integrated into larger avionics and industrial platforms, raising potential for scale if successful.
-
Chengdu Spaceon Electronics — A major domestic producer with advantages in vertical integration for certain end-markets. Their positioning matters for procurement strategies tied to specific geographies or national programs.
-
Stanford Research Systems — Serves laboratory and precision instrument niches with reliable bench-top rubidium standards; important for test, calibration and research workflows rather than mass-deployed systems.
Recent product launches underscore the pace of innovation: several firms released second-generation miniature rubidium clocks and low-cost commercial models in 2025, accelerating the migration of atomic timing into new device classes. These product moves validate the trend toward smaller, lower-power solutions while simultaneously compressing time-to-qualification for network and defense integrators.
Strategic recommendations for executives planning in 2026
-
Prioritize miniaturized, low-power product roadmaps if you compete in telecom, avionics or LEO satellite markets — these segments are most sensitive to SWaP improvements and cost-per-channel economics.
-
Operationalize supplier diversification: define second-source contracts for critical subassemblies and negotiate joint inventory buffers with strategic suppliers to protect against lead-time shocks.
-
Embed regulatory readiness into product development: design to meet evolving frequency-interoperability, cybersecurity and environmental standards from day one to avoid costly retrofits.
-
Invest in aftermarket services and lifecycle monetization: extended warranties, calibration-as-a-service and remote-monitoring can materially improve lifetime margins and customer stickiness.
-
Pursue targeted M&A or partnerships to fill capability gaps quickly — especially where qualification cycles are long and in-house development would delay market entry.
-
Use scenario planning to size contingencies: model the impact of accelerated miniaturization, disruptive cost entrants, and tightening export controls on revenue and margin trajectories through 2032.
How to use this preview and the full study
This preview exists to orient leadership toward the strategic choices that will matter in 2026. The full PW Consulting study contains the granular segmentation, regional analytics, detailed supplier scorecards and executable templates that you will need to implement the recommendations above. If your objective is to (a) align R&D budgets to market windows, (b) structure procurement contracts that mitigate supplier risk, or (c) identify acquisition targets that accelerate route-to-market, the complete dataset and scenario models in the full report are designed to plug directly into your planning cycles.
For confidentiality and commercial reasons, we have intentionally withheld the granular regional and application splits in this preview — those detailed figures, together with unit-price models and downloadable decision tools, are available in the full report and through our advisory engagements.
Next steps
-
Request a tailored briefing: schedule a one-hour executive session where we will run the model on your specific product, region and procurement constraints and deliver a prioritized action plan for 90–180 days.
-
Engage for a rapid supply-chain stress test: a three-week engagement to map critical exposures, test alternative sourcing strategies and provide a remediation playbook.
-
Download the full study and interactive models to unlock the granular segmentation and supplier benchmarking required for tactical execution in 2026.
Timing devices frame the tempo of complex systems. As enterprises calibrate plans for 2026, access to disciplined market intelligence and an operational playbook will be the difference between being a supplier of choice and simply responding to procurement fires. Our full Rubidium Atomic Clock Market study provides that intelligence and the tools to act — contact PW Consulting to continue the conversation and convert this market momentum into measurable competitive advantage.
For detailed analysis of this topic, please visit the official page: Rubidium Atomic Clock Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com