

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Nursing Bras Market to Reach USD 2,510M by 2032 at 8.1% CAGR

Nursing Bras Market — Strategic Preview for 2026 Decision Makers
PW Consulting’s Nursing Bras Market study is designed as an operational playbook for executives, product leads, and investors preparing decisions across 2026. This briefing distills the study’s strategic value: it reveals why the category is shifting from a niche postpartum accessory into a mainstream, innovation-driven subsegment of intimate apparel—and which levers matter most for near-term commercial success. We surface the structural drivers, competitive moves, and supply-chain constraints that will determine winners, while deliberately reserving the full, granular segmentation and scenario tables for the complete report.
Nursing Bras Market
Market trajectory and why 2026 is pivotal
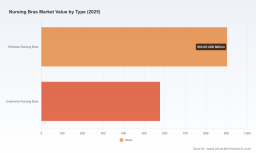
The category moved from a stable niche in the early 2020s to a double-digit growth trajectory by mid-decade. Our base-year analysis (2025) benchmarks the global market at approximately USD 1.48 billion, with a compound annual growth rate of 8.1% across the forecast window (2026–2032). By 2032 the market is projected to exceed USD 2.5 billion under the baseline scenario. That pace is sufficient to change strategic calculus for mainstream apparel brands, private-label retailers, and specialist innovators alike: what was once incremental revenue now represents a platform for adjacent services (pumping solutions, subscription replacement, certified materials) and durable customer relationships across pregnancy and postpartum cohorts.
Nursing Bras Market
Three structural dynamics converge to make 2026 a strategic inflection point:
Nursing Bras Market
- Product innovation (hands‑free pumping, breathable quick‑dry zones, seamless wireless constructions) is moving from premium niche to broad market adoption.
- Regulatory and certification pressures (material safety and Oeko‑TEX® standards) are increasing supplier switching costs and raising barriers for low‑quality entrants—this is shifting the competition from low‑price to product‑quality and compliance differentiation.
- Retail and reimbursement pathways (including selective insurer reimbursement and workplace breastfeeding support programs) are beginning to amplify distribution beyond traditional maternity channels.
Strategic implications for 2026 corporate planning
Leaders who use this report convert macro trends into executable choices across five decision domains:
- Portfolio strategy: Invest selectively across wireless, underwire, and hands‑free pumping variants based on margin and brand fit. The market rewards clarity—brands that present a coherent “from pregnancy to pumping” narrative outperform those that treat nursing bras as an afterthought.
- Manufacturing & sourcing: Expect rising emphasis on certified materials and skilled sewing labor. Firms should map supplier certification status, labor specialization, and audit trail to de‑risk scale. Near‑sourcing options matter for speed-to-market of seasonal innovations.
- Pricing & channel mix: Entry-level price points remain important for volume; premium features (pumping compatibility, advanced fabrics) justify higher ASPs and direct-to-consumer channels. Retail assortment decisions should balance trial-driven low-price SKUs and margin-rich premium cores.
- Go-to-market & partnerships: Strategic collaborations—co‑branded bundles with pumping device manufacturers or lactation service providers—accelerate adoption, as seen in recent industry tie‑ups. Retailer and insurer pathways can materially expand addressable reach when paired with clinical validation.
- M&A & innovation scouting: Consolidation and tuck‑ins are already reshaping concentration in parts of the market. Identify targets that provide proprietary hands‑free designs, pump integration, or certification advantages before competition escalates multiples.
What the full PW Consulting report delivers (practical, transaction‑grade)
This market preview accompanies a comprehensive dossier built for implementation. Key operational deliverables included in the full report:
- Proprietary market sizing and demand model (historical 2020–2025 and forecast 2026–2032) with scenario sensitivities to price, channel mix, and hands‑free adoption rates.
- Go‑to‑market playbooks for direct-to-consumer, specialty retail, and mass retail channels, showing SKU rationalization, pricing ladders, and promotion timing to optimize lifetime value.
- Supplier risk maps and a certification tracker focused on material safety (e.g., Oeko‑TEX®), labor skill requirements for inclusive sizing, and supplier lead times by region.
- Segment playbooks—buyer personas for lactating and pregnant cohorts, retailer decision trees, and product feature-set prioritization to maximize conversion.
- Competitive heat maps and M&A candidate shortlists with valuation heuristics tied to portfolio synergies and scale economics.
- Regulatory impact assessment and reimbursement opportunity matrix by major markets—highlighting where partial insurance coverage or workplace programs can be leveraged.
Note: this preview highlights the types of segmentation and models included. The full report contains the granular regional, type, and application splits and underlying datapoints that leaders use in board‑level business cases.
Competitive landscape: profiles and strategic postures
The market’s competitive structure exhibits moderate concentration; three firms account for a meaningful share of branded sales while the top five control a larger portion of specialty revenues. This leaves room for nimble challengers and retailer private labels, but also benefits incumbents that can scale innovation and certification investments quickly.
Representative competitive archetypes analyzed in the report include:
- Specialist innovators — Brands that foreground hands‑free pumping and inclusive sizing, investing in fabric engineering and user‑centric closures. These players are driving product feature expectations in higher‑value channels.
- Heritage intimates — Established bra manufacturers that bring category expertise and distribution scale; their advantage lies in fit engineering and trusted retail relationships.
- Retail/private‑label players — High-volume, value-focused offerings that accelerate category penetration among price‑sensitive buyers; these players pressure conversion economics for all competitors.
We profile specific companies that illustrate these archetypes and their strategic moves—examples include Kindred Bravely (leader in wireless, hands‑free and inclusive sizing innovations), Cake Maternity (full‑coverage and bust‑support specialization), Bravado Designs (seamless everyday comfort and fit focus), Davin & Adley and Momcozy (pump‑integration and hands‑free design leaders), plus European specialists like Anita and Medela who emphasize technical fabrics and clinical compatibility. Recent activity—product launches, award recognitions, and collaborative bundles—signal an acceleration of product differentiation and channel partnerships that will be decisive in 2026.
Supply chain, regulation, and consumer behavior — the operational constraints
Three “noise” factors in the operating environment require immediate attention:
- Labor specialization: Manufacturing nursing bras requires precise cutting and sewing to deliver inclusive fits across size ranges. Labor skill and factory capacity are bottlenecks for rapid line expansions, increasing the value of supplier relationships and manufacturing flexibility.
- Material compliance: Certification standards for maternal apparel are tightening—Oeko‑TEX® and related textile certifications influence supplier selection and time‑to‑market. Brands that pre‑certify fabrics reduce downstream compliance costs and retailer objections.
- Consumer shifts: Wireless and hands‑free pumping styles are moving from trend to expectation in several leading markets. Pricing remains bifurcated: value SKUs drive trial, while advanced features command premium pricing. Reimbursement and workplace support programs are early amplifiers of demand in select geographies.
Recommended 90‑/180‑day roadmap for 2026
- 30 days: Conduct a rapid supplier certification audit and prioritize fabrics that meet Oeko‑TEX® and quick‑dry specifications; identify at least two near‑sourcing options for pilot SKUs.
- 90 days: Validate two pilot SKUs—one wireless hands‑free and one value everyday style—with controlled retail and DTC channels; run A/B pricing and shopper experience tests linked to conversion and returns metrics.
- 180 days: Finalize channel mix guided by pilot economics, secure strategic partnership(s) with lactation or pump manufacturers for bundled offers, and prepare a 12‑month product roadmap emphasizing certification lead times and inventory cadence.
Why PW Consulting’s study accelerates your 2026 decisions
Executives tell us they need three things to move fast: credible market sizing, actionable operational playbooks, and targeted competitive intelligence tied to transaction opportunities. This study delivers all three. It translates macro momentum (baseline market size and 8.1% CAGR) into executable next steps and measurable KPIs—without overwhelming readers with raw micro‑splits in this preview. The full report contains the segmentation, price‑band models, and competitive benchmarking necessary to build investment cases, product roadmaps, and M&A screens for 2026.
For senior leaders planning product launches, channel expansion, or M&A activity in 2026, the study provides the data, scenarios, and operational tools to convert market growth into sustainable margin and market share. Access the complete report to unlock the detailed regional and application breakdowns, SKU-level demand curves, and candidate lists that underpin our recommendations.
For detailed analysis of this topic, please visit the official page: Nursing Bras Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com