

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: IT & Electronics
PW Consulting: VOC Rotor Market to hit USD 259M by 2032 at 4.85% CAGR
By pmarketresearch, 2026-07-30
VOC Rotor Market 2026: Strategic Imperatives from PW Consulting’s VOC’s Rotor Market Study
As companies plan capital allocation, supply-chain resilience, and product roadmaps for 2026, the VOC (volatile organic compound) concentrator rotor market has shifted from a niche engineering solution to a strategic lever for cost, compliance, and competitiveness. PW Consulting’s latest VOC’s Rotor Market study distils five years of historical performance and a forward-looking forecast to 2032, delivering the commercial context executives need to make decisive investments next year. This executive introduction highlights the study’s strategic value while intentionally withholding granular segmentation tables and proprietary scorecards—those items are available in full from the source report.
VOC's Rotor Market
Market at a Glance: Growth, Scale and Concentration
-
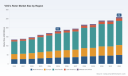
Market trajectory: The global VOC rotor market expanded consistently through 2020–2025, moving from a small base to a materially larger installed market. The 2025 base year is calibrated at USD 183.0 Million (revenue unit: Million, USD), reflecting maturation across semiconductor, automotive, and industrial end markets.
VOC's Rotor Market -
Near- to mid-term outlook: Our forecast uses a compound annual growth rate of 4.85% for 2026–2032, projecting a market approaching USD 259.0 Million by 2032. The growth pattern is steady and characterized by episodic upgrades tied to regulatory cycles and capacity expansions in semiconductor and chemical sectors.
VOC's Rotor Market -
Market structure: Concentration metrics indicate a moderately consolidated supplier landscape—CR3 at approximately 45% and CR5 near 65%—leaving meaningful room for regional specialists and technology-focused entrants to carve niches.
Why 2026 Is a Pivotal Decision Year
Three converging dynamics make 2026 a strategic inflection point for buyers, OEMs, and investors:
-
Regulatory inflection: Energy-efficiency mandates and updated guidelines for solvent-cleaning and VOC concentration devices are accelerating demand for selective adsorption solutions that reduce energy intensity per unit of emission removed. Compliance windows and the capital planning cycles of large industrial players converge in 2026, prompting procurement and retrofit waves.
-
Technology economics: Advances in high-silica zeolites and more durable honeycomb substrates are improving rotor life, reducing maintenance windows, and narrowing the TCO delta versus traditional abatement approaches. These improvements materially influence buy vs. retrofitting decisions in 2026 CAPEX cycles.
-
Operational pressures: Automation-driven labor constraints and higher uptime requirements in semiconductor and automotive production lines increase the value of low-maintenance, high-reliability concentrator rotors—pushing decision-makers to prioritize systems that blend adsorption performance with serviceability.
Strategic Themes for 2026 Decision-Makers
Companies need frameworks that translate the market view into executable choices. The study organizes actionable recommendations across five decision vectors:
-
Procurement and supplier segmentation: Move beyond price-per-unit to total cost-of-ownership models that factor energy consumption, regeneration cycles, rotor life, spare-part lead times, and service contracts. The market’s CR3/CR5 dynamics suggest that strategic supplier partnerships—including exclusive replenishment or managed-service agreements—can yield both pricing and continuity advantages.
-
Technology selection and portfolio positioning: Zeolite-based honeycomb rotors and activated-carbon approaches each deliver competitive advantages depending on feedstock profile, concentration, and duty-cycle. For 2026, prioritize pilot deployments and lifecycle testing for any new rotor chemistry; the TCO inflection often appears only after two to three full service cycles.
-
Manufacturing and retrofit planning: Expect a growing installed-base retrofit market as plants align to updated efficiency mandates. Pre-approved retrofit packages and modular rotor units reduce downtime exposure. Our analysis shows that a staged retrofit strategy—combining pilot lines, regional service hubs, and standardised installation kits—minimizes production disruption.
-
M&A and partnership plays: Mid-sized suppliers with proprietary zeolite mixes or unique honeycomb substrate formulations are attractive bolt-on targets for larger systems integrators aiming to raise CR3. Conversely, well-capitalized regional players can win share via service differentiation and localized supply chains.
-
Risk management and compliance: Integrate rotor performance into corporate emissions monitoring and energy dashboards. Given tightening norms and ISO-referenced expectations for solvent-cleaning equipment, non-compliant assets can attract operational restrictions—accelerating depreciation and forcing earlier-than-planned capital replacement.
Competitive Landscape: Who Matters and Why
The market is shaped by a mix of global integrators, specialist materials firms, and regional equipment makers. The report profiles the leading players and teases strategic implications for 2026 sourcing and product strategies:
-
Seibu Giken Corporation (Japan): A technology leader in honeycomb rotor concentrators, Seibu Giken’s solutions are positioned for semiconductor and high-spec industrial applications where energy-efficiency and low leakage are critical. For buyers, Seibu Giken represents premium performance with engineered systems expertise—suitable where reliability and regulatory certainty outweigh capital sensitivity.
-
Huashijie Environment Technology (HSJ) (China): HSJ’s focus on molecular sieve adsorption rotors combined with RTO systems targets cost-effective fixed-source industrial abatement. Their offerings are relevant for manufacturers prioritizing integrated thermal-desorption workflows within regional compliance regimes.
-
Nichias Corporation (Japan): With its HONEYCLE HZ series and long-standing product pedigree, Nichias emphasizes robust honeycomb zeolite solutions for solvent cleaning and low-concentration emissions. Their product lifecycles and service literature make nichias a pragmatic partner for long-term maintenance planning.
-
Munters (Sweden): Munters’ zeolith rotor concentrators are designed for high-volume, low-concentration streams. Their expertise in engineered adsorbent blends makes them a compelling partner where performance per square meter of rotor is a primary procurement metric.
-
Taikisha Ltd. (Japan): Taikisha brings systems integration strength through rotary RTO systems and rotor components. They are a natural partner for complex retrofit projects where HVAC, heat recovery, and rotor staging must be engineered end-to-end.
-
ProFlute AB (Sweden): As a specialist in PPM molecular sieve and silica gel rotors, ProFlute targets desiccant and niche abatement applications that support VOC removal in humidity-sensitive processes. Their niche focus can be attractive for R&D collaborations or regionally specialized contracts.
Operational Realities: Materials, Standards and the Supply Chain
Material inputs and standards are practical constraints that executives often underestimate. Key supply-side realities to factor into 2026 planning include:
-
Raw materials: Modern concentrator rotors are constructed from honeycomb inorganic paper substrates impregnated with high-silica zeolites, activated carbons, or molecular sieves. Sourcing of high-grade zeolite and consistent substrate manufacturing quality materially affects rotor life, adsorption performance, and replacement cadence.
-
Standards and maintenance norms: ISO-referenced standards for solvent cleaning and concentration devices emphasize routine inspection and performance verification. Buyers should require documented maintenance protocols, test-data at commissioning, and contractual response times as part of procurement.
-
Service economics: Energy efficiency mandates raise the value of rotors that reduce regeneration energy and heat loss. Lifecycle energy modelling—incorporated into procurement evaluation—often flips the decision from replacing to retrofitting existing capture systems.
What the VOC’s Rotor Market Study Delivers (Practical Components)
The full PW Consulting study is intentionally operational. Key deliverables designed for 2026 decision cycles include:
-
Proprietary market model: Scenario-based forecasts (base, accelerated regulation, and slower CAPEX) through 2032 with sensitivity to energy prices and regional compliance timing.
-
Supplier scorecards: Comparative assessments across technology, capacity, service footprint, warranty terms, and supply-chain risk—designed to plug into RFP evaluations.
-
TCO calculators: Configurable templates to compare zeolite vs activated-carbon rotor solutions across duty cycles and energy tariffs.
-
Retrofit playbooks: Step-by-step guidance to plan pilot-to-scaling rollouts with downtime mitigation, mechanical interfaces, and commissioning checklists.
-
Risk heatmaps: Concentration of regulatory and raw-material risks by region and application class—presented to support executive risk registers.
How Executives Should Use This Intelligence in 2026
For procurement leaders: use the TCO models to convert vendor claims into lifecycle outcomes; require pilot validation for new rotor chemistries.
For manufacturing and operations: prioritize modular retrofit contracts and pre-negotiated spare-part inventories to reduce mean time to repair.
For corporate development and strategy: identify midsize materials players with differentiated zeolite blends or honeycomb manufacturing as primary M&A targets to consolidate technical advantage.
For sustainability and compliance functions: integrate rotor performance into emissions accounting and capital planning to avoid unexpected asset stranding as standards tighten.
Next Steps and How to Access Full Intelligence
This introduction outlines the strategic imperatives PW Consulting has surfaced for 2026. The full VOC’s Rotor Market study contains the detailed segmentation tables, regional and application modelling, unit-price decks, supplier contract exemplars, and the downloadable TCO calculator that underpin recommended actions. Those proprietary datasets (including exact regional and application splits and supplier-level financials) are intentionally withheld from this preview to preserve their operational value.
To obtain the complete report, model files, and an advisory session tailored to your business, please visit the VOC’s Rotor Market report page or contact PW Consulting’s industry practice. Armed with the study, executive teams can turn the 2026 inflection into a strategic advantage—optimizing capital, reducing compliance risk, and positioning operations for the next wave of regulation and demand.
For detailed analysis of this topic, please visit the official page: VOC's Rotor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: HD Map Market to Surge to USD 2.01B by 2032 at 21.74% CAGR
By pmarketresearch, 2026-07-30
HD Map Market 2026: Strategic Imperatives from PW Consulting’s Forward-Looking Brief
Executive summary
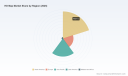
High-definition (HD) maps are moving from a niche enabler for research vehicles to a foundational layer for commercially viable advanced driver assistance systems (ADAS), automated driving features, and software-defined vehicle platforms. Our latest HD Map Market study (base year 2025) documents this transition, quantifying a rapid expansion that accelerates through the late 2020s. The market grew materially from the start of the decade and, under mainstream adoption trajectories, is forecast to expand at a compound annual growth rate (CAGR) of 21.74%—reaching an addressable market size that surpasses two billion USD by 2032. For executives preparing strategic plays in 2026, this is not a mid-cycle technology bet: it is a multi-year platform decision that will shape product roadmaps, partnerships, and regulatory compliance strategies.
HD Map Market
Why this research matters for 2026 corporate decisions
By 2026, organizations will face converging inflection points: stronger regulatory expectations for map-backed safety systems, the emergence of software-defined vehicle architectures that monetize data, and the operational realities of producing and maintaining centimeter-level map fidelity at scale. Our brief synthesizes historical trends (2020–2025), immediate market signals, and forward forecasts (2026–2032) to create a decision-ready lens for three critical audiences: OEM strategy teams, Tier‑1 suppliers and ADAS software vendors, and investors evaluating platform plays versus point-solution bets.
HD Map Market
-
For OEMs: the study clarifies how HD maps integrate with software-defined vehicle stacks and when in-vehicle vs. cloud-first map architectures deliver lower total cost of ownership.
HD Map Market -
For suppliers: it provides a framework to evaluate investments in mapping infrastructure, data pipelines, and edge compute that enable e‑Horizon and ODD-aware functionality.
-
For investors and M&A teams: it establishes scenario-based revenue and margin paths—identifying where consolidation is likely and where specialist players retain durable advantages.
Market trajectory in one view
Between 2020 and 2025, the HD map market demonstrated strong expansion as pilot deployments scaled and regulatory drivers increased the value of precise map layers. Our baseline shows the market expanding from a small multi-hundred-million-dollar segment in 2020 to a materially larger base by 2025, and continuing to accelerate thereafter. Under the median scenario, the market reaches approximately 2.01 billion USD by 2032—underpinned by a 21.74% CAGR across the forecast window. This pace reflects accelerating unit adoption in production vehicles, recurring cloud subscription models, and increasing demand for continuous map refreshes tied to advanced driver assistance and automated driving features.
Strategic implications — five priorities for 2026
-
Design your map architecture as a product decision, not an afterthought. Decisions about cloud vs. embedded map stacks have long-term implications for software update cadence, data ownership, and monetization. Our research maps out how different architectural choices impact time-to-market and lifecycle cost for feature sets tied to dynamic map layers and live updates.
-
Prioritize regulatory readiness. New and evolving regulations—such as requirements for Intelligent Speed Assistance and other safety-related mandates—are increasingly enforced via map-backed inputs. HD maps are already being used to define Operating Design Domains (ODDs) for SAE Level 2–4 activations: companies that align mapping data pipelines with compliance workflows will reduce time-to-certification and avoid retrofit costs.
-
Invest selectively in sensor + processing capabilities. High-quality map production requires professional mobile mapping systems equipped with LiDAR, high-resolution cameras, and GNSS-RTK systems, as well as significant labeling and compute resources. Our scenarios show when in-house capture fleets make sense versus partnerships with specialist map providers.
-
Build flexible monetization models. The market is shifting toward recurring revenue via cloud subscriptions and live-layer services, but opportunities continue for licensing, per-vehicle entitlements, and value-added location intelligence for fleet operations. Our report includes GTM architectures that reconcile OEM purchasing cycles with consumer-facing subscription models.
-
Plan for labor and compute constraints. Map creation is labor- and compute-intensive: manual annotation remains a significant cost driver where automated pipelines are immature. Strategic investments in ML tooling, workforce development, and partnerships with compute providers are essential to scale without disproportionate margin erosion.
What this report delivers (practical contents)
-
Clear market sizing and scenario models (base year 2025; forecast through 2032) that let you stress-test revenue and margin outcomes under adoption, price, and refresh-rate sensitivities.
-
Vendor benchmarking and capability matrices that compare map fidelity, latency, update cadence, and integration models—crafted to support vendor selection and partnership negotiations.
-
Technology stack and ops playbook: mobile mapping system requirements, data pipeline templates, ML labeling approaches, and edge/cloud synchronization patterns.
-
Regulatory impact analysis and compliance checklists for mapping inputs used in ISA, GSR2, and ODD enforcement for SAE levels 2–4.
-
Commercial model archetypes and go-to-market frameworks for OEMs, Tier‑1s, and pure-play map providers, including pricing levers and channel strategies.
-
Risk matrix and mitigation strategies covering data quality, supply-chain concentration for specialized equipment, and talent bottlenecks.
Competitive landscape: what to watch in 2026
The vendor field is diverse—ranging from large, multi-modal map platforms to specialist firms with precise, lane-level mapping capabilities. Market concentration remains moderate: our concentration metrics indicate an ecosystem where several leaders hold meaningful shares, yet there remains space for focused specialists and regional players to compete on technical differentiation and service models.
-
HERE Technologies (Eindhoven, Netherlands) — https://www.here.com. HERE remains a bellwether, offering a live HD map portfolio that targets real-time layer delivery for ADAS and automated driving. Recent developments include an AI-enhanced product push aimed at software-defined vehicle platforms unveiled at CES 2026—signaling an expanded strategy that bundles live mapping with higher-level driving and assistance software.
-
Dynamic Map Platform (DMP) (Livonia, Michigan, USA) — https://dmp-maps.com. DMP differentiates on absolute mapping accuracy and targeted coverage for key markets. In 2025 the company announced substantial expansion of its North American coverage with sub-15 cm RMSE commitments for primary road classes—a positioning that appeals to ADAS integrators requiring deterministic road models and e‑Horizon capabilities.
-
Mapbox (San Francisco, California, USA) — https://www.mapbox.com. Traditionally strong in developer and in-vehicle navigation stacks, Mapbox is advancing lane-level and 3D navigation features. Early 2026 announcements showcase a 3D Lanes capability developed with BMW and an in-vehicle deployment powering next-generation navigation in production vehicles—bridging developer-friendly APIs and OEM-grade map responsibilities.
Industry dynamics and operational noise
Beyond vendor competition, four systemic dynamics will shape outcomes and should be central to 2026 planning:
-
Labor and ML trade-offs: High-fidelity map creation still requires significant manual labeling or investment in high-performing ML training pipelines. Organizations must weigh labor cost predictability against capital expenditure in GPU fleets and annotation platform tooling.
-
Specialized equipment dependencies: HD map production depends on Mobile Mapping Systems outfitted with LiDAR, cameras, and GNSS-RTK. Much of this hardware supply originates in select geographies, which can constrain rapid scale-up in regions without established procurement channels.
-
Regulatory accelerants: Regulations that mandate map-backed safety functions or that use maps to define legal ODDs will accelerate demand from conservative OEMs and fleet operators looking to de-risk deployments.
-
Infrastructure and integration complexity: Real-time map refreshes and live-layer services increase demands on connectivity, edge compute, and harmonized data schemas across suppliers. Integration friction remains the most common hidden cost in multi‑vendor implementations.
Quick-read strategic checklist for leadership teams (2026)
-
Confirm whether HD map capability is core to your product differentiation and allocate a multi-year budget accordingly.
-
Map regulatory obligations to product release timelines—prioritize early investments where compliance timelines compress feature launches.
-
Negotiate vendor SLAs that include update cadence and quality metrics; focus on end-to-end responsibilities (capture → processing → delivery).
-
Invest in a hybrid capture strategy: a mix of in-house MMS assets for critical regions and specialist partners for breadth and refresh scale.
-
Build scenario-informed financial models that reflect subscription uplift, per-vehicle royalties, and potential post-sales service revenue.
Conclusion and next steps
The HD map market is entering a decisive phase where technological capability, regulatory clarity, and commercial models coalesce to determine winners and losers. Our report gives decision-makers the contextual intelligence and operational playbooks to act prudently in 2026—balancing investment in precision mapping assets with partnerships and product design that monetize map-enabled features across the vehicle lifecycle.
To access the complete set of market tables, vendor scores, scenario models, and downloadable playbooks that underpin these strategic recommendations, please consult the full PW Consulting HD Map Market report on our website. The granular segmentation data, supplier scorecards, and downloadable financial models are intentionally gated to support enterprise decision workflows and to safeguard the fidelity of our benchmarking.
For detailed analysis of this topic, please visit the official page: HD Map Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Near-IR Camera Market to Reach USD 232.91M by 2032 at 7.3% CAGR — PW Consulting
By pmarketresearch, 2026-07-30
Near IR Camera Market: Strategic Briefing for 2026 Decision-Makers
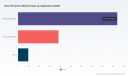
As PW Consulting’s Senior Industry Analyst, I present a concise—yet strategically rich—preview of our full Near Infrared (NIR) Camera Market research suite. This briefing synthesizes the market dynamics, competitive posture, risk vectors, and actionable decision frameworks that matter most for capital allocation, product roadmaps, and M&A activity in 2026. The analysis is grounded in a market model with a 2025 base year (USD, Million), a historical window from 2020–2025 and a forecast horizon through 2032 at a compound annual growth rate (CAGR) of 7.3%—illustrating a clear, multi-year expansion from the 2025 base toward the 2032 outlook.
Near IR Camera Market
Why this research matters for 2026 strategic choices
- Timing and scale: With the market expanding at a steady mid-single-digit CAGR, 2026 is a juncture where investment decisions either accelerate platform-scale plays (supply chain, high-volume optics/packaging) or prioritize niche, high-margin product differentiation (cooled sensors, extended-SWIR).
- Technology inflection: Innovations in sensor materials and cooling (including extended SWIR sensor architectures and compact Stirling solutions) are shifting performance-cost trade-offs. Firms that align product roadmaps to the emerging technical envelope will lock in lead positions for the next product cycle.
- Commercial leverage: Buyers across medical diagnostics, industrial inspection, defense, and telecom increasingly expect not only imaging performance but validated systems-level compliance (functional safety, environmental ruggedization, and regulatory certifications). Vendors that can combine component supply with system validation win larger integrated deals.
- M&A and partnerships: Fragmented supplier economics and specialized IP pockets create high potential for bolt-on acquisitions and strategic alliances—especially for players seeking to accelerate time-to-market for SWIR-enabled systems.
High-level market trajectory (selected view)
- Base year context: The market model uses 2025 as the reference point, capturing the cumulative evolution across 2020–2025 and setting the stage for scenario planning in 2026.
- Growth direction: Under our central-case assumptions the market continues its steady growth through 2032, reflecting broader adoption across medical, industrial, and defense segments as well as incremental adoption in telecom and automotive niches.
- Implication: The growth profile supports both scale and specialization strategies—investors should choose based on margin target, time-to-payback, and exposure tolerance to supply-chain cycles.
Key demand and technology dynamics
- Sensor economics and architecture: The dichotomy between silicon-based designs and InGaAs (and emerging extended-SWIR) approaches defines product positioning—each presents different cost structures, cooling needs, and performance envelopes (sensitivity, spectral range, speed).
- Systemization over components: Customers increasingly value turnkey modules—camera cores plus validated optics, software stacks, and certification artifacts—over chip-only wins. This favors vertically integrated suppliers and OEM partners able to deliver system-level value.
- Application pull: Medical diagnostics (non-invasive imaging and spectral tissue assessment), high-speed industrial inspection, telecom test & measurement, and surveillance/defense each generate distinct performance and compliance requirements that shape procurement cycles and vendor selection.
- Regulatory and standards momentum: Functional safety requirements for automotive integrations and MilSpec/industrial ruggedization for defense and aerospace exert a gating effect on addressable opportunities. Vendors with documented standards compliance obtain faster qualification windows.
Competitive landscape—who matters and why
The market remains commercially fragmented: leading suppliers deliver differentiated IP (sensor design, cooling, core modules) while a wider set of specialists fills niche needs. Our competitive mapping places emphasis on product architecture, go-to-market routes (OEM vs system integrator), and certification footprints.
Near IR Camera Market
- Hamamatsu Photonics K.K. (Japan) : Renowned for InGaAs cameras across area and line-scan formats. Strengths lie in sensor quality, scientific-grade reliability, and broad wavelength coverage—positioned for lab, medical, and high-precision industrial roles.
- Xenics / Exosens (Belgium) : Specialist SWIR provider focused on InGaAs cores and cameras for machine vision and defense. Competitive edge in customized detector cores and modular integration for machine-vision OEMs.
- Teledyne FLIR OEM (United States) : Large OEM channel presence and recent product extensions targeted at high-speed telecom and automotive functional-safety use-cases. Strong commercial reach into systems integrators and tiered partners.
- Raptor Photonics (U.K./U.S.) : Rapid product innovation in extended SWIR—recent launches demonstrate a push into higher-performance, cooled sensor modalities and scale-up of production capabilities to meet market demand.
- Sensors Unlimited (Collins Aerospace, U.S.) : Defense and aerospace-specialist SWIR supplier; emphasis on certified, rugged platforms suited to haze-penetrating imaging and airborne applications.
- Photonic Science (U.K.) : Supplier of cooled and uncooled SWIR cameras for scientific imaging—competitive where measurement fidelity and lab-grade performance are required.
- New Imaging Technologies / LYNRED (France) : Focus on high-speed, high-dynamic-range SWIR cameras for industrial inspection; investment in CAD modeling and customer co-design strengthens OEM adoption.
Recent company moves (product launches, production scaling and CAD releases) indicate accelerated investment in extended-SWIR sensor modalities and cooling subsystems; these developments materially influence 2026 supplier shortlists and capital planning.
Near IR Camera Market
Market structure and concentration
The competitive map shows a market where specialized vendors hold distinct technology advantages but no single supplier dominates. Such structure supports a mixture of procurement strategies—multi-sourcing for core detectors, single-sourcing for fully integrated, certified modules where risk transfer and lifecycle support are critical.
Risk factors and scenario sensitivities
- Supply-chain concentration: Sensor fabrication and specialized cooling subsystems are chokepoints. Procurement teams should stress-test supplier continuity and identify second-source pathways.
- Price and margin pressure: Sensor and optics cost volatility creates margin compression for lower-complexity camera models. Product teams should model ASP sensitivity and preferred-margin thresholds before committing to high-volume programs.
- Standards and certification delays: Functional-safety and defense certifications can add program timelines and cost. Early engagement with certifying bodies and co-development of test plans is necessary to avoid go-to-market slippage.
- Technology obsolescence: Rapid innovation in sensor materials and readout electronics can shorten product lifecycles; firms must balance R&D cadence with scalable manufacturing investments.
2026 Playbook — Practical actions for executives
- Prioritize portfolio clarity: Define which products will be scaled for volume and which will be high-margin, differentiated systems—align investment horizons and supply commitments accordingly.
- Secure sensor supply lines: Convert critical suppliers into strategic partners via long-term offtake agreements, co-investment in foundry capacity, or exclusive development pathways for unique sensor variants.
- Certify early, sell faster: Invest in pre-certification and qualification artifacts (safety, environmental, MilSpec) during prototype phases to shorten procurement cycles with enterprise and defense buyers.
- Adopt modular architectures: Design camera cores that can be re-used across medical, industrial, and defense SKUs to reduce time-to-market and amortize R&D across multiple revenue streams.
- M&A and partnerships: Target acquisitions that fill capability gaps—sensor readout IP, cooling subsystems, or application-specific imaging software—rather than broad, unfocused scale plays.
- Commercial rigor: Implement value-based pricing for differentiated imaging solutions and preserve margin in commodity SKUs through manufacturing efficiency and bundled services.
What the full PW Consulting report delivers (practical contents)
- Comprehensive market model (historical and forecast through 2032) with scenario levers for sensor pricing, certification timelines, and adoption curves.
- Actionable go-to-market playbooks and buyer decision matrices for medical, industrial, defense, and telecom customers.
- Technology radar comparing silicon vs InGaAs vs extended-SWIR options, including cooling trade-offs and roadmap implications.
- Supplier heatmaps, capability scorecards, and an M&A target shortlist based on integration ease and IP defensibility.
- Price-to-performance benchmarking and recommended procurement clauses to mitigate supply and warranty exposure.
- Regulatory and standards checklist tailored to automotive functional safety, aerospace/defense ruggedization, and global market entry.
- Interactive dashboard for scenario testing—align product investment with revenue and margin sensitivity in real time.
How to use this intelligence in 2026
Executives should treat the NIR camera space as a portfolio decision: preserve optionality where technology and standards are still settling, and accelerate where the pathway to certification and scale is clear. Use the full report to populate investment memos, supplier scorecards, and M&A screens with evidence-based inputs rather than intuition-driven estimates.
For leaders preparing budgets, product roadmaps, or acquisition theses in 2026, this research provides a defensible market view, validated vendor assessments, and pragmatic mitigation plans to convert growth potential into measurable returns. Accessing the full dataset and the interactive scenario models will allow your team to turn the high-level strategies outlined here into executable plans tailored to your risk appetite and time horizon.
PW Consulting’s full Near IR Camera Market report contains the granular segmentation, buyer economics, and supplier-level datasets needed to operationalize these recommendations—contact our research desk to unlock the complete analysis and interactive tools.
For detailed analysis of this topic, please visit the official page: Near IR Camera Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
GNSS Market 2026: Strategic Imperatives for Executives — A PW Consulting Preview
Executive teaser
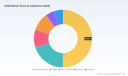
The global GNSS market has entered a phase of renewed strategic importance for enterprise leaders. After expanding from roughly USD 163 billion in 2020 to USD 256.2 billion in 2025, the sector is forecast to continue robust growth into the next decade — approaching USD 480 billion by 2032 at a 9.48% compound annual growth rate (2026–2032). These headline numbers disguise a much more complex competitive and regulatory environment: technology-driven jumps in availability and resilience, new firmware- and software-centered business models, and shifting regulatory prescriptions around interference and spoofing are rewriting the playbook for product, M&A, and platform strategies.
GNSS Market
Why PW Consulting’s GNSS Market research matters for 2026 decisions
- Strategic clarity: The market’s strong macro trajectory creates attractive growth corridors, but the value has migrated from pure hardware to integrated systems (firmware, corrections, and services). Senior leaders must align investment choices to capture recurring service revenue and defend margin against commoditization.
- Risk management: Updated regulatory guidance and validated jamming/spoofing test results require near-term technical and compliance responses — both to protect existing deployments and to enable new use cases in safety-critical segments.
- M&A timing: The sector remains comparatively fragmented at the top (top-5 share in the mid‑20s percent range), which creates windows for consolidation and capability acquisition — particularly for players looking to scale resilient, multi-constellation solutions quickly.
- Go-to-market choices: Volume markets demand modular, low-cost solutions while mission-critical segments continue to prize certified high-reliability stacks. A one-size-fits-all approach exposes vendors to pricing pressure and missed revenue pools.
Macro and regulatory dynamics to watch in 2026
Three interlinked dynamics will drive board-level choices this year:
GNSS Market
- Resilience and safety regulation: Aviation and other safety-critical sectors have new guidance that elevates GNSS interference risk to an operational priority. The March 2026 update on GPS/GNSS interference, jamming, and spoofing is already influencing procurement specifications and certification roadmaps.
- Technology-enabled availability gains: Recent product and firmware advances are materially improving signal availability in challenging environments. Case in point: firmware enhancements introduced in early 2026 that capture additional signals have produced measurable availability uplifts, validating software as a high-leverage intervention to improve field performance.
- Validation and standardization: Industry testing campaigns and independent jammertests have validated resilience claims for select suppliers, accelerating procurement cycles in defense, aerospace, and industrial robotics. These results are influencing both public sector standards and private purchasing thresholds.
Competitive landscape — what the leaders are doing and why it matters
The competitive map is bifurcated: a set of specialized, technology-led vendors focus on high-reliability and premium applications, while a broad group of module and system suppliers address high-volume commercial and consumer markets. Recent strategic moves illustrate two clear playbooks.
GNSS Market
- Capability consolidation and resilience: The acquisition activity and product integrations pursued by major players underscore a shift toward vertically integrated positioning stacks for mission-critical customers. A notable transaction completed in 2025 brought a specialist resilient-GNSS provider under the umbrella of a larger systems integrator, accelerating that integrator’s path to deliver “assured positioning” for autonomy and defense use cases.
- Software and service differentiation: Firmware upgrades and corrective services are now tangible levers for performance differentiation. Suppliers that combine robust signal processing with correction and subscription services are capturing higher-margin, recurring revenue — while simultaneously raising switching costs for their customers.
How specific vendors exemplify these trends:
- u-blox (Thalwil, Switzerland): Continuing to strengthen its high-precision chip and module portfolio, with clear emphasis on automotive ADAS, industrial robotics, and precision agriculture where integration of sensor stacks and software-defined features matters.
- NovAtel (Calgary, Canada): Scaling OEM receiver capability and value-added correction services; recent firmware releases have focused on improving reliability in contested environments — a meaningful differentiator for aerospace and defense buyers.
- Septentrio (Leuven, Belgium): Known for resilient multi-frequency, multi-constellation receivers; product family extensions into ultra-compact modules underscore a two-track approach — premium performance and migration to higher-volume deployments.
- Topcon Positioning Systems (Tokyo, Japan): Maintaining a strong position in surveying, construction and agriculture through integrated receiver/base/rover solutions and targeted product launches that localize capability for high-growth agricultural markets.
- Trimble (Colorado, USA): Leveraging broad systems expertise across surveying, construction and automated vehicles — combining hardware, cloud services and applications to lock in enterprise customers.
- Quectel (Shanghai, China): Focused on scalable GNSS modules and integrated IoT offerings to capture volume-driven automotive and machine-control opportunities.
Practical, board-level implications for 2026
- Reprioritize R&D and product roadmaps around resilience and software — allocate 2026 investment to firmware, signal-processing IP, and correction-service capabilities that materially improve availability in degraded RF environments.
- Move from transactional sales to subscription-led monetization where possible — design product bundles that combine hardware, firmware updates, and correction services to create sticky recurring revenue.
- Treat certification and standards leadership as strategic assets — sponsoring standards work, participating in government-industry rulemaking forums, and aligning engineering roadmaps with newly updated regulatory guidance will reduce procurement friction in safety-critical segments.
- Use targeted M&A to fill capability gaps — with the market’s top concentration relatively low, disciplined acquisitions of resilient-sensor designers or regional correction networks can accelerate market entry more cost‑effectively than greenfield R&D.
- Reassess supply-chain and sourcing strategies — for high-volume modules, cost-down and manufacturing scalability are must-win battles; for mission-critical platforms, having dual-source, certified components is essential to satisfy procurement and safety regimes.
What PW Consulting’s full GNSS Market report delivers (practical contents)
Our comprehensive market study is structured to convert insight into action. Key deliverables include:
- Demand models and scenario forecasts with base year 2025 and a detailed 2026–2032 outlook to support budgeting and capital allocation.
- Competitive benchmarking: supplier scorecards, technology roadmaps, and go-to-market motions for leading vendors.
- Segment playbooks for product design, pricing, and channel strategies across consumer, industrial and safety-critical customers.
- Regulatory impact assessments and certification timelines to inform compliance, testing, and advocacy planning.
- M&A target lists and diligence templates derived from capability gaps and concentration dynamics.
- Supply-chain risk heatmaps and mitigation playbooks for component scarcity, certification bottlenecks, and manufacturing scale.
- Practical implementation checklists and 90/180/360-day action plans tailored for executive teams.
Note: this preview highlights the strategic themes and macro traction that matter for 2026 planning. The full report contains the detailed segment and regional breakdowns, datasets and model inputs that executives use to build precise financial scenarios and operational plans; those granular figures are intentionally reserved for the full deliverable.
How to use this research in your 2026 planning cycle
- Scenario planning: Use the report’s forecasting scenarios to stress-test product roadmaps and service-revenue targets under differing regulatory and technology-adoption assumptions.
- Budget alignment: Translate the forecast and competitive benchmarks into R&D, certification, and go‑to‑market budgets that prioritize resilience and software monetization.
- M&A screening: Apply our capability-gap matrix to shortlist inorganic opportunities that accelerate time-to-market for assured-positioning solutions.
- Regulatory engagement: Align internal compliance milestones with the latest guidance on interference and spoofing to avoid procurement disqualification in critical accounts.
Closing — the strategic choice for 2026
The GNSS market’s growth curve creates a rare moment: the underlying market is expanding rapidly, yet leadership is still defined by capability, integration and regulatory alignment more than scale alone. Executives who reposition their organizations around resilient positioning stacks, software-driven differentiation and carefully timed capability acquisitions will convert market growth into defensible value. For teams preparing 2026 budgets and board materials, PW Consulting’s full GNSS Market report supplies the granular segmentation, scenario modeling, and execution templates needed to move decisively — while this preview surfaces the strategic priorities that should be debated at the top of the house.
To access the full dataset, regional and application splits, and proprietary benchmarks that power our recommendations, please consult the complete GNSS Market report on the PW Consulting research portal.
For detailed analysis of this topic, please visit the official page: GNSS Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Logistics Services (3PL & 4PL) Market Poised for 9.25% CAGR Through 2032
By pmarketresearch, 2026-07-30
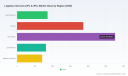
Logistics Services (3PL & 4PL) Market — Strategic Preview for 2026 Decision-Makers
This preview presents the high-level implications of PW Consulting’s forthcoming Logistics Services (3PL & 4PL) Market study and explains why the analysis will be a decision-critical input for corporate strategy teams in 2026. Built on a 2025 base and a 2026–2032 forecast horizon, our modeling shows a continued, material expansion of the outsourced logistics economy at a compound annual growth rate of approximately 9.25 percent. After recovering from pandemic-era disruption, the total industry value climbed from roughly USD 902 billion in 2020 to about USD 1.40 trillion by 2025 and, under the central case, approaches roughly USD 2.61 trillion by 2032. That scale and pace reshape sourcing priorities, capital planning, and competitive positioning for shippers, logistics providers and investors alike.
Logistics Services (3PL & 4PL) Market
Why this study matters for 2026 strategy
-
Prioritizing investment: With double-digit growth on a multi-year horizon, firms must be selective about where to deploy capital—automation, control tower capabilities, and logistics orchestration are common high-return bets. Our study quantifies payoff timelines under alternate demand and cost scenarios so CFOs can sequence expenditures to preserve liquidity while capturing efficiency gains.
Logistics Services (3PL & 4PL) Market -
Supplier and partner strategy: Fragmentation remains a structural feature of the market, creating both arbitrage and risk. The report gives procurement teams a practical vendor-selection framework and negotiation playbook geared to 3PL/4PL engagements—emphasizing outcome-based KPIs, risk-sharing terms, and transition safeguards.
Logistics Services (3PL & 4PL) Market -
Network and footprint decisions: As omnichannel fulfillment proliferates, the right warehouse footprint and transportation mix can be the difference between competitive cost-to-serve and margin erosion. Our location-optimization models translate market growth and regional demand trends into actionable siting scenarios.
-
Resilience and volatility management: Recent industry indicators show capacity contraction in key corridors and continued labor pressure. The study provides scenario-based contingency plans—inventory buffers, dual-sourcing templates, and dynamic routing playbooks—to help executives harden supply chains without permanently bloating operating costs.
-
M&A and portfolio plays: For investors and corporate development teams, our report highlights where scale matters and where niche specialization wins, helping to prioritize targets and structure earnouts tied to operational KPIs rather than top-line vanity metrics.
Macro dynamics shaping 3PL & 4PL through 2026 and beyond
-
E-commerce and omnichannel complexity continue to be structural demand engines. These shifts increase the share of fulfillment and last-mile complexity in many shippers’ cost stacks, pushing them towards integrated 4PL orchestration for end-to-end visibility.
-
Labor scarcity and technology acceleration operate in tandem. Most providers are investing in automation and software-driven control towers to offset labor constraints and to deliver measurable service improvements. Industry studies and practitioner surveys repeatedly cite labor and technology as co-equal forces transforming provider capabilities.
-
Capacity signals are mixed and volatile. Recent freight and capacity indices indicate intermittent contraction in some segments even as aggregate demand grows—creating upward pressure on spot rates and incentivizing longer-term contracts for critical lanes.
-
Regulatory and sustainability drivers are rising up the agenda. Compliance, decarbonization roadmaps, and traceability requirements are widening the services that strategic 3PLs and 4PLs must offer, from emissions reporting to circular logistics for returns management.
-
Market structure remains moderately fragmented: the concentration metrics in our analysis show that while large global integrators hold meaningful capabilities, a long tail of regional specialists continues to capture meaningful volumes—creating options for both cost and service customization.
What PW Consulting’s full report delivers (practical, executable outputs)
-
Executive and Board Briefs — concise, slide-ready narratives linking macro scenarios to company-specific actions.
-
Forecast Engine — a reproducible model with base-case and stress-case outputs across the 2026–2032 horizon (built on transparent assumptions and tested against historical patterns).
-
Operational Playbooks — procurement templates, service-level agreements, transition risk checklists and KPI dashboards tailored to both 3PL and 4PL engagements.
-
Technology Prioritization Matrix — ROI-backed sequencing for control towers, warehouse automation, and AI-enabled transportation orchestration.
-
Network Optimization Tools — scenario-based facility siting and inventory-placement models to support CAPEX decisions and contract structuring.
-
Competitive Benchmarking — qualitative and quantitative scorecards for leading providers, with due-diligence questions for partnership and acquisition candidates.
-
Risk & Compliance Framework — regulatory impact assessments and ESG implementation roadmaps for logistics operations.
-
Case Studies & Implementation Timelines — real-world examples and 90/180/540-day workplans for pilots and rollouts.
Competitive landscape: what leading providers are doing now
The competitive field blends global integrators, contract-logistics specialists, and regional champions. Established players are converging on three strategic moves: (1) embedding technology and control-tower capabilities to offer 4PL orchestration, (2) deploying automation and robotics in contract logistics, and (3) expanding service portfolios to include reverse logistics, fulfillment and sustainability services.
-
C.H. Robinson is accelerating its software and orchestration capabilities — most recently introducing an AI-driven system to autonomously manage multi-modal 4PL shipments — positioning itself to capture value from customers seeking automated decisioning across ocean, air, rail and truck flows.
-
GXO Logistics continues to emphasize contract logistics and warehouse automation, pairing robotics deployments with process redesigns to raise throughput and reduce cost-per-order for large retail and industrial customers.
-
Expeditors and traditional freight-forwarding leaders are leveraging customs expertise and integrated forwarding to upsell higher-margin supply-chain management services.
-
Global network operators such as Kuehne + Nagel, DHL Supply Chain and DSV are doubling down on 4PL orchestration and industry-specific platforms, betting that end-to-end digital offerings will win larger enterprise partnerships.
-
U.S.-focused operators like XPO and J.B. Hunt are exploiting modal strengths—intermodal and last-mile—to defend and expand commercial relationships in high-density markets.
-
Regional and specialist players such as Geodis and CEVA continue to thrive by integrating vertical-specific expertise (e.g., automotive, life sciences) with flexible contract terms, offering an alternative to the “one-size-fits-all” global integrator model.
Recent industry signals to watch in 2026
-
AI and autonomy are moving from pilots to production for orchestration and planning — the industry’s attention at trade shows this spring confirmed technology adoption is now a board-level topic.
-
Conferences and forums in 2026 focused heavily on volatility management and collaboration models, reflecting an immediate need for providers and shippers to co-invest in capacity smoothing mechanisms.
-
Independent indicators show the U.S. 3PL market continuing to expand and that the U.S. 4PL segment remains an emergent but fast-growing component of overall logistics spend—both trends underscoring rising demand for orchestration services.
-
Capacity indices are signaling intermittent tightening, which should push negotiators to build flexibility clauses and surge-capacity arrangements into contracts offered in 2026.
How to convert this intelligence into a 90/180/540-day plan
-
First 90 days — stress-test current contracts, run a supplier capability heatmap, and launch two targeted pilots: one for control-tower orchestration and one for warehouse automation ROI measurement.
-
Next 180 days — standardize commercial terms across your carrier and contract logistics portfolio, renegotiate critical lanes with indexation and performance incentives, and establish a cross-functional deployment team for the highest-value automation pilot.
-
By 540 days — finalize network optimization decisions informed by pilot data, execute phased rollouts of orchestration tech, and pursue strategic alliances or acquisitions only where they deliver clear, measurable improvements in service or cost-to-serve.
Where we draw the line in a public preview
To preserve the utility of the report for commercial decision-making, this preview intentionally omits the granular regional and application-level breakouts, and it does not reproduce the detailed segment tables and proprietary model outputs. Those items — segmented projections, country- and application-level demand curves, provider scorecards with quantified capability ratings, and downloadable modeling spreadsheets — are included in the full PW Consulting Logistics Services (3PL & 4PL) Market report and the companion data package available via our report portal.
Next steps for readers
If your organization is updating sourcing strategies, planning discrete automation investments, or building a 4PL partnership roadmap in 2026, PW Consulting’s full study will deliver the specific inputs and playbooks you need to convert market trends into profitable action. The full report contains the segmented forecasts, provider comparisons and financial models referenced here; request access through our report page to obtain the detailed tables, scenario models and implementation toolkits.
For detailed analysis of this topic, please visit the official page: Logistics Services (3PL & 4PL) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
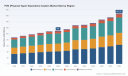
PVD Coaters Market 2026: Strategic Preview for Executive Decision-Making
Market snapshot — what the numbers tell senior leaders
Physical Vapor Deposition (PVD) coaters remain a compact but strategically important industrial equipment market. Between 2020 and 2025 the global market expanded from approximately USD 88.1 Million to USD 110.0 Million (base year 2025). Under the forecast window (2026–2032) PW Consulting projects a steady recovery and structural growth, with the market advancing to roughly USD 167.75 Million by 2032 at a compound annual growth rate (CAGR) of about 6.2%.
PVD (Physical Vapor Deposition) Coaters Market
These macro figures mask important inflection points that will determine winners and losers in 2026: accelerating regulatory pressure on wet and chrome-based finishes, rising adoption of PVD alternatives in high-value manufacturing, and a supply-chain realignment for specialty target materials. This preview explains why those dynamics matter for your 2026 strategy while intentionally withholding the granular segment-by-segment tables — our full report provides the detailed splits executives use to model capex, procurement, and M&A decisions.
PVD (Physical Vapor Deposition) Coaters Market
Why this research matters for 2026 enterprise decisions
- Capex prioritization — Purchasing teams and plant managers need to time equipment acquisition against both regulatory deadlines and vendor delivery lead times. The market’s mid-single-digit CAGR and 2026 regulatory milestones create a narrow window to secure preferred configurations and service contracts.
- Product roadmap alignment — OEMs supplying components or finished products that rely on PVD coatings must align materials and design roadmaps to coating availability constraints and evolving environmental compliance requirements.
- M&A and partnership timing — Fragmentation trends and pockets of consolidation create tactical opportunities for acquiring technology, accessing regional service networks, or securing consumables. Our market concentration analysis shows a moderate top-tier share that leaves room for strategic bolt-ons and regional roll-ups.
- Supply chain risk mitigation — Specialty sputtering target materials have concentrated sources. Procurement teams must incorporate alternative sourcing, strategic inventory, and recycling options into 2026 budgets ahead of potential disruptions or tariff shifts.
Practical contents of the full PW Consulting report (high-level)
Clients use this study as an operational playbook rather than a theoretical overview. The full deliverable includes:
PVD (Physical Vapor Deposition) Coaters Market
- Verified market sizing (historical 2020–2025 and base-year 2025) and a granular forecast (2026–2032) with scenario outputs for demand shocks and technology substitution.
- Segment-level demand models by type, application and region plus sensitivity levers for material pricing, capex deferral, and regulatory tightening (note: detailed segment tables and model inputs are available in the full report).
- Vendor benchmarking and product feature matrices covering reliability, throughput, energy intensity, modularity, and aftermarket economics.
- Procurement playbooks for target-material sourcing, total cost of ownership (TCO) calculators that capture energy, consumables, and compliance cost trajectories, and supplier scorecards to support RFQs.
- Regulatory impact assessment and compliance roadmaps tailored to EU and U.S. rule sets, with step-by-step actions for transitioning to zero-effluent or low-VOC process flows.
- Investment decision frameworks: capex timing templates, break-even analyses for retrofits vs. greenfield assets, and risk-adjusted IRR models for different adoption scenarios.
- Strategic M&A and partnership playbook, including prioritized target archetypes (technology innovators, regional service platforms, and consumable producers) and a due-diligence checklist focused on process reproducibility and target-material contracts.
Competitive landscape — patterns and strategic takeaways
The PVD equipment vendor space is characterized by a mix of specialized engineering houses, industrial platform providers, and a growing number of modular-system vendors. The market concentration metrics show that the top three firms account for roughly one-third of the market, while the top five firms approach about half — a structure that supports both organic differentiation and targeted consolidation.
- VaporTech (Longmont, Colorado) — Recognized for advanced PVD and PECVD/DLC platforms, VaporTech competes on systems that balance throughput with flexible chamber architectures. For industrial users, their V.MAX and VTi series demonstrate how modularity shortens time-to-production for specialty runs.
- PVD Products, Inc. (Wilmington, Massachusetts) — A precision-deposition specialist whose portfolio includes magnetron sputtering, pulsed laser deposition, and thermal evaporation. They are a frequent partner for R&D-to-production scale-up projects where process reproducibility and tight film properties are gating features.
- Vergason Technology (Van Etten, New York) — Following its integration into a broader tribology portfolio, Vergason strengthens offerings around wear-resistant PVD and vacuum metalizing, combining product breadth with aftermarket services relevant to tooling and industrial components.
- Hauzer Techno Coating (Venlo, Netherlands) — Known for modular batch and inline platforms optimized for both decorative and low-friction functional coatings. Their recent investments in digital configuration tools signal a push toward commercializing a service-led model for remote commissioning and lifecycle support.
- Oerlikon Balzers Coating AG (Pfäffikon, Switzerland) — A high-performance systems supplier with platform portfolios positioned for tool, automotive and high-volume decorative segments. Their strength lies in scale, service networks, and cross-selling coatings know-how to equipment customers.
Strategic takeaway: 2026 favors vendors that combine robust process performance (yield, repeatability), sustainable process footprints (low effluent/VOC), and business models that monetize uptime — service, consumables, and digital support. Buyers should evaluate vendors on integrated TCO, not just upfront capex.
Recent vendor developments that shift the competitive calculus
- Hauzer’s platform investments and its "digital configuration" launch point to faster quote-to-order cycles and reduced commissioning risk for complex specs — a material commercial advantage when lead times matter.
- Consolidation moves — exemplified by the acquisition of a U.S. vacuum metalizing specialist by an industrial group — reconfigure access to aftermarket revenue and cross-sell channels for tribology and surface-engineering solutions.
- Across the vendor set, product updates and trade-show participation in 2026 indicate an emphasis on systems that reduce effluent, support alternative target materials, and integrate monitoring dashboards — all attributes buyers should prioritize in procurement language.
Near-term forces and risks that will shape actionable strategy in 2026
- Raw material concentration — Key sputtering target metals (including some rare or strategically sensitive elements) exhibit geographically concentrated supply chains. Procurement teams must model price and availability shocks and consider multi-source or recycling strategies.
- Regulatory acceleration — New regulatory developments (including tighter VOC limits and phase-outs of certain chromium chemistries) accelerate the shift to PVD and zero-effluent systems. Corporate compliance calendars must be synchronized with capital planning to avoid forced retrofits under compressed timelines.
- Technology substitution — In some high-value applications, PVD is displacing older wet chemistries; this is most visible where device yield or environmental restrictions create economic pressure to change process architecture. Firms should quantify switching costs and time-to-qualified production.
- Service and consumables as differentiation — As equipment capabilities converge, aftermarket service contracts, spare-part availability, and consumable supply-security become decisive purchasing criteria.
Strategic playbook — prioritized executive actions for 2026
- Run a 12–18 month procurement window analysis linking regulatory milestones to vendor lead times; favor suppliers with digital commissioning and remote diagnostics to shorten ramp-up.
- Reassess supplier contracts for strategic target materials and insulate critical production lines with dual-sourcing and inventory buffers that are sized by scenario stress tests.
- Expand capital evaluation to include environmental compliance savings (lower effluent handling, avoided remediation costs) and product yield improvements — use our TCO templates to capture these levers quantitatively.
- Pursue bolt-on acquisitions or partnerships focused on aftermarket services, consumable supply, or digital lifecycle platforms rather than only on new system-builds.
- Institute a cross-functional steering committee (engineering, procurement, sustainability, regulatory) to govern PVD transitions and to accelerate technology pilots from lab to production within defined KPIs.
Closing — how PW Consulting can accelerate your 2026 moves
This executive preview draws on our proprietary market sizing and competitive workstreams to highlight where 2026 decisions will generate disproportionate value. The market’s steady growth to 2032 at a roughly 6.2% CAGR signals durable demand, but the strategic gradients — regulation, supplier concentration, and service models — create critical near-term inflection points.
PW Consulting’s full PVD Coaters Market report contains the data tables, regional and application splits, vendor scorecards, and executable templates that manufacturing executives and investors use to finalize 2026 budgets and M&A playbooks. For access to the detailed segmentation, supplier-by-supplier benchmarking, and the downloadable TCO models, please consult the full report and our advisory team to translate the insights above into a prioritized implementation plan.
For detailed analysis of this topic, please visit the official page: PVD (Physical Vapor Deposition) Coaters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting — A2P SMS Market: From USD 71.5B (2025) to USD 96.0B by 2032 at 4.5% CAGR
By pmarketresearch, 2026-07-30
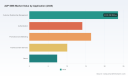
A2P SMS Market 2026: A Strategic Preview for Enterprise Decision-Makers
As organizations finalize budgets and channel strategies for 2026, A2P (application-to-person) SMS remains a cornerstone of digital customer engagement and authentication. PW Consulting’s latest A2P SMS Market study — with base year 2025 and a forward-looking forecast through 2032 — offers the empirical foundation that executives need to shape resilient, compliant, and cost-effective messaging strategies. This preview highlights the research’s strategic value, synthesizes market dynamics, and surfaces actionable priorities that will matter most in 2026, while preserving the full, proprietary segment-level intelligence for the complete report.
A2P SMS Market
Market Trajectory: What the Macro Numbers Tell Us
The A2P SMS market has demonstrated steady expansion through the early 2020s. Our model shows a notable increase in global revenue from the beginning of the decade into the 2025 base year, and a continuation of growth across the forecast window. PW Consulting’s scenario modelling projects growth consistent with a mid-single-digit compound annual growth rate (CAGR) through 2032, reflecting a balance between legacy SMS demand (authentication, alerts) and evolving channel migration toward richer messaging formats over time.
A2P SMS Market
- Market momentum: The industry’s trajectory reflects sustained enterprise reliance on SMS for high-assurance use cases (e.g., OTPs, transactional notifications) even as omnichannel strategies diversify.
- Forecast durability: A forecast CAGR of approximately 4.5% to 2032 underpins our baseline scenario, with upside and downside sensitivities driven by regulatory shifts, operator commercialization of RCS, and enterprise migration rates to rich channels.
- Concentration metrics: The sector shows measurable concentration — our CR3 and CR5 estimates indicate that a relatively small set of global providers control a meaningful share of A2P volume and revenue, shaping routing dynamics and commercial bargaining power.
Why This Study Matters for 2026 Decisions
Enterprises face three intersecting pressures in 2026: heightened regulatory scrutiny, evolving operator economics, and the need to modernize customer engagement stacks without disrupting mission-critical flows. PW Consulting’s research equips decision-makers to act on each pressure with precision:
A2P SMS Market
- Regulatory compliance is no longer optional: Mandatory registration regimes and operator-enforced blocking have increased the operational risk of legacy approaches to A2P messaging. Our analysis translates regulatory timelines and enforcement practices into a pragmatic compliance roadmap for enterprises and their vendors.
- Cost and performance optimization: With wholesale and termination pricing under review in several markets, buyers must balance unit costs with deliverability and latency. The report provides an evidence-based framework for assessing total cost of ownership across multi-vendor routing strategies.
- Channel strategy orchestration: While SMS remains indispensable for certain transactional flows, the right mix of SMS, RCS, push channels, and voice differs by use case and geography. We show how to prioritize migrations that preserve security and conversion while capturing efficiency gains.
Key Market Dynamics and Implications
The next 12–24 months will be shaped by a handful of observable trends that are already influencing vendor behaviour and enterprise procurement.
- Regulatory tightening and carrier commitments: Several national regulators and large operator groups have introduced voluntary commitments, proposed price caps, and mandatory registration programs. These measures reduce commercial uncertainty in some corridors but raise compliance and administrative demands for enterprises — particularly those using multi-country short codes, toll-free messaging, or 10DLC-type arrangements.
- Operator-led infrastructure moves: Investments in fiberization and operator-grade A2P platforms signal that some national carriers are positioning to capture more enterprise value. Where operators control delivery and routing, enterprises will need to adapt contracts and testing regimes to maintain throughput and service-level guarantees.
- Vendor consolidation and concentration: The market shows notable concentration among a handful of global CPaaS and messaging platform providers. This dynamic creates bargaining leverage for large suppliers but also opportunities for nimble regional specialists to win by optimizing local termination and compliance.
- Product differentiation: Vendors are layering analytics, delivery assurance, omnichannel integration (SMS + RCS + chat), and compliance tooling to escape commoditization. Enterprises should evaluate vendors across these dimensions rather than on headline price alone.
Competitive Landscape: How Leading Providers Are Positioning
Our competitive review profiles the strategic positioning of global and regional A2P players. The following summaries reflect each provider’s primary market strengths and the strategic questions buyers should ask during vendor selection.
- Twilio, Inc.: Known for programmable messaging APIs that support high-volume A2P use cases, Twilio’s global carrier partnerships and developer-centric platform make it a default choice for firms prioritizing speed-to-market and API flexibility. Evaluate real-world SLA performance, regional termination economics, and managed compliance support when assessing fit.
- Sinch AB: Sinch’s emphasis on omnichannel integration and direct operator relationships in several regions positions it well for enterprises seeking consolidated messaging footprints. Ask about direct operator routing versus wholesale fallbacks and the vendor’s roadmap for RCS scale.
- Infobip Ltd: Infobip combines global reach with engagement tooling that supports both transactional and marketing use cases. Focus discussions on analytics fidelity, segmentation control, and campaign governance, especially where regulatory opt-in compliance is material.
- Vonage America LLC: Vonage’s API suite supports authentication and alerts with integrated voice and messaging capabilities — useful for multi-modal authentication strategies. Probe redundancy strategies and delivery telemetry for high-throughput authentication flows.
- Plivo, Inc.: Plivo offers messaging APIs and compliance-focused routing. For enterprises with complex routing needs, validate how the provider manages carrier relationships and handles regulatory registrations on behalf of customers.
- Route Mobile Ltd and regional carriers: Providers with strong footprints in Asia and emerging markets can offer favorable termination economics and localized compliance expertise. Confirm scale commitments and SLAs for cross-border campaigns.
- Tata Communications and global network operators: These players leverage network infrastructure to offer multinational reach with fiber-enhanced delivery. Evaluate contractual terms for multinational SLAs and dispute resolution.
- CM.com, Syniverse, Bandwidth, Kaleyra: Each brings specialized strengths — European omnichannel integration, advanced routing and compliance, North American carrier integrations, and analytics-driven messaging, respectively. Use vendor scorecards to match provider capabilities to priority use cases.
Recent Industry Moves — Practical Takeaways
Recent launches and regulatory milestones are already reshaping vendor and buyer behaviours:
- National operator platforms and fiberization initiatives have created new direct-delivery options that can improve reliability for enterprise traffic, but they also require contractual and technical adjustments.
- Toll-free A2P services and mandatory registration regimes have tightened the operational window for unregistered traffic in large markets — a hard stop that requires immediate remediation for non-compliant senders.
- Regulators’ voluntary commitments on termination pricing introduce temporary stability in some markets through defined time horizons; however, enterprises should plan for pricing resets at commitment expirations.
What the Full Report Contains — Practical, Actionable Assets
The full PW Consulting A2P SMS Market report is designed to be directly usable by strategy, procurement, security, and channel teams. Key deliverables include:
- Proprietary market model and forecast (2026–2032) with scenario sensitivity and upside/downside paths for regulatory and technology adoption variables.
- Use-case decision matrix that maps messaging channels to authentication, transactional, and marketing outcomes — including migration sequencing and migration ROI estimates.
- Vendor scorecards and procurement playbook, including RFP templates, evaluation checklists, contract clauses for delivery SLAs, and compliance obligations.
- Compliance and registration roadmap covering major regulatory regimes, required registrations, and operational controls to prevent blocking or filtering.
- Technical annex: deliverability best practices, monitoring KPIs, test plan templates, and integration guides for hybrid routing architectures.
- Country-by-country regulatory tracker and operator landscape briefing for prioritized markets.
Five Strategic Priorities for 2026
Enterprises should prioritize the following actions in 2026 to preserve SMS’s value while positioning for channel evolution:
- Operationalize compliance: Complete mandatory registrations, adopt doctrinal controls for consent and opt-out, and build monitoring to detect carrier-level blocks quickly.
- Diversify delivery: Implement multi-route architectures with at least one primary and one fallback provider per critical corridor to protect availability and pricing leverage.
- Measure beyond price: Evaluate vendors on deliverability, latency, fraud detection, and support for re-routing during outages — not price per message alone.
- Prioritize high-assurance flows for SMS: Keep SMS for OTPs and critical transactional alerts while testing richer channels (RCS, in-app messaging) for engagement-focused journeys.
- Embed analytics into procurement: Require vendors to provide standardized delivery and engagement metrics to enable continuous optimization and transparency.
Conclusion — The Strategic Edge in 2026
For enterprises, SMS will remain a mission-critical channel in 2026 — but success will be determined by how quickly organizations manage regulatory compliance, restructure routing and vendor relationships, and incorporate richer channel options where appropriate. PW Consulting’s A2P SMS Market study provides the quantitative foundation, competitive intelligence, and actionable toolkits that decision-makers need to execute on these imperatives.
To access the full segmentation insights, provider benchmarks, and the comprehensive implementation playbook that underpin these strategic conclusions, please visit the PW Consulting study landing page for subscribers and decision-makers. The granular data and vendor-level scoring are held in the full report to ensure you have the detailed inputs required to operationalize these recommendations inside your organization.
For detailed analysis of this topic, please visit the official page: A2P SMS Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hardware Encryption Devices Market Poised for 9.6% CAGR Through 2032
By pmarketresearch, 2026-07-30
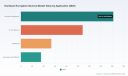
Hardware Encryption Devices Market: Strategic Briefing for 2026 Decision‑Makers
Executive preview — why this briefing matters to your 2026 agenda
As organisations accelerate digital transformation and regulatory scrutiny tightens, hardware encryption devices — from compact portable HSMs to enterprise-class modules — have moved from niche security tooling to core infrastructure. This PW Consulting briefing synthesises proprietary modelling and vendor intelligence to show where value will accrue through 2026 and beyond, and to frame the boardroom trade‑offs executives must resolve this year.
Hardware Encryption Devices Market
We adopt a “trailer” approach: this article presents high‑conviction, data‑driven insights and practical implications while intentionally withholding the granular, segment‑level tables and procurement tools that are available in the full report. Consider this an executive map: enough detail to shape policy and sourcing strategy; the full dataset and vendor scorecards are provided in the complete publication.
Hardware Encryption Devices Market
Market snapshot: trajectory, scale and concentration
PW Consulting’s baseline is 2025. Between 2020 and 2025 the market nearly doubled in scale, reflecting accelerated adoption across cloud, payments and regulated verticals. Our bottom‑up model establishes 2025 as the base year and projects the market forward through 2032 under multiple scenarios.
Hardware Encryption Devices Market
- The market exhibits structural momentum: our central forecast implies a mid‑single digit to low‑double digit compound expansion in the 2026–2032 window, driven by compliance refresh cycles, cloud migration of cryptographic workloads, and early enterprise investment in post‑quantum readiness.
- Under the central scenario the market grows at a compound annual rate of approximately 9.6% through the forecast window, more than offsetting near‑term supply adjustments and providing durable tailwinds for vendors that align product roadmaps with regulatory and cloud operator needs.
- Concentration is material: the top three vendors account for roughly two‑thirds of market revenue, and the top five represent over eighty percent. This structure creates clear leader advantages on scale, validation effort and ecosystem integration, while leaving pockets of opportunity for specialised challengers.
Industry dynamics shaping 2026 buying decisions
Four converging forces will dominate procurement and architecture decisions in 2026:
- Regulatory tightening. U.S. federal standards now require higher FIPS validation baselines for cryptographic modules, and industry‑specific standards (notably payments) have updated device requirements. These deadlines force a short, predictable vendor rationalisation and create a bifurcation between validated incumbents and those still on the compliance ladder.
- Standards and certification activity. New versions of payment‑centric HSM requirements and Common Criteria certifications in key jurisdictions have altered the compliance map. Organisations with cross‑border operations must overlay multiple certification requirements into a single procurement specification.
- Post‑quantum transition. Vendors are shipping post‑quantum algorithm support in firmware and appliance form factors; but readiness is uneven. The practical impact for 2026 is not immediate replacement but staged capability adoption tied to key lifecycle events (certificate renewals, PKI migration windows, cloud contract renewals).
- Infrastructure acceleration. Policy and permitting actions that speed data‑centre and edge deployments reduce lead times for appliance deployment and increase the value of scalable, multi‑tenant HSM platforms that can be deployed in hybrid environments.
Competitive landscape: who matters and why
The market is led by a group of established security vendors and a handful of specialised challengers. Our competitor analysis focuses on product differentiation, certification posture, cloud interoperability and commercial models.
- Thales Group (France) — Thales’ Luna series spans network, PCIe, USB and cloud‑native HSMs. Their roadmap emphasises validated modules, comprehensive key lifecycle tooling and an early, standardised approach to post‑quantum algorithms. Thales continues to prioritise enterprise and regulated use cases.
- Entrust Corporation (United States) — Entrust’s nShield family targets enterprise deployments with appliance and cloud options. Their focus on certified toolkits, developer SDKs and managed cryptographic services keeps them competitive in large corporate and government deals.
- Utimaco GmbH (Germany) — Utimaco positions its u.trust and CryptoServer lines as high‑assurance, multi‑tenant platforms with a strong emphasis on physical tamper resistance and compliance. Their recent product introductions and validation achievements make them a go‑to for the most demanding regulatory environments.
- Yubico (United States) — Yubico’s compact HSM offerings are designed for developer and edge scenarios where form factor and simplicity matter. They are an option where integration speed and portability trump scale.
- Futurex (United States) — Futurex provides enterprise HSMs and centralized key management with focus on payment and POS ecosystems and on integration with legacy estates.
- IBM Corporation (United States) — IBM brings quantum‑safe HSM solutions that blend classical cryptographic support with early post‑quantum algorithms, aimed at customers pursuing an explicit quantum migration roadmap.
- Atos SE (France) — Atos delivers secure HSM solutions focused on data protection and high assurance mission profiles, often bundled with broader data security services.
- Securosys SA (Switzerland) — Securosys offers Primus HSMs and cloud HSM services with attention to post‑quantum readiness and developer ergonomics for cloud operators and MSPs.
Recent vendor developments reinforce the competitive shape: multi‑tenant high‑assurance product launches, firmware releases standardising post‑quantum implementations, and ongoing updates to payment HSM requirements. Together these moves compress the window for evaluation and procurement in 2026.
What our full report contains — practical tools for 2026 execution
The full PW Consulting Hardware Encryption Devices Market study is built for practitioners and includes the following operational deliverables (summarised):
- Proprietary market model with historical reconciliation (2020–2025) and scenario forecasts to 2032, including sensitivity runs tied to regulatory and cloud adoption levers.
- Vendor scorecards assessing certifications, performance profiles, management ecosystems, cloud marketplace footprints and support models — designed to accelerate vendor short‑listing.
- Procurement playbooks and an RFP template keyed to multi‑jurisdiction compliance, performance SLAs and lifecycle migration clauses.
- Deployment blueprints for common migration paths (on‑prem to cloud HSM, appliance upgrade cycles, hybrid cryptographic fabrics), with sample timelines and cost buckets for CapEx/Opex trade‑offs.
- TCO and risk matrices that map certification gaps to remediation costs and implementation time — enabling procurement teams to stress‑test vendor proposals against compliance deadlines.
- Scenario planning and M&A briefing notes identifying consolidation vectors and potential targets for strategic buyers or partnerships.
We intentionally do not disclose granular segment splits or unit prices here: those model rows and downloadable templates are part of the complete report package designed to support procurement and security teams through RFP and integration phases.
Strategic implications for 2026 decision cycles
Based on our analysis, boards and CISOs should prioritise four near‑term decisions this year:
- Certification first: embed certification timelines (FIPS, PCI, Common Criteria) in all procurement and renewal decisions. For many buyers, a validated baseline by the end of 2026 materially reduces compliance risk and total cost of ownership over a three‑ to five‑year window.
- Adopt a hybrid posture: a mixed on‑prem and cloud HSM architecture balances regulatory constraints with operational agility. Shortlist vendors that provide validated cloud HSM offerings plus consistent tooling for key lifecycle management.
- Plan for quantum migration now, execute later: inventory cryptographic dependencies, prioritise critical assets for early post‑quantum protection, and align certificate renewal windows to minimise re‑encryption events.
- Vendor and ecosystem strategy: weigh the benefits of consolidation against the lock‑in risks of single‑vendor stacks. Given the market concentration dynamics, strategic partnerships or multi‑vendor strategies can preserve negotiating leverage while ensuring redundancy for high‑value keys.
Actionable next steps for 90‑day and 12‑month horizons
- 90 days: complete a validated inventory of HSM dependencies and certificate lifecycles; issue an RFP using our template to close gaps with at least two validated vendors.
- 6–12 months: finalise procurement with contractual certification commitments and migration milestones aligned to regulatory deadlines; pilot post‑quantum integrations in non‑production PKI streams.
- 12 months+: transition to an operational model that integrates HSM metrics into security KPIs and procurement scorecards, and evaluate consolidation or strategic partnership opportunities identified by the scenario analysis.
Conclusion — what to expect in 2026 and where PW Consulting adds value
Hardware encryption devices will remain a critical control point for enterprise security, regulated data protection and payments infrastructure through 2026 and beyond. The market’s projected trajectory and the evolving compliance landscape create windows of opportunity for disciplined buyers and well‑prepared vendors. PW Consulting’s full report provides the calibrated datasets, vendor evaluations and procurement tooling needed to turn that window into sustained advantage.
To access the complete market model, vendor scorecards, practical playbooks and downloadable RFP templates, please consult PW Consulting’s Hardware Encryption Devices Market report. The full package contains the granular segmentation analyses and supporting spreadsheets that operational teams require to execute with confidence.
For detailed analysis of this topic, please visit the official page: Hardware Encryption Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: ITSM Software Market Poised for 16.45% CAGR Through 2032
By pmarketresearch, 2026-07-23
IT Service Management (ITSM) Software Market — Strategic Outlook for 2026
Executive summary
As enterprises move from episodic digitization to continuous digital operations, IT Service Management (ITSM) has shifted from a ticketing tool to an operational nervous system. PW Consulting’s latest ITSM Software Market research establishes a clear, data-driven foundation for strategic choices in 2026. The sector is on a steep trajectory — growing from a 2025 baseline and projected to expand at a compound annual growth rate (CAGR) of 16.45% through the 2026–2032 forecast window — with the global market approaching roughly USD 624 million by 2032. This growth is being driven by the convergence of AI-led automation, multi-cloud operations, and an urgent enterprise need to operationalize compliance and privacy at scale.
IT Service Management (ITSM) Software Market
Why this research matters for 2026 decision-makers
- Investment timing: With the market accelerating quickly, 2026 is a pivot year for CAPEX vs OPEX choices. The CAGR implies significant supplier innovation and pricing pressure; early adopters of AI-first ITSM can capture outsized operational savings, while late movers risk higher migration costs and displacement.
- Vendor selection and lock-in risk: The market is meaningfully concentrated — the leading vendors capture a majority of spend — which raises strategic supplier risk considerations for large enterprises. Choosing a platform today affects integration budgets, data residency choices, and multi-year service models.
- Operational transformation: ITSM platforms are becoming execution engines for autonomous work. Decisions taken in 2026 will determine whether organizations reap the promised labor efficiencies (ticket deflection and faster mean-time-to-resolution) or inherit brittle automation that amplifies governance risk.
Market trajectory and what the headline numbers mean
Our report uses a 2025 base year and a comprehensive historical window (2020–2025) to project the sector to 2032. The headline CAGR of 16.45% is not abstract — it reflects rapid re-platforming to cloud-native architectures, premiuming for AI-enabled capabilities, and expanding use cases beyond classical incident and asset management. Practically, organizations should expect escalating vendor feature churn, more aggressive bundled AI pricing, and richer ecosystem tie‑ins with observability, ITOM, and HR/service productivity stacks.
IT Service Management (ITSM) Software Market
For executives, the key takeaway is dual: the market’s unit economy and feature set are evolving quickly enough that procurement cycles shortened in 2024–25 will look out of date by 2027; and the total addressable value for ITSM-related operational savings (labor, incident costs, business downtime) materially grows as platforms automate higher-value workflows.
IT Service Management (ITSM) Software Market
Dynamics shaping the market
- AI-driven labor economics: Industry benchmarking shows AI-enabled ITSM capabilities can deliver 30–60% ticket deflection and 40–90% faster resolution on routine workloads. These efficiencies are reshaping staffing models for centralized and distributed IT teams and creating new ROI profiles for platform investments.
- Data privacy and compliance burden: Enterprises report a sharp rise in data subject requests and regulatory oversight, which elevates demand for ITSM platforms that embed audit trails, consent handling, and automated subject-request workflows. Compliance is now a functional requirement, not an optional bolt-on.
- Cloud and hybrid infrastructure pressures: As operations span multiple clouds and edge environments, buyers prioritize solutions that provide real-time service visibility, SLA assurance, and cross-domain automation. Cloud-first offerings are increasingly the default for large-scale deployments.
- Standards and governance: Adoption of ITIL v4 and ISO-aligned processes remains high; however, vendors are racing to reconcile these frameworks with autonomous workflows, necessitating governance layers (AI control towers, explainability, verified playbooks) to pass audit and compliance gates.
- Pricing divergence: The market exhibits bifurcated pricing dynamics — competitive mid-market offers lower entry points, while enterprise-grade, AI-enabled suites command substantially higher per-agent economics. This divergence complicates TCO modeling for heterogeneous estates.
Segmentation — what to watch (without the raw splits)
The market is commonly segmented by deployment model (cloud vs on-prem), functional modules (incident, configuration, asset, change, and others), and geography. In this preview we intentionally do not disclose the detailed split statistics — the full report contains the complete segmentation tables and forward-looking share scenarios. For strategic planning, the critical insight is not merely which segment is largest today, but which combinations of deployment model, functionality, and procurement model create sustainable advantage for your organization by 2028.
Competitive landscape — leaders, challengers, and strategic moves
The vendor landscape combines global platform leaders, specialized challengers, and systems integrators delivering verticalized solutions. Market concentration metrics indicate that top-tier vendors hold a commanding position, while a larger set of mid-market and niche vendors compete on speed, verticalization, and cost.
- ServiceNow: As a platform leader, ServiceNow continues to push enterprise-grade autonomy with initiatives introduced in early 2026 (Autonomous Workforce, EmployeeWorks, and the Otto unified AI experience). These moves accelerate the convergence of conversational AI, governed workflows, and cross-domain automation — creating both opportunity and lock-in for large enterprises that can invest in deep platform integrations.
- BMC: BMC’s Helix line emphasizes proactive, AI-enabled operations across complex, multi-cloud estates. Their focus on change management and operational resiliency appeals to regulated industries.
- Atlassian (Jira Service Management): Positioned strongly with developer-centric ops and DevOps toolchain integration, recent feature updates reinforce its pull for engineering-led service models and agile incident response.
- Ivanti: Ivanti’s recent release of agentic conversational AI capabilities and modern UX enhances its competitive posture for organizations prioritizing rapid automation adoption and modern user experiences.
- Freshworks, ManageEngine, Microsoft, Broadcom, and others: Each vendor pursues differentiated routes — mid-market speed, unified workplace integrations, or deep ITOM tie-ins. Partnerships and OEM relationships (for example, enterprise deployments powered by third-party platforms) are recurring themes.
Recent product launches and feature cycles are more consequential than in prior periods — they materially change integration scopes and operational playbooks. The report annotates these developments with practical implications for procurement, architecture, and migration sequencing.
What’s inside the full PW Consulting report (practical contents, not just high-level commentary)
- Actionable vendor selection frameworks that map business objectives (cost reduction, customer experience, compliance) to platform capabilities and sourcing models.
- Implementation playbooks and phased migration templates for re-platforming from legacy or on-prem stacks to cloud-native, AI-enabled ITSM, including change-management checklists to protect service continuity.
- TCO and ROI models that incorporate labor deflection, incident-cost avoidance, and automation uplift — configurable for industry and estate complexity.
- Governance design for AI in ITSM: control towers, audit trails, model validation checkpoints, and escalation matrices to ensure autonomous workflows remain auditable and compliant.
- Negotiation levers and contract playbooks that reflect current pricing dynamics and bundling practices, with templates for SLAs and exit strategies to limit vendor lock-in.
- Vendor profiles and scenario-based vendor shortlists tailored for enterprise size, industry regulation, and cloud footprint.
Strategic recommendations for 2026
- Prioritize governance early: If you plan to adopt autonomous capabilities, implement an AI control tower and audit-ready process definitions before scaling automation.
- Design for composability: Favor platforms that expose robust APIs, support hybrid integration fabrics, and avoid deep proprietary extensions that impede portability.
- Adopt a phased value-first approach: Start with high-frequency, low-risk workflows to capture labor savings quickly, then reinvest realized savings into broader, higher-risk automations.
- Reconsider labor models: Use conservative scenarios in workforce planning that account for substantial ticket deflection and faster resolution times observed in early AI adopters.
- Embed compliance as a product requirement: Procurement must include privacy and data-subject-request capability as mandatory evaluation criteria, not optional features.
Use the report as your operational blueprint — and why you’ll need the full data
This article previews the strategic implications and high-level numbers that should shape your 2026 decisions. However, actionable vendor shortlists, segmented market forecasts, pricing band matrices, and implementation templates are deliberately excluded here to preserve the “trailer” intent: to demonstrate analytical depth while guiding buyers to the full research. The full PW Consulting report contains the granular segmentation, scenario models, and downloadable artifacts necessary to execute vendor selection and migration with confidence.
Next steps
For CISOs, CIOs, procurement leads, and transformation sponsors preparing 2026 budgets and roadmaps, the immediate priority is to validate whether your current ITSM architecture and vendor agreements can support an AI-first, multi-cloud operating model. Use this briefing to align your leadership on the horizon and then consult the full PW Consulting ITSM Software Market report for the detailed breakouts, playbooks, and vendor-by-vendor analysis required to operationalize your strategy.
For detailed analysis of this topic, please visit the official page: IT Service Management (ITSM) Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Blood Bank Information Systems Market USD 947M in 2025, 7.8% CAGR
By pmarketresearch, 2026-07-23
Blood Bank Information Systems Market — Strategic Briefing for 2026 Decision-Makers
Executive summary
As healthcare organizations confront increasingly stringent traceability and safety requirements, the Blood Bank Information Systems (BBIS) market has moved from niche operational tooling to a strategic infrastructure layer. Our market model, calibrated to a 2025 base year and spanning historical performance (2020–2025) with a forward-looking forecast to 2032, shows a sustained expansion at a compound annual growth rate (CAGR) of 7.8%. The market that approached the billion-dollar threshold in 2025 is projected to exceed USD 1.5 billion by 2032 (figures in USD Million). This trajectory is driven by regulatory imperatives, digitization of transfusion workflows, and cloud-first deployment economics.
Blood Bank Information Systems Market
Why this matters for 2026 strategic planning
For hospital systems, national blood services, ISVs and investors planning actions in 2026, BBIS decisions are no longer confined to feature checklists. They intersect with enterprise architecture, compliance risk, and supply-chain resiliency. The 2026 planning cycle will determine which organizations lock in legacy constraints and which adopt more flexible, audit-ready platforms capable of supporting multi-site operations, donor-to-recipient traceability, and analytics-driven inventory optimization.
Blood Bank Information Systems Market
Key market trajectory — high-level numbers
-
Historical expansion: The market grew steadily from the 2020 baseline through 2025, reflecting accelerating adoption and replacement cycles among blood banks and transfusion services.
Blood Bank Information Systems Market -
Near-term inflection: 2026 marks the start of the forecast horizon in our study. The market crosses the billion-dollar mark in the immediate year and continues an upward path through 2032, reflecting compounding investments in compliance, digital workflows and cloud migration.
-
Long-term opportunity: By 2032 the market size is projected to be materially larger than the 2025 base, underscoring durable demand for integrated BBIS capabilities across healthcare ecosystems.
Report scope — what the study delivers
This research is designed as an operationally actionable guide for executives and program owners. Highlights include:
-
Validated market sizing (2020–2025 historical; 2026–2032 forecast) expressed in USD Million, with scenario sensitivity to regulatory and technology adoption variables.
-
A pragmatic vendor evaluation framework that scores solutions across safety/traceability, interoperability, deployment architecture (on-premise vs cloud), and total cost of ownership (TCO) over 5–7 year horizons.
-
Decision-ready playbooks for procurement teams: RFP templates, risk-adjusted cost models, migration timelines, and success metrics for phased rollouts in multi-facility environments.
-
Integration blueprints for EHR/LIS connectivity and point-of-care allocation, plus recommended KPIs to monitor compliance, utilization and product shelf-life optimization.
-
Scenario analyses for strategic options: in-house modernization, vendor consolidation, managed services, and M&A targets — each with quantified impacts on operational KPIs and compliance risk.
Market dynamics and regulatory drivers
The BBIS market is being reshaped by policy and clinical safety requirements as much as by technology. Two regulatory trends are particularly material in 2026 planning:
-
Traceability mandates: Regulatory agencies now require full donor-to-recipient traceability and audit-ready records. Systems must provide end-to-end documentation that can withstand regulatory scrutiny without creating significant manual workarounds.
-
Real-time auditability: In several jurisdictions, legislators and regulators expect electronic, real-time audit trails as part of Substances of Human Origin (SoHO) compliance frameworks. That raises the bar for data model design, retention policies, and incident response workflows.
Operationally, survey and industry data indicate that regulatory compliance is the primary driver for BBIS upgrades across blood centers — a factor cited by a substantial majority of centers as the leading justification for investment. At the same time, cloud deployments continue to reshape cost structures: they reduce upfront capital expenditure and permit elastic scaling of inventory and traceability services, enabling more sophisticated workflows without commensurate hardware investments.
Competitive landscape — who sets the standard
The vendor environment balances specialized BBIS providers, broader healthcare IT platforms, and niche modules. Market concentration remains modest: the top three and top five firms together account for under half of the market, indicating room for both consolidation and regional specialization. That concentration profile drives specific strategic choices for buyers and investors:
-
Specialist vendors combine deep blood-bank provenance with modular suites tailored to transfusion workflows. Examples include longstanding players whose solutions emphasize inventory control, point-of-care allocation and traceability.
-
Larger healthcare IT platforms embed BBIS functionality within broader EHRs and enterprise suites — attractive to integrated delivery networks seeking single-vendor stacks and tighter clinical interoperability.
-
There is a growing cohort of cloud-native and web-enabled solutions that prioritize rapid deployment, central management and API-first interoperability, appealing to multi-site blood services and national programs.
Representative vendor profiles (high level):
-
Haemonetics — modular suite emphasizing inventory control, traceability and safe transfusion workflows at the point of care.
-
WellSky — transfusion systems with strong EHR/LIS integration and compliance tooling; recent updates (early 2026) introduced new kit-management features focused on inventory and workflow optimization.
-
SCC Soft Computer — web-based BBIS showcased at international conferences in 2025 and 2026, reinforcing its commitment to global best practices and market education.
-
Mediware Information Systems — modular transfusion service management with compliance-centered features and integration capabilities.
-
Cerner (as part of large EHR platforms) — embedded blood bank workflows within broader electronic health record solutions, enabling tighter clinical-process integration.
Recent vendor moves and what they imply
Two tactical developments illustrate vendor positioning in 2026:
-
Feature rollouts that emphasize kit and inventory optimization signal vendors are prioritizing operational efficiency alongside safety. These features reduce waste, improve traceability and shorten turnaround times for critical transfusion decisions.
-
Trade show and conference investments reflect a push to drive global uptake and professionalize BBIS procurement. Vendors are increasingly using live demonstrations and interoperability showcases to de-risk buyer decisions.
Strategic implications and recommended actions for 2026
For enterprise leaders evaluating BBIS directions in 2026, our analysis yields a compact set of recommendations:
-
Prioritize compliance-first roadmaps: Ensure any short-listed system demonstrably meets traceability and audit-readiness requirements in your regulatory jurisdictions. Compliance gaps are the leading source of downstream cost and risk.
-
Model TCO across deployment options: Cloud architectures reduce capex but introduce operational and governance nuances. Build multi-year TCO and vendor-lock-in scenarios into procurement evaluations.
-
Insist on interoperable architectures: Integration with EHRs, laboratory information systems and point-of-care devices must be tested with realistic data and workflows before procurement commitments.
-
Use vendor scorecards and pilot outcomes to drive phased rollouts: Pilots should measure waste reduction, transfusion safety events, cycle-times, and regulatory audit readiness. Translate pilot KPIs into contract SLAs.
-
Explore consolidation or partnership where scale matters: Given the market’s current concentration profile, there are opportunities — and risks — in market consolidation. Assess whether to invest in internal capabilities, partner with a specialist, or pursue M&A to accelerate market entry.
How PW Consulting’s report supports your 2026 agenda
This study is structured to be directly executable by strategy teams:
-
Market sizing and scenario models ready for sensitivity analysis (regulatory tightening, cloud adoption rates, capital availability).
-
Vendor benchmarking tools that translate functional capabilities into procurement scorecard metrics and negotiation levers.
-
Implementation playbooks with timelines, resource plans and governance checkpoints for single-site and multi-site rollouts.
-
Regulatory mapping that aligns local requirements to system capabilities, minimizing compliance surprises during deployment and audit.
Methodology and transparency
The report uses a blended methodology: primary interviews with blood center operators and vendor product teams, a review of regulatory publications, and quantitative triangulation against historical adoption curves. The base year is 2025, historical tracking covers 2020–2025, and forecasts extend 2026–2032 in USD Million. The model is openly documented so decision teams can re-run scenarios with internal assumptions.
Final note — a teaser, not the full map
We have intentionally framed this briefing to reveal the market direction, regulatory imperatives, vendor positioning and the practical levers available to 2026 planners — while withholding the granular regional, application and type-specific breakdowns that are critical to detailed procurement and investment decisions. Those granular splits, vendor-specific scorecards and downloadable executable models are included in the full PW Consulting report and accompanying data pack.
For teams that must convert 2026 strategy into executable programs — from procurement and integration to M&A and product roadmap prioritization — the full report provides the datasets, vendor evaluations and playbooks needed to move from decision to delivery. Contact PW Consulting or visit our report page to access the complete analysis, model files and procurement templates.
For detailed analysis of this topic, please visit the official page: Blood Bank Information Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com