

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Near-IR Camera Market to Reach USD 232.91M by 2032 at 7.3% CAGR — PW Consulting

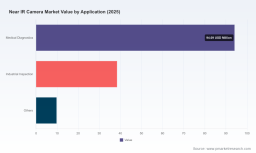
Near IR Camera Market: Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Industry Analyst, I present a concise—yet strategically rich—preview of our full Near Infrared (NIR) Camera Market research suite. This briefing synthesizes the market dynamics, competitive posture, risk vectors, and actionable decision frameworks that matter most for capital allocation, product roadmaps, and M&A activity in 2026. The analysis is grounded in a market model with a 2025 base year (USD, Million), a historical window from 2020–2025 and a forecast horizon through 2032 at a compound annual growth rate (CAGR) of 7.3%—illustrating a clear, multi-year expansion from the 2025 base toward the 2032 outlook.
Near IR Camera Market
Why this research matters for 2026 strategic choices
- Timing and scale: With the market expanding at a steady mid-single-digit CAGR, 2026 is a juncture where investment decisions either accelerate platform-scale plays (supply chain, high-volume optics/packaging) or prioritize niche, high-margin product differentiation (cooled sensors, extended-SWIR).
- Technology inflection: Innovations in sensor materials and cooling (including extended SWIR sensor architectures and compact Stirling solutions) are shifting performance-cost trade-offs. Firms that align product roadmaps to the emerging technical envelope will lock in lead positions for the next product cycle.
- Commercial leverage: Buyers across medical diagnostics, industrial inspection, defense, and telecom increasingly expect not only imaging performance but validated systems-level compliance (functional safety, environmental ruggedization, and regulatory certifications). Vendors that can combine component supply with system validation win larger integrated deals.
- M&A and partnerships: Fragmented supplier economics and specialized IP pockets create high potential for bolt-on acquisitions and strategic alliances—especially for players seeking to accelerate time-to-market for SWIR-enabled systems.
High-level market trajectory (selected view)
- Base year context: The market model uses 2025 as the reference point, capturing the cumulative evolution across 2020–2025 and setting the stage for scenario planning in 2026.
- Growth direction: Under our central-case assumptions the market continues its steady growth through 2032, reflecting broader adoption across medical, industrial, and defense segments as well as incremental adoption in telecom and automotive niches.
- Implication: The growth profile supports both scale and specialization strategies—investors should choose based on margin target, time-to-payback, and exposure tolerance to supply-chain cycles.
Key demand and technology dynamics
- Sensor economics and architecture: The dichotomy between silicon-based designs and InGaAs (and emerging extended-SWIR) approaches defines product positioning—each presents different cost structures, cooling needs, and performance envelopes (sensitivity, spectral range, speed).
- Systemization over components: Customers increasingly value turnkey modules—camera cores plus validated optics, software stacks, and certification artifacts—over chip-only wins. This favors vertically integrated suppliers and OEM partners able to deliver system-level value.
- Application pull: Medical diagnostics (non-invasive imaging and spectral tissue assessment), high-speed industrial inspection, telecom test & measurement, and surveillance/defense each generate distinct performance and compliance requirements that shape procurement cycles and vendor selection.
- Regulatory and standards momentum: Functional safety requirements for automotive integrations and MilSpec/industrial ruggedization for defense and aerospace exert a gating effect on addressable opportunities. Vendors with documented standards compliance obtain faster qualification windows.
Competitive landscape—who matters and why
The market remains commercially fragmented: leading suppliers deliver differentiated IP (sensor design, cooling, core modules) while a wider set of specialists fills niche needs. Our competitive mapping places emphasis on product architecture, go-to-market routes (OEM vs system integrator), and certification footprints.
Near IR Camera Market
- Hamamatsu Photonics K.K. (Japan) : Renowned for InGaAs cameras across area and line-scan formats. Strengths lie in sensor quality, scientific-grade reliability, and broad wavelength coverage—positioned for lab, medical, and high-precision industrial roles.
- Xenics / Exosens (Belgium) : Specialist SWIR provider focused on InGaAs cores and cameras for machine vision and defense. Competitive edge in customized detector cores and modular integration for machine-vision OEMs.
- Teledyne FLIR OEM (United States) : Large OEM channel presence and recent product extensions targeted at high-speed telecom and automotive functional-safety use-cases. Strong commercial reach into systems integrators and tiered partners.
- Raptor Photonics (U.K./U.S.) : Rapid product innovation in extended SWIR—recent launches demonstrate a push into higher-performance, cooled sensor modalities and scale-up of production capabilities to meet market demand.
- Sensors Unlimited (Collins Aerospace, U.S.) : Defense and aerospace-specialist SWIR supplier; emphasis on certified, rugged platforms suited to haze-penetrating imaging and airborne applications.
- Photonic Science (U.K.) : Supplier of cooled and uncooled SWIR cameras for scientific imaging—competitive where measurement fidelity and lab-grade performance are required.
- New Imaging Technologies / LYNRED (France) : Focus on high-speed, high-dynamic-range SWIR cameras for industrial inspection; investment in CAD modeling and customer co-design strengthens OEM adoption.
Recent company moves (product launches, production scaling and CAD releases) indicate accelerated investment in extended-SWIR sensor modalities and cooling subsystems; these developments materially influence 2026 supplier shortlists and capital planning.
Near IR Camera Market
Market structure and concentration
The competitive map shows a market where specialized vendors hold distinct technology advantages but no single supplier dominates. Such structure supports a mixture of procurement strategies—multi-sourcing for core detectors, single-sourcing for fully integrated, certified modules where risk transfer and lifecycle support are critical.
Risk factors and scenario sensitivities
- Supply-chain concentration: Sensor fabrication and specialized cooling subsystems are chokepoints. Procurement teams should stress-test supplier continuity and identify second-source pathways.
- Price and margin pressure: Sensor and optics cost volatility creates margin compression for lower-complexity camera models. Product teams should model ASP sensitivity and preferred-margin thresholds before committing to high-volume programs.
- Standards and certification delays: Functional-safety and defense certifications can add program timelines and cost. Early engagement with certifying bodies and co-development of test plans is necessary to avoid go-to-market slippage.
- Technology obsolescence: Rapid innovation in sensor materials and readout electronics can shorten product lifecycles; firms must balance R&D cadence with scalable manufacturing investments.
2026 Playbook — Practical actions for executives
- Prioritize portfolio clarity: Define which products will be scaled for volume and which will be high-margin, differentiated systems—align investment horizons and supply commitments accordingly.
- Secure sensor supply lines: Convert critical suppliers into strategic partners via long-term offtake agreements, co-investment in foundry capacity, or exclusive development pathways for unique sensor variants.
- Certify early, sell faster: Invest in pre-certification and qualification artifacts (safety, environmental, MilSpec) during prototype phases to shorten procurement cycles with enterprise and defense buyers.
- Adopt modular architectures: Design camera cores that can be re-used across medical, industrial, and defense SKUs to reduce time-to-market and amortize R&D across multiple revenue streams.
- M&A and partnerships: Target acquisitions that fill capability gaps—sensor readout IP, cooling subsystems, or application-specific imaging software—rather than broad, unfocused scale plays.
- Commercial rigor: Implement value-based pricing for differentiated imaging solutions and preserve margin in commodity SKUs through manufacturing efficiency and bundled services.
What the full PW Consulting report delivers (practical contents)
- Comprehensive market model (historical and forecast through 2032) with scenario levers for sensor pricing, certification timelines, and adoption curves.
- Actionable go-to-market playbooks and buyer decision matrices for medical, industrial, defense, and telecom customers.
- Technology radar comparing silicon vs InGaAs vs extended-SWIR options, including cooling trade-offs and roadmap implications.
- Supplier heatmaps, capability scorecards, and an M&A target shortlist based on integration ease and IP defensibility.
- Price-to-performance benchmarking and recommended procurement clauses to mitigate supply and warranty exposure.
- Regulatory and standards checklist tailored to automotive functional safety, aerospace/defense ruggedization, and global market entry.
- Interactive dashboard for scenario testing—align product investment with revenue and margin sensitivity in real time.
How to use this intelligence in 2026
Executives should treat the NIR camera space as a portfolio decision: preserve optionality where technology and standards are still settling, and accelerate where the pathway to certification and scale is clear. Use the full report to populate investment memos, supplier scorecards, and M&A screens with evidence-based inputs rather than intuition-driven estimates.
For leaders preparing budgets, product roadmaps, or acquisition theses in 2026, this research provides a defensible market view, validated vendor assessments, and pragmatic mitigation plans to convert growth potential into measurable returns. Accessing the full dataset and the interactive scenario models will allow your team to turn the high-level strategies outlined here into executable plans tailored to your risk appetite and time horizon.
PW Consulting’s full Near IR Camera Market report contains the granular segmentation, buyer economics, and supplier-level datasets needed to operationalize these recommendations—contact our research desk to unlock the complete analysis and interactive tools.
For detailed analysis of this topic, please visit the official page: Near IR Camera Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com