

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: IT & Electronics
PW Consulting: Gate Driver ICs for BLDC Motors Market to Grow at 8% CAGR from 2026, Reaching USD 2,825 Million by 2032
By pmarketresearch, 2026-08-18
Gate Driver ICs for BLDC Motors Market: Strategic Intelligence to Shape 2026 Decisions
PW Consulting today releases an executive preview of our in-depth market research report, Gate Driver ICs for BLDC Motors Market — Base Year 2025, Forecast 2026–2032. Designed for C-suite executives, product leaders, procurement heads, and M&A teams, this analysis translates semiconductor dynamics into concrete commercial actions for 2026. The study synthesizes supply-chain realities, technology trajectories, and competitive maneuvering to show where value pools will open and which tactical moves will preserve or expand advantage.
Temperature Assured Packaging Market
Why this report matters in 2026
The gate driver IC market for BLDC motors has entered a phase of steady expansion underpinned by electrification trends across automotive, industrial and consumer segments. Our model—with 2025 as the base year—indicates the market is growing at a compound annual growth rate (CAGR) of approximately 8.0% across the 2026–2032 forecast window. By the end of the forecast period the market is projected to materially exceed the 2025 base, reflecting scaling adoption of integrated driver architectures, higher-voltage silicon and SiC enablement, and the rising complexity of motor controls in next‑generation systems.
Enfuvirtide for Injection Market
For decision-makers in 2026, this report turns growth projections into strategic choices: where to invest in product development, which supplier risks to hedge, how to calibrate pricing and inventory strategies, and what M&A or partnership moves will strengthen position without overpaying for commoditized offerings.
AI Software Tools for Finance Market
Report scope and practical deliverables
PW Consulting’s study is intentionally operational. Beyond high‑level forecasts, the report equips clients with:
- Actionable supplier risk matrices that combine lead‑time, material concentration and regulatory exposure to identify single‑point failures and prioritise dual‑sourcing or localised inventory strategies.
- Technology adoption roadmaps mapping gate driver feature sets (isolated drivers for SiC, integrated MOSFET SmartMCDs, built‑in microcontrollers and sensorless control) to specific end‑market requirements and certification barriers (automotive/industrial functional safety).
- Decision frameworks for make vs. buy, with TCO modelling that factors in rising component pricing, extended MOSFET lead times and qualification costs for automotive-grade parts.
- A competitive playbook profiling product portfolios, go‑to‑market moves, and design‑win trajectories for the major incumbent and challenger suppliers.
- Scenario analyses that stress-test strategic plans against supply-chain shocks (export controls on critical materials, tariff changes) and component price swings—enabling board‑level contingency planning.
Competitive landscape — what to watch
The market exhibits moderate concentration: the top three suppliers account for a meaningful share of addressed revenues, while the top five increases that footprint further—indicative of a market where scale and product breadth matter, but opportunities remain for niche specialists and design‑win focused entrants.
- Infineon Technologies — Strong in automotive-grade solutions, Infineon’s MOTIX™ family and recent isolated drivers for SiC motor drives underscore a strategy centered on functional safety and high‑voltage applications. Their product positioning makes them a preferred partner for OEMs that prioritise ISO 26262 compliance.
- STMicroelectronics — With integrated families that span driver + MCU and options pushing into high‑voltage domains, ST’s approach is focused on platform plays for industrial and automotive customers seeking consolidated supplier relationships.
- Toshiba Electronic Devices & Storage — Recent SmartMCD and gate driver sampling programs indicate Toshiba is accelerating into integrated MOSFET‑plus‑driver architectures for automotive body and small motor applications; these moves lower system BOM and accelerate time‑to‑market for OEMs.
- ROHM Semiconductor — ROHM’s medium‑voltage driver launches and production ramps highlight a strong play in mid‑voltage electrification use cases, particularly where robust thermal and switching performance are required.
- Texas Instruments, Allegro, Microchip, Renesas, onsemi and Monolithic Power Systems — Each of these firms brings differentiated strengths: integrated current sensing, Hall/sensor interfaces, AEC‑qualified predrivers, and platform breadth. For system houses, supplier mosaics will increasingly blend these capabilities to meet both cost and functional targets.
Our competitive chapter not only inventories product capabilities and recent launches, but also assesses route‑to‑qualification timelines, software and toolchain maturity, and the strength of distribution and design‑support programs—elements that ultimately decide design‑win velocity.
Supply chain realities that must influence 2026 strategy
Macro and micro supply risks are central to the report’s recommendations. Notable pressures include:
- Raw material and export control exposure: Restrictions on materials critical to advanced semiconductors (e.g., gallium and germanium) have introduced a new layer of geopolitical supply fragility. Firms that rely on single‑source supply lines for these inputs face escalating strategic risk.
- Component lead times: MOSFET lead times averaged well into the 20s of weeks in early 2026, with some suppliers reaching 30+ weeks. These elongated cycles materially affect production planning for gate driver assemblies and favour earlier allocation and forward buys.
- Pricing environment: Several semiconductor suppliers announced price increases in the spring of 2026. Procurement organisations must balance margin protection with end‑market price sensitivity, and consider hedging and contract structures that share risk between OEMs and supplier partners.
- Regulatory constraints: Export controls and tariffs continue to shape sourcing strategies—driving investments in alternative supply bases, on‑shore assembly, and qualification of second‑source semiconductor suppliers for critical platforms.
Our report includes a prioritized list of mitigations and procurement playbooks tailored to different company profiles: OEMs with high design rigidity, contract manufacturers with variable customer mixes, and pure‑play semiconductor vendors seeking to insulate their fabs and revenue streams.
Technology trajectories and product innovation
Technical evolution in gate driver ICs is happening along several axes that will determine which product architectures capture the most value:
- Integration — SmartMCD approaches (MOSFET integrated with driver and sometimes MCU) reduce system BOM and assembly complexity, enabling compact designs for automotive pumps, fans and small motors. This integration shortens design cycles but raises qualification intensity for safety‑critical applications.
- SiC and isolation — Isolated gate drivers designed for SiC switching and higher system voltages are becoming essential where efficiency and power density are priorities, particularly in traction and high‑power industrial applications.
- Embedded intelligence — Gate drivers with integrated current sensing, self‑diagnostics and sensorless control expand the system value proposition and support higher levels of predictive maintenance and closed‑loop control.
- Functional safety and certifications — ISO 26262 compliance and AEC‑Q100 qualification remain gating factors for large OEM opportunities; suppliers that fast‑track documentation and compliance testing unlock system design wins.
We evaluate these contrasts at a modular level to advise whether to pursue bespoke silicon, licensed IP, or partner integrations based on cost, time‑to‑market and end‑market margins.
Strategic recommendations for 2026
For executive teams making resource allocation decisions this year, PW Consulting’s core recommendations are:
- Prioritise dual‑sourcing and local buffer inventories for MOSFETs and other long‑lead inputs. Lead‑time volatility is a near‑term reality and proactive inventory strategies reduce churn at the system level.
- Invest selectively in integration where it unlocks systems margin and shortens OEM qualification cycles, but avoid overpaying for generic integration in commoditizing segments.
- Accelerate certification roadmaps (functional safety and automotive qualifications) now—design cycles and validation windows are long; early investment yields disproportionate returns in design‑win capture.
- Use partnership and JV structures to mitigate geopolitical exposure to critical materials and to create regionalised capacity for high‑volume automotive and industrial customers.
- Evaluate M&A targets that bring differentiated IP (SiC‑grade isolation, advanced sensorless algorithms) rather than scale for scale’s sake; the market’s concentration profile rewards specialty assets that expand accessible end‑market addressability.
What the preview intentionally withholds — and why
True to the “trailer” principle of this preview, we are sharing directional, high‑confidence insights while withholding the granular, monetised splits and proprietary scenario matrices that form the core of the full report. Detailed regional and application breakdowns, segment‑level revenue tables, and supplier market‑share time series are available exclusively in the full document. This is deliberate: precise segmentation and share data are the actionable intelligence organisations need for contractual negotiations, supplier scorecards and M&A valuations.
Clients and readers who require those specifics can access them via the full report, which contains downloadable tables, an interactive forecast model and supplier benchmarking tools tailored to different buyer profiles.
Next steps
PW Consulting’s Gate Driver ICs for BLDC Motors Market report is structured to support immediate strategic planning cycles in 2026. If you are preparing 2026 R&D budgets, supplier negotiations, or M&A pipeline screens, the full report will provide the calibrated inputs and scenario tools to prioritise and quantify your options. For organisations seeking bespoke workshops, PW Consulting also offers targeted briefings that overlay your company’s product roadmap and supplier footprint onto the market model to generate a 90‑day action plan.
To learn more about the full report and to schedule a briefing, please visit the PW Consulting website or contact our market intelligence team. The complete study contains the proprietary segment tables, supplier scorecards, and downloadable forecast models that underpin the strategic recommendations outlined here.
About PW Consulting
PW Consulting specialises in translating semiconductor and power‑electronics markets into board‑level strategy. Our research combines deep technical competency with rigorous commercial analysis to deliver workplans that executives can act on within quarter‑to‑quarter planning cycles.
For detailed analysis of this topic, please visit the official page: Gate Driver ICs for BLDC Motors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Video Inspection Robot Market to Reach USD 4,158.62 Million by 2032, Expanding at a 7.85% CAGR (2026–2032)
By pmarketresearch, 2026-08-12
Video Inspection Robot Market 2026: Strategic Imperatives from PW Consulting’s Latest Industry Brief
As infrastructure owners, industrial operators, and technology investors plan for the next chapter of capital allocation and operational modernization, PW Consulting releases a targeted industry brief that synthesizes multi-year market dynamics and delivers an actionable roadmap for decisions to be taken in 2026. Our Video Inspection Robot Market report — built on a 2020–2025 historical base and a 2026–2032 forecast horizon — frames opportunity and risk across technology, supply chains, regulation, and competitive positioning. At the macro level, the market has expanded materially from our 2025 base and is forecast to grow at a compound annual growth rate (CAGR) of 7.85% through the forecast period, reflecting accelerating investment in remote visual inspection, robotics autonomy, and data-driven asset management.
Worldwide Benchtop Hydrogen Analyzers Market
Why this brief matters for 2026 decision-makers
-
Timing: 2026 will be a decision-heavy year for procurement cycles and deployment pilots. Organizations that move beyond vendor demonstrations to structured pilots with well-defined success metrics will secure earlier operational benefits and superior negotiating leverage.
Story Puzzle Game Market -
Capital allocation: With the market set on a mid-single-digit to high-single-digit growth trajectory, executives must choose between buying mature systems, co-developing specialized platforms, or adopting robotics-as-a-service models. Each path has distinct implications for CAPEX, OPEX, and balance-sheet exposure.
1G6P Lens Market -
Regulatory and supply risks: New trade and regulatory actions, coupled with sensor and optics supply constraints, are compressing lead times and increasing components’ unit cost volatility. Procurement teams need hedging strategies that go beyond single-source buying.
-
Data monetization and asset intelligence: Video inspection platforms are becoming conduits for condition-based maintenance and GIS-enrichment. How organizations design their data ingestion, labeling, and analytics pipelines will determine the long-term ROI of robotics investments.
What’s inside the PW Consulting brief (practical content highlights)
-
Executive synthesis: A concise view of market size, growth trajectory, and high‑level segmentation dynamics to support board-level briefings and investor memos.
-
Technology maturity map: Comparative assessment of mobility platforms (crawlers, pole systems, aerial drones), onboard imaging and sensor suites (HD video, sonar, laser profiling), autonomy stacks (path planning, SLAM, defect recognition), and communications approaches (wireless, tethered, edge-cloud). Each technology is scored for readiness, integration complexity, and expected TCO impact.
-
Vendor diligence templates: Rapid supplier scorecards, contract negotiation checklists, test-and-acceptance protocols, and field validation playbooks to reduce procurement cycle time and mitigate integration risk.
-
Implementation playbooks: Step-by-step deployment roadmaps by use case (e.g., sewers and pipeline inspection, confined space inspection, large‑diameter asset monitoring) including pilot sizing, metrics for go/no-go decisions, and maintenance scheduling guidance.
-
Regulatory impact and scenario planning: Structured scenarios that quantify the operational impact of tariff regimes, import controls, and certifications (e.g., ATEX/IECEx) on sourcing strategies and total cost of ownership.
-
Financial tools: ROI and payback calculators, service model comparisons (capex vs. robotics-as-a-service), and sensitivity analyses that stress-test vendor pricing and component-cost inflation.
-
M&A and partnership playbook: Criteria for evaluating acquisition targets and technology partnerships, and a shortlist of capability gaps that are most valuable to bolt-on or co-develop.
Competitive landscape — what to watch
The market remains fragmented with a modest level of concentration: the top three suppliers account for under one quarter of industry sales and a top five concentration below forty percent. That structure creates room for both focused niche players and global integrators to capture value.
-
Envirosight LLC (Randolph, NJ) continues to push the boundary on integrated inspection platforms with HD imaging and AI-assisted defect detection embedded in field-capable crawlers. Their recent product introduction further crystallizes the shift from manual video logs to automated defect recognition workflows, making them a benchmark for municipal and utility procurement teams seeking vendor maturity.
-
Deep Trekker Inc. (Kitchener, ON) remains differentiated by hybrid underwater and confined-space platforms that combine mobility engineering with proven HD optics. Their systems are often selected for cross-environment use cases where robustness and ease-of-deployment matter more than peak autonomy.
-
IBAK Helmut Hunger GmbH & Co. KG (Kiel, Germany) has advanced panoramic video and 3D laser profiling integration, signaling a move toward high-fidelity condition assessment packages that support advanced asset modeling and rehabilitation planning.
-
CUES Inc. , RedZone Robotics , Mini-Cam Ltd. , and iPEK each bring distinctive approaches—truck-mounted systems, large-diameter automation, compact drain crawlers, and modular CCTV platforms respectively—highlighting the spectrum of form factors buyers must evaluate.
-
Waygate Technologies (Baker Hughes) illustrates how industrial multinationals are applying remote visual inspection expertise to hazardous and certified environments; their recent deployment of explosion-proof robotic systems underscores demand for certified offerings in energy and petrochemical sectors.
-
Wuhan Easy-Sight and other Asia-based manufacturers remain competitive on price and increasingly on feature parity; however, buyers must overlay geopolitical and tariff considerations into sourcing decisions.
Recent market moves and implications
-
Product innovation is active: Several vendors launched new platforms or upgrades in 2025–2026 that embed AI, panoramic 3D profiling, wireless telemetry, and intrinsically safe certifications. Buyers should adopt evaluation frameworks that prioritize integration capability and lifecycle update paths over one-off feature sets.
-
Regulatory trade actions are reshaping sourcing: Investigations and tariffs initiated in 2025 impacting robotics and related components increase the probability that procurement teams will incur higher landed costs or face longer lead times. Scenario-based sourcing and dual-sourcing strategies are no longer optional for critical programs.
-
Supply-chain constraints around precision optics and sensors remain the primary operational choke point. Teams that invest in early qualification of alternative suppliers and component-substitution testing will shorten deployment cycles and reduce schedule risk.
Strategic recommendations for 2026 — six concrete moves
-
Conduct a 90‑day supplier stress test: Simulate procurement cycles under tariff and lead‑time stress to identify single points of failure. Prioritize vendors that can produce certified alternatives or have regional manufacturing footprints.
-
Run two parallel pilots: one focused on operational maturity (scheduling, integration with CMMS/GIS) and another focused on analytics (AI defect recognition, dataset labeling). Require vendors to deliver exportable video/data deliverables to avoid lock-in.
-
Implement a modular procurement clause: Specify interchangeability of core elements (cameras, processors, comms) to foster competitive upgrade paths and reduce total upgrade costs over the asset lifecycle.
-
Negotiate outcome-based contracts for high-volume programs: Tie a portion of vendor compensation to agreed uptime, inspection throughput, or defect-detection accuracy to align incentives and shift risk to suppliers.
-
Invest in a data strategy and governance model: Define labeling standards and data storage schemas now so inspection outputs can be monetized or repurposed across asset management, planning, and regulatory reporting functions.
-
Evaluate strategic M&A or JV options to fill capability gaps (e.g., autonomy, laser profiling, explosion-proof certifications) rather than relying solely on long, uncertain internal development cycles.
How PW Consulting’s dataset supports these decisions
Our brief pairs a quantitative top-down market sizing with practical, operationally oriented deliverables. We provide the high-level market scale and the growth rate context you need to prioritize portfolios and scenario-plan for 2026, while delivering the playbooks, scorecards, and procurement templates organizations require to convert strategy into executed programs. To preserve our role as an unbiased advisor and to protect proprietary client workflows, deeper segmentation matrices, vendor market shares, and precise pricing benchmarks are made available exclusively in the full report and accompanying data package.
Final note — the “trailer” approach
This industry brief is designed as a high-value preview: it demonstrates the analytical depth and practical orientation of PW Consulting’s Video Inspection Robot Market report while intentionally withholding proprietary subsegment tables and granular vendor share figures. If your organization is preparing a 2026 procurement cycle, an investment evaluation, or an asset digitalization roadmap, the full report contains the detailed datasets, scenario models, and negotiation templates required to act with confidence.
To request the complete report, data workbook, and an executive briefing tailored to your organization’s operating context, visit our report page or contact the PW Consulting industry desk. Time-sensitive regulatory shifts and component shortages make rapid access to validated market intelligence a competitive advantage — now is the moment to convert insight into decisive action.
For detailed analysis of this topic, please visit the official page: Video Inspection Robot Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: New report predicts Epoxy Electrocoating market to expand at a 4.5% CAGR through 2032
By pmarketresearch, 2026-08-12
Epoxy Electrocoating Market — Strategic Outlook 2026: PW Consulting Insights
Executive summary
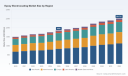
PW Consulting’s latest Epoxy Electrocoating Market report (base year 2025) delivers a forward-looking toolkit for executives making high-stakes sourcing, manufacturing, and M&A decisions in 2026. After tracking the market through the 2020–2025 historical window, our model forecasts the global epoxy e-coat market to grow at a steady compound annual growth rate (CAGR) of 4.5% over the 2026–2032 forecast horizon. The market expanded from about USD 1.5 billion in 2020 to roughly USD 1.85 billion in 2025, and is projected to surpass USD 2.5 billion by 2032 under our central scenario.
XR Imaging Waveguide Market
This release summarizes the strategic implications that matter most to C-suite and business unit leaders — while reserving proprietary, line-item segmentation and scenario tables for the full report. Consider this a high-fidelity preview: deep enough to guide near-term strategy, intentionally limited to encourage direct access to the complete dataset and decision-support materials.
Kraft Interleaving Paper Market
Market trajectory and macro drivers
-
Demand resilience and steady growth: The epoxy electrocoating market has shown consistent expansion through 2020–2025, reflecting its entrenched role in corrosion protection for automotive OEMs, industrial machinery, and durable appliances. Our base-year assessment (2025) captures the market at approximately USD 1.85 billion, with a prudent baseline projection rising to ~USD 1.92 billion in 2026 and continuing to reach roughly USD 2.52 billion by 2032 under the central-case 4.5% CAGR.
Spaceborne Multibeam Antennas Market -
Cost and supply-chain volatility: Raw-material headwinds have intensified in early 2026. Regional epoxy resin price observations in April 2026 show material cost pressures — for example, Northeast Asia pricing near USD 2.62/kg (up ~23% year-over-year in our monitoring window) and increases in Europe and the Middle East that have meaningfully raised input cost baselines. These moves are being reinforced by corporate pricing actions across the value chain.
-
Policy and trade friction: Recent regulatory actions — notably final affirmative determinations by the U.S. Department of Commerce in antidumping and countervailing duty investigations on epoxy resins from several producing countries — introduce a new layer of trade risk and cost of goods considerations for manufacturers and importers in 2026.
Dynamics shaping 2026 decisions
-
Input-cost passthrough and margin management: Manufacturers and OEMs must reassess price models and contractual terms. Our scenario workbench demonstrates that in most cases, immediate margin pressure from April–June 2026 epoxy resin inflation cannot be absorbed without operational levers or renegotiated supply agreements.
-
Sourcing diversification vs. consolidation: The ecosystem remains moderately concentrated; the top three suppliers control a clear majority of market supply, with the top five exerting near-three-quarters influence on the market. This concentration amplifies supplier-side pricing influence but also presents targeted partnership opportunities for buyers seeking security of supply.
-
Technology and application transitions: Low-temperature curing formulations, lower-voltage application systems, and sustainability-focused chemistries are gaining traction. Investments in these technology vectors reduce energy intensity and support OEM sustainability commitments — a material consideration for capex prioritization in 2026.
-
Regional demand shifts: Growth momentum in Asia-Pacific continues to shape capacity decisions, while mature markets sustain demand through replacement and aftermarket activity. Our full report quantifies these flows at a granular level and models cross-border trade under varying tariff and duty scenarios.
Competitive landscape — what the leading players are doing
We examined the strategies and capabilities of leading suppliers and technology owners to map competitive advantage across production footprint, product performance, and customer intimacy. Highlights:
-
PPG Industries, Inc. (Pittsburgh, USA) — maintains leadership through its Powercron cathodic epoxy line, emphasizing high corrosion resistance and uniform film build. Its global customer relationships in industrial and automotive sectors are a structural advantage for volume and innovation partnerships.
-
Axalta Coating Systems (Philadelphia, USA) — positions its AquaEC cathodic epoxy series toward OEMs prioritizing corrosion protection and mechanical performance. Axalta’s strength is in integrated coatings systems and OEM program alignment.
-
BASF SE (Ludwigshafen, Germany) — leverages its CathoGuard family and broad materials science platform. Recent greenfield and expansion investments underscore BASF’s intention to support automotive OEM re-shoring and regional capacity needs.
-
The Sherwin-Williams Company (Cleveland, USA) — focuses on heavy machinery and industrial applications with formulations engineered for edge coverage and substrate performance in challenging environments.
-
Nippon Paint and Kansai Paint (Japan) — together with regional specialists like KCC Corporation and Tatung Fine Chemicals, they offer strong local capabilities across Asia, often emphasizing eco-efficiency, low-temperature curing, and supply reliability for OEMs in the region.
Recent corporate actions matter for 2026 strategy. For example, BASF commissioned a new automotive coatings plant in Münster in late 2025 and expanded e-coat capacity in Mangalore in early 2026 — moves that change competitive capacity and customer lead-times in Europe and South Asia. Meanwhile, DIC Corporation’s April 2026 announcement of price increases for epoxy resins and curing agents is a leading indicator of continued upstream price volatility. These events reinforce the need for dynamic supplier engagement and scenario modeling.
What’s inside the full PW Consulting report (actionable, practitioner-focused)
The full report is structured to move teams from insight to action during 2026 planning cycles. Key deliverables include:
-
Market size and forecast model (2020–2032) with company-level roll-ups and scenario toggles — base case, upstream shock case, and accelerated electrification case.
-
Supplier risk heatmap — assessing concentration, geopolitical exposure, feedstock sensitivity, and capacity elasticity at the production-node level.
-
Cost-pass-through and margin impact calculators — sector-specific templates that allow procurement and finance teams to stress-test contracts against realistic resin-price trajectories.
-
Technology readiness assessment — performance, capex implications, and time-to-market for low-temp curing, low-VOC chemistries, and application equipment.
-
M&A and partnership playbook — prioritized target archetypes (bolt-on capacity, technology play, or channel access) and valuation benchmarks informed by concentration metrics and recent transactions.
-
Regulatory and trade impact matrix — mapping antidumping/countervailing outcomes and likely near-term trade frictions to procurement and distribution strategies.
Note: This summary intentionally preserves proprietary segmentation tables and unit economics that are included exclusively in the paid report. Those granular figures — including formulation-, region-, and end-use breakouts by revenue and volume — are available to subscribers and clients through our secure portal.
Practical recommendations for 2026
-
Immediate (0–3 months): Stabilize supply through dual-sourcing of critical resins, activate price-index clauses where feasible, and run the PW Consulting cost-pass-through calculator against current contracts to quantify near-term margin exposure.
-
Near-term (3–9 months): Prioritize small-capex pilot projects to qualify low-temperature and low-VOC formulations with key OEM customers. These pilots both reduce energy usage and create differentiators for future contracts.
-
Medium-term (9–18 months): Revisit capacity plans in light of upstream inflation and trade measures. For producers, we recommend a staged investment approach — conditional on validated off-take agreements or supply contracts that mitigate feedstock risk.
-
Strategic (12–36 months): Assess targeted M&A to plug strategic gaps — for example, acquiring regional formulation expertise or localized production to minimize tariff/duty exposures and logistics costs under stressed trade scenarios.
Methodology and data integrity
Our analysis synthesizes primary interviews with supply-chain executives, OEM procurement data, regional trade statistics, company filings, and independent price monitoring. The report uses the calendar year 2025 as the base year, covers the historical period 2020–2025, and presents a 2026–2032 forecast scenario set. Financials are reported in USD, with market values expressed in millions for comparability.
Why this matters for 2026
Two simultaneous trends define the strategic landscape for epoxy electrocoating in 2026: persistent upstream cost volatility and accelerating technology-driven product differentiation. Companies that act early — securing supply, validating energy-efficient formulations, and aligning with OEM decarbonization priorities — will convert transient pressures into durable competitive advantage. Conversely, passive actors risk margin compression and supply disruption as raw-material and trade dynamics evolve.
Next steps
PW Consulting’s full Epoxy Electrocoating Market report contains the granular segmentation, downloadable model files, supplier scorecards, and bespoke advisory options designed to support procurement, operations, and strategy teams through 2026 planning cycles. For tailored briefings, scenario workshops, or to acquire the complete dataset and modeling tools, please contact PW Consulting through our corporate channels or visit our report landing page for subscription details.
For detailed analysis of this topic, please visit the official page: Epoxy Electrocoating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pod Hotel Market Poised for 7.15% CAGR in 2026–2032, Driving Global Expansion
By pmarketresearch, 2026-08-12
Pod Hotel Market 2026 Strategic Preview: What Every Executive Needs to Know Before Committing Capital
As the travel sector continues its uneven recovery and urban land economics push lodging operators to innovate, pod hotels are moving from niche experiment to repeatable business model. PW Consulting’s forthcoming Pod Hotel Market report—anchored to a 2025 base year and projecting through 2032—maps the end-to-end economics, competitive moves, and regulatory contours that will determine winners in 2026 and beyond. This preview summarizes the strategic value of the full study for corporate decision-makers, while preserving the granular segment tables and site-level intelligence that we reserve for the complete report.
THz Polarizers Market
Executive summary: growth, concentration, and what it means for 2026 plays
Between 2020 and 2025 the global pod hotel market more than doubled in strategic relevance: total market revenue expanded from roughly USD 170 million to USD 245.5 million, reflecting resilient consumer adoption across transit, urban, and leisure settings. Our forecast begins in 2026 and extends to 2032, during which the market is projected to grow at a compound annual growth rate (CAGR) of approximately 7.15%, reaching an estimated ~USD 398 million by 2032.
Solid-state Active Cooling Chip Market
Two structural features jump out from PW Consulting’s analysis:
Quantum Computing Online Platform Market
- Fragmentation: market concentration remains low—top-three and top-five operators together control a small fraction of global revenues—creating a permissive environment for new entrants, regional roll-ups and brand-consolidation plays.
- Capital efficiency: relative to full-service and even limited-service hotels, pod facilities demonstrate materially lower per-unit construction cost and the potential for compressed payback periods, enabling faster portfolio growth under the right operational model.
Why this matters for 2026 decision-makers
For hotel chains, private equity investors, urban landlords and institutional capital, the pod hotel category presents a set of attractive strategic options in 2026:
- Portfolio densification: pod concepts can unlock incremental revenue on constrained urban parcels or within mixed-use assets where traditional hotel footprints are uneconomic.
- Transit-node monetization: short-stay and micro-rest demand at airports and major rail hubs continues to climb; appropriately designed pods capture yields that are structurally different from traditional transient room nights.
- Modular growth plays: manufacturers and hotel operators can pursue factory-built pod roll-outs to compress opening timelines and standardize quality across assets, improving return predictability.
What the numbers reveal (high level)
Our top-line trajectory—from USD 245.5 million in 2025 to a projected USD 267.5 million in 2026 and on toward nearly USD 400 million by 2032—is evidence of steady demand and expanding investor interest. Importantly, the 7.15% CAGR is not a uniform expansion; value pools within the market will rotate as operators innovate on experience, distribution and partnerships. The full report contains the granular demand drivers and revenue-mix scenarios that underlie this headline forecast (note: detailed regional and channel-level tables are intentionally not reproduced in this preview).
Competitive landscape: who to watch and why
The pod sector features a mix of legacy capsule players, urban lifestyle brands and systems suppliers. Market participants range from purpose-built airport pod specialists to hybrid boutique brands aiming at city-business and leisure audiences. Key profiles we analyze in the report include:
- nine hours Inc. (Tokyo) — a minimalist capsule pioneer emphasizing sleep optimization and tech-enabled health partnerships. Their recent announcement of a Shinjuku-North property (planned opening mid‑2026) and collaboration with a medical university for sleep-monitoring underscores a premium, research-aligned approach to product differentiation.
- First Cabin (Japan) — positions itself between capsule and business hotel categories with upgraded cabin amenities; international site selection activity signals a brand strategy focused on premium compact stays.
- YOTEL (London) — translates airline-cabin efficiency into a scalable global brand, with airport variants (YOTELAIR) that demonstrate how pod layout and operational design can be standardized across complex terminals.
- Bobobox (Indonesia) — a tech-first operator leveraging IoT and modular design to expand rapidly in a price-sensitive, high-demand domestic market—recent network additions illustrate the speed and feasibility of aggressive rollouts.
- Sleepbox, napcabs, GoSleep — specialized suppliers and operators focused on transit and workplace rest solutions; these players are important partners for landlords and airports seeking turnkey pod deployments.
- The Pod Hotel (New York) — an example of urban boutique scale-up, combining style and compact efficiency in dense city centers.
PW Consulting’s competitive analysis goes beyond profiles: we score operators on product differentiation, unit economics, distribution sophistication and partnership agility. The report includes M&A playbooks, franchise and management-fee comparators, and proprietary readiness indices that help acquirers and brand teams prioritize targets.
Operational and development dynamics shaping 2026 roll-outs
Developers and operators contemplating new builds or conversions must balance four operational levers: unit construction cost, build cadence, regulatory compliance and ancillary revenue design. Key insights from our field and desk work:
- Unit economics: capsule unit construction typically ranges widely, reflecting product complexity and fit-out level, but remains materially lower than traditional hotel rooms. This creates a faster nominal payback window—our synthesis indicates payback horizons that can compress into 2–4 years under conservative occupancy and ADR assumptions.
- Modular advantage: factory-built pod modules reduce on-site labor and waste, and can reduce time-to-market substantially. We document examples where a customized pod module strategy enabled a site to reach operational readiness in roughly three months from first delivery.
- Regulatory overlay: pod developments must be navigated through local building codes and safety regimes—fire protection, ventilation, privacy and hygiene standards differ materially across jurisdictions. Early regulatory engagement is non-negotiable; our report includes a compliance checklist and jurisdiction risk matrix that saves development teams months of negotiation time.
- Distribution and revenue management: while online travel agencies remain a central channel for transactional demand, our field interviews show that direct-booking strategies, membership programs and corporate block agreements materially improve RevPAR and repeat visitation for pod operators.
Actionable strategic recommendations for 2026
PW Consulting recommends that executives consider the following priority actions as they set 2026 objectives:
- Adopt a two-track entry strategy: pilot lightweight, modular sites in high-yield transit or urban fringe locations while concurrently testing a premium, tech-enhanced pod prototype in gateway cities to capture both volume and margin.
- Lock in manufacturing partnerships early: long lead times for custom pods and component sourcing mean that procurement decisions made in 2026 determine feasibility windows for 2027 openings.
- Negotiate flexible regulatory pilot arrangements: target municipalities with established “innovation corridors” and seek conditional approvals that allow phased openings tied to compliance milestones.
- Design ancillaries for yield: prioritize flexible workspace, short-stay F&B and locker/last-mile services to diversify revenue per square foot beyond bed nights.
- Prepare for consolidation: given the fragmented nature of the market, create a clear M&A horizon—identify acquisition targets that provide route-to-market rather than just bed-counts, and use standardized scorecards from our report to underwrite bids.
What the full PW Consulting Pod Hotel Market report includes
The complete report is a practical toolkit for deal teams, operators, and city planners. Highlights include:
- Top-down and bottom-up market-sizing for 2020–2032 with scenario-based forecasts and sensitivity testing.
- Operational benchmarks: capex/OPEX per pod, staffing models, IT/IoT integration costs and occupancy-to-ADR mapping for revenue forecasting.
- Competitive playbook: operator profiles, expansion timelines, brand-positioning matrices and M&A readiness scores.
- Site-selection model: demand catchment analytics, transit-node scoring, commercial tenancy synergies and landlord uplift estimates.
- Regulatory and compliance compendium with jurisdictional red flags and a phased approval template.
- Vendor directory and procurement framework for modular pod manufacturers, installers and maintenance partners.
- Financial model templates and investor-ready pitch decks for growth equity and franchise offers.
To preserve commercial value for subscribers and enterprise clients, segment-level tables and the full state-by-state/regional breakouts are available only in the paid report and our client workshop packages.
How to use this preview for 2026 planning
Use this preview to align strategic priorities: decide whether to pilot, scale or partner; earmark capital for modular manufacturing; and accelerate regulatory engagement in target cities. If you are assessing acquisition pipelines, prioritize assets that offer rapid retrofit potential or embedded transit demand. For operators looking to internationalize, focus first on replicable product standards and centralized procurement to protect margins during expansion.
Next steps
PW Consulting is offering limited advisory slots for 2026 execution plans rooted in the full Pod Hotel Market report. Clients receive the complete dataset, our proprietary scenario models, and an on-site strategy workshop to convert insight into an executable 12–36 month plan. For access to the full report and advisory services, please visit PW Consulting’s reports page or contact your account representative to schedule a briefing.
Our preview is designed to help you ask the right questions. The full analysis delivers the answers—and the models—to act with confidence in 2026.
For detailed analysis of this topic, please visit the official page: Pod Hotel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Email Deliverability Services Market to Grow at 11.78% CAGR — From USD 1,445.9 Million in 2025 to USD 3,152.8 Million by 2032
By pmarketresearch, 2026-08-12
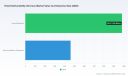
PW Consulting: New Market Intelligence on Email Deliverability Services — Strategic Guide for 2026 Decision-Makers
PW Consulting today publishes its latest market research brief on the Email Deliverability Services market, designed as a strategic playbook for senior executives and procurement teams preparing budgets and technology roadmaps for 2026. Built on an empirical foundation covering 2020–2025 with a forecast window of 2026–2032, the report synthesizes macro market trends, vendor positioning, regulatory headwinds, and actionable implementation guidance — while preserving detailed segment-level datasets for subscribers.
Worldwide Artificial Leather for Furnitures Market
Why 2026 Is a Defining Moment for Deliverability Strategy
- Mailbox providers and regulators have made 2025 the baseline year for tougher enforcement: widespread adoption of stricter DMARC policies, reinforced requirements for SPF/DKIM, and more rigorous consent expectations mean that 2026 budgets must prioritize compliance as a first-order deliverability control.
- Market telemetry indicates meaningful improvements in average global inbox placement in 2025, yet variation across provider and geography remains material. This dichotomy forces organizations to shift from ad-hoc fixes to systematic deliverability programs that combine technology, process, and vendor partnerships.
- For leaders evaluating digital engagement spend, deliverability is no longer a narrow email ops concern — it is a revenue and risk management discipline that intersects privacy law, brand reputation, and customer experience.
Market Trajectory: Growth, Scale and What It Means for Planning
The email deliverability services market has moved from a niche optimization category into a robust and fast-growing market. Our analysis traces market expansion from under a billion USD in 2020 to a significantly larger market by the 2025 base year, and projects continued high-teens to low-twenties growth in many subsegments through 2032. The market exhibits a compound annual growth rate of 11.78% over the forecast horizon, reflecting sustained demand for verification, authentication, reputation management, testing, and managed services as organizations scale their digital communications.
Buck DC/DC Switching Regulator Market
For procurement and finance teams, the implication is clear: deliverability should be modeled as a multi-year capability investment with recurring operating costs and potential capital for integrations. Strategic budgeting must incorporate scenario planning around provider policy shifts, regulatory compliance costs, and resource needs for in-house versus outsourced models.
Worldwide Electric Bean Grinders Market
What the Report Contains — Practical, Operational, and Decision-Ready
- Actionable playbooks for operationalizing deliverability: audit templates, stepwise remediation roadmaps, and an integration checklist for authentication (SPF/DKIM/DMARC), list hygiene, warm-up, and monitoring.
- Vendor selection framework: criteria-weighted scorecards (technical fit, data security posture, SLA structure, managed-service capability, and change management support) tailored for three archetypal buyer profiles — high-volume transactional senders, marketing-sending enterprises, and organizations running cold outreach programs.
- Procurement instruments and negotiation levers: a practical primer on crafting SLAs, setting deliverability KPIs, and designing vendor pilot programs that minimize operational disruption.
- Case studies and ROI models: anonymized client engagements that illustrate time-to-value, cost-of-poor-deliverability, and the business case for shifting from in-house experimentation to managed services or hybrid models.
- Compliance and risk playbook: mappings from regulatory requirements (including consent and data protection expectations) to mailbox provider rules and operational controls that reduce the risk of inbox exclusion or fines.
- Interactive methodologies: readers will find transparent modeling approaches, assumptions and scenario drivers — the underlying datasets and detailed segment analytics are retained for subscribers and website access.
Competitive Landscape: Who’s Shaping the Market and Why It Matters
The market is a mix of specialist consultancies, verification platforms, email delivery platforms, and testing tools. Each class of provider plays a different strategic role:
- Full-service consultancies (example: InboxArmy; Email Industries) — These firms excel at complex remediation, reputation management, and strategic program delivery for mid-market and enterprise clients. They provide hands-on change management that many organizations need when mailbox provider interventions are systemic rather than tactical.
- Verification and hygiene specialists (example: Kickbox; ZeroBounce) — Leaders in list validation and scoring, useful for organizations seeking to reduce bounce risk and optimize list quality before scale sends. Their tooling is increasingly embedded in broader deliverability stacks.
- Delivery platforms with native deliverability features (example: Mailgun; Postmark; SendGrid) — These providers combine API-driven sending with operational features (infrastructure segregation, analytics, warmup). Organizations with heavy transactional volumes will often prioritize platform-level guarantees and integration efficiency.
- Monitoring and testing tools (example: GlockApps; Mailtrap) — Focused on inbox placement checks, reputation tracking and pre-send testing, these products reduce time-to-detection for deliverability regressions and are frequently bundled into internal QA workflows.
- Specialized optimization platforms (example: Folderly) — Emerging AI-assisted platforms focus on domain warmup, automated remediation recommendations, and continuous optimization — areas of rapid innovation that appeal to fast-growth firms and agencies.
Market concentration metrics indicate a market with meaningful leaders but room for niche competitors and consolidation. The top-tier players collectively account for measurable market share, leaving strategic openings for firms that can combine deep technical capabilities with industry-specific compliance and integration offerings.
Regulatory and Operational Risks — The New Normal
- Regulatory compliance is now embedded in deliverability outcomes. Comprehensive consent frameworks and data protection rules expose senders to significant financial and reputational risk if programs are misaligned with legal obligations.
- Mailbox provider enforcement is operationally prescriptive: authentication, transparent unsubscribe mechanisms, and sustained low complaint rates are non-negotiable. Benchmarks in 2025 show average inbox placement in the mid‑80s percentage range globally, but single-point failures can lead to severe placement deterioration.
- Operational cost variability matters. Cold-email infrastructure and warm-up activities have a cost spectrum that organizations must budget for when evaluating in-house vs. managed approaches. Dedicated IP options and domain management add additional line items that should be factored into TCO models.
Strategic Recommendations for 2026 Decision-Makers
- Elevate deliverability from a tactical ops function to a cross-functional capability owned jointly by marketing, security/compliance, and IT. Create a single roadmap that aligns authentication, list hygiene, and consent management with business KPIs.
- Invest early in continuous monitoring and alerting. Rapid detection of placement changes reduces remediation costs and protects revenue-sensitive flows (transactional notifications, billing, critical user comms).
- Select vendors according to use-case and integration risk. Prioritize platform partners for heavy transactional volumes, consultancies for complex remediation needs, and verification providers for high-volume list management.
- Model multiple enforcement scenarios in your 2026 budget process — including stricter DMARC rollouts and higher compliance audit frequencies. Use the market growth trajectory as a baseline, and stress-test for policy shocks.
- Use a staged procurement approach: proof-of-value pilots, followed by phased rollouts tied to performance gates. Negotiate contractual provisions that tie fees to agreed deliverability outcomes where feasible.
- Plan for talent and process investments. Managed services can accelerate time-to-compliance, but internal capability is essential for long-term governance and vendor oversight.
About the Report and Next Steps
PW Consulting’s research provides the strategic context, operational templates, and competitive analysis decision-makers need to act in 2026. To preserve commercial utility and to honor client confidentiality among the many data contributors, core segment-level tables, regional breakdowns, and vendor scorecards are published in the full report available via PW Consulting’s website. Executives who require bespoke briefings, vendor shortlists, or a rapid diagnostic tailored to their sending profile can request a workshop with our email deliverability practice.
In an environment where mailbox provider policy changes and privacy enforcement converge, organizations that pair disciplined compliance with robust technical controls will convert deliverability from a recurring risk into a measurable growth lever. PW Consulting’s Email Deliverability Services report is designed to make that transition faster, less risky, and measurably more profitable.
For licensing, enterprise briefings, or to access the complete dataset and interactive dashboards, visit the PW Consulting portal or contact our industry practice leads for a confidential consultation.
For detailed analysis of this topic, please visit the official page: Email Deliverability Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Computer Consulting Services Market to Expand from USD 865.0 Billion in 2025 to USD 1.50 Trillion by 2032 at an 8.2% CAGR — North America Leads with USD 327.7B; Top‑5 Firms Hold 24.1%
By pmarketresearch, 2026-08-12
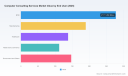
Computer Consulting Services Market 2026: Strategic Imperatives from PW Consulting
PW Consulting’s newest market research release, Computer Consulting Services Market — 2026 Edition, frames a decisive moment for CIOs, procurement chiefs, and private equity investors planning enterprise technology allocations this year. With a robust compound annual growth rate (CAGR) of 8.2% and a global services market that reached an estimated USD 865.0 Billion in our 2025 base year, our analysis projects sustained expansion through 2032 — underlining both scale and the structural shifts reshaping how organizations buy, contract and consume IT consulting services.
Digital Trunking Intercom Market
Why this report matters for 2026 decision cycles
Corporate technology roadmaps for 2026 must confront three simultaneous forces: accelerated adoption of AI and real-time data architectures; intensifying regulatory and operational resilience requirements; and continued pressure on total cost of ownership driven by labor market dynamics. PW Consulting’s study synthesizes these forces into a pragmatic playbook. The report translates macro growth (with a forecasted pathway extending to a projected market north of USD 1.5 Trillion by 2032) into tangible, time-bound actions — enabling leaders to prioritize investments that preserve optionality while capturing near-term value.
Totem Pole PFC Market
What the research reveals (high level)
- Market momentum is structural, not cyclical: the services market has expanded markedly since 2020 and our base-year analysis shows continued year-on-year growth into 2026 and beyond.
- Vendor ecosystems are expanding around data, cloud and AI platforms. Strategic M&A, platform plays and managed offerings are re-shaping competitive advantage — creating new choices but also new integration and governance imperatives for buyers.
- The provider landscape remains fragmented. Top-tier firms capture a meaningful share, yet overall concentration is moderate (our concentration analysis shows a three-firm and five-firm share that underlines available room for specialist players and new entrants).
- Regulation and labor cost trends are now first-order considerations in vendor selection, contract design, and sourcing strategy.
Practical content inside the report
This is a practitioner’s report designed to inform active procurement and strategy decisions in 2026. Core deliverables include:
AI Tool for Aviation Market
- Proprietary market-sizing and forecast model (historical 2020–2025, forecast 2026–2032) with scenario lanes for macro, technology adoption and regulatory shock events.
- A vendor assessment framework with scored dimensions for capability depth, delivery footprint, platform partnerships, IP controls, pricing models and migration velocity.
- Go-to-market playbooks and procurement templates tailored for enterprise buyers — including phased engagement models (proof-of-concept → scale → run), outcome-based contracting clauses, and performance SLAs mapped to business outcomes.
- Technology adoption timelines and capability roadmaps for AI, hybrid cloud, real-time data streaming, and cybersecurity, highlighting typical adoption lags, integration costs and break-even horizons.
- Risk registers and regulatory compliance checklists that align operational controls with the latest rules affecting IT service providers and their clients.
- Financial impact tools: TCO comparators, build-vs-buy calculators and vendor selection decision trees calibrated to industry archetypes.
To preserve strategic value, the report intentionally reserves granular regional and subsegment-level revenue tables for the full release. Readers looking to obtain deep segmentation, vendor-specific revenue splits, and downloadable model files should refer to the report subscription page.
Competitive landscape — how leading firms are positioning in 2026
The report profiles incumbent global firms and highlights how each is adapting to the era of AI, cloud-native architectures, and elevated resilience requirements. High-level takeaways:
- Accenture remains the archetypal integrator: broad industry reach, deep transformation practice, and aggressive investment in cloud, AI and industry cloud platforms. Its emphasis on outcome-oriented delivery makes it a frequent partner for large-scale modernization programs.
- IBM Consulting is doubling down on real-time data and hybrid cloud capabilities. A major strategic step in 2026 was the completion of a transformational acquisition to bolster real-time streaming and enterprise AI workflows — a capability set that materially alters turnkey options for clients building event-driven architectures.
- Deloitte continues to blend traditional consulting excellence with technology modernization services, focusing on enterprise systems modernization, cybersecurity and risk advisory — attractive for highly regulated sectors.
- Capgemini and other engineering-led firms are leveraging strong domain engineering capabilities and industry-specific IP to win complex digital engineering and cloud migration engagements.
- Tata Consultancy Services, Cognizant, Infosys and Wipro maintain scale advantages in global delivery, hybrid sourcing models and broad platform partnerships, enabling cost-competitive, rapid delivery for extensive transformation programs.
Collectively these providers define the strategic “shelf” from which most large enterprises will procure services. Yet our market-concentration analysis shows meaningful headroom for specialized firms and new entrants to capture value in niche verticals and emerging capabilities.
Recent developments shaping 2026 strategy
- Strategic M&A has accelerated platform consolidation and capability stacking across consulting leaders. Notably, a leading global consulting firm completed a high-profile acquisition in early 2026 to secure real-time data streaming and enterprise AI orchestration capabilities — a deal with significant implications for how clients source streaming architectures and agentic AI solutions.
- Smaller scale strategic acquisitions continue to re-bundle managed services, cybersecurity, and regional delivery capabilities — enabling acquirers to rapidly fill capability gaps without multiyear organic build plans.
- Regulatory milestones (described below) and ongoing labor-market pressures are driving buyers to re-evaluate risk allocation in contracts and to build stronger compliance and audit capabilities into sourcing decisions.
Regulation, labor and resilience: non-negotiable variables for 2026
Two regulatory changes and labor-market forces demand special attention in 2026 planning:
- The EU’s Digital Operational Resilience Act (DORA) has come fully into force and now applies to financial institutions and relevant ICT service providers, raising the bar for operational risk management, testing regimes and supplier oversight. Enterprises operating in, or serving, the EU must re-baseline vendor due diligence and contractual compliance clauses.
- U.S. regulatory measures governing bulk sensitive personal data transactions have expanded compliance obligations for relevant systems and providers, increasing the need for technical controls and forensic record-keeping across service deliveries.
- On the labor side, salary inflation pressures continue to bite. Average increases across technology roles are modest but meaningful; specialized skills in AI/ML and data engineering are commanding outsized premium growth compared with general IT roles. These dynamics influence near-term project costing, retention strategies and the attractiveness of managed or outcome-based contracts.
What this means for enterprise buyers — five prioritized actions for 2026
- Re-balance vendor portfolios to manage integration and regulatory risk: favor modular contracts that allow rapid substitution of components (platform, implementation partner, and managed services) without vendor lock-in.
- Price in talent premium and design for skill obsolescence: include reskilling clauses, success-based milestones and supplier retention incentives where AI and data-science expertise are central to outcomes.
- Adopt hybrid contracting models that shift more upside to outcome metrics: clients should pilot outcome-linked pricing in greenfield or low-risk domains and expand as measurement fidelity increases.
- Embed resilience and compliance KPIs into procurement checklists: require evidence of regulatory program maturity, third-party testing and incident response readiness as part of standard RFP evaluations.
- Use scenario-based forecasting to stress-test plans: leverage the report’s scenario lanes to assess implications of accelerated AI adoption, protracted supply constraints or regulatory escalations on program timing and economics.
Methodology and rigor
PW Consulting’s market model is built on a blend of bottom-up vendor analysis, top-down macro drivers, primary interviews with vendor and buyer executives, and triangulation against public filings and proprietary engagement data. Historical series cover 2020–2025, with forward-looking forecasts for 2026–2032 across three market scenarios. The report includes downloadable model worksheets for licensed clients, enabling customized sensitivity analysis aligned with a buyer’s industry, geography and technology focus.
How to use this report in your 2026 planning
Leaders planning budgets and procurement in 2026 should use this study as both a risk matrix and a prioritization instrument. The document converts large-scale market growth forecasts into recommended investment horizons, vendor engagement sequencing, and contract design patterns that reduce integration risk while preserving upside participation in AI and cloud modernization value pools.
Because the most valuable parts of the analysis are the tactical tables, vendor scorecards and downloadable financial models, PW Consulting has structured this release as a “strategic preview.” The preview demonstrates our evidence-based approach and the direction of travel without disclosing all segment-level ratios and provider revenues — encouraging investors and enterprise buyers to access the full report for operationalized intelligence.
Next steps
- Download the full report and model package from PW Consulting’s report page to obtain segment-level forecasts, vendor revenue splits, and industry-specific playbooks.
- Schedule a briefing with our senior advisors to translate findings into a one-page action plan tailored to your organization’s 2026 budget cycle.
- Engage our vendor due diligence service to validate proposed provider selections against compliance, resilience and delivery-readiness criteria.
In an environment where technology-driven advantage increasingly depends on data velocity, resilience and talent orchestration, the choices made in 2026 will compound through the decade. PW Consulting’s Computer Consulting Services Market — 2026 Edition equips leaders with the foresight and practical tools to convert market growth into defensible, measurable outcomes.
For detailed analysis of this topic, please visit the official page: Computer Consulting Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: International Business Travel Insurance Market Set to Reach USD 31,402.92 Million by 2032 from USD 18,500 Million in 2025, Growing at a 7.85% CAGR
By pmarketresearch, 2026-08-12
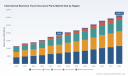
International Business Travel Insurance Plans Market — Strategic Briefing for 2026 Decision‑Makers
Executive summary
PW Consulting’s new market study on International Business Travel Insurance Plans (base year 2025) frames an actionable roadmap for corporate buyers, insurers, brokers, and investors preparing strategic moves in 2026. The market reached approximately USD 18,500 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 7.85% over the forecast horizon, reaching north of USD 31,000 Million by the end of the 2026–2032 forecast window. This trajectory reflects a sustained rebound in cross‑border corporate mobility, intensifying duty‑of‑care obligations, and steady product innovation from incumbent and challenger insurers.
Bots Market
Why this matters for 2026 corporate strategy
For multinational employers and mobility program leads, the marketplace is shifting from commodity indemnity to integrated duty‑of‑care platforms. Procurement decisions in 2026 should treat travel insurance not as a risk transfer line item but as a component of employee safety, compliance, and continuity planning. The market growth and concentration dynamics we document have three implications:
Worldwide Food Grade Ethanol Market
- Buyers can expect more modular offerings (policy + assistance + tech), enabling tighter integration with corporate EHS and HR systems. Procurement frameworks must therefore evaluate API interoperability, response SLAs, and provider network depth alongside price.
- The mix of competition and scale — reflected in a moderately concentrated market structure — means selective partnerships and affinity models will yield outsized returns for insurers that can combine underwriting strength with distribution reach.
- Regulatory and reputational pressures (duty of care) are increasing the total cost of non‑compliance; insurance solutions that demonstrably support risk mitigation and repatriation logistics will command premium positioning.
Market trajectory and what the numbers hide (and reveal)
The headline growth (CAGR ~7.85%) masks important structural shifts that senior leaders must calibrate for 2026:
Battery Intercell Connectors Market
- Volume recovery and premium normalization — business travel volumes are recovering past pandemic troughs and are trending toward new steady states driven by hybrid work and resumed international assignments. Insurers should prepare for a steady uptick in frequency of short‑term international trips and a parallel increase in multi‑trip demand models.
- Value migration to services — emergency medical evacuation, 24/7 global assistance, visa and logistics support, and telemedicine are increasingly where differentiation and margin reside. Pricing for pure indemnity is under pressure; value is captured through services and ecosystem play.
- Concentration offers consolidation opportunities — the market’s top players capture a meaningful share of premium, but there remains room for regional specialists and technology‑led entrants to carve defensible niches. M&A and partnership activity in 2026 will likely target capability gaps rather than scale alone.
Competitive landscape — what incumbents are doing now
The report profiles leading global players and examines how their strategic moves alter competitive dynamics. Highlights from our competitive assessment:
- Allianz Partners — remains a strategic bellwether: recent partnerships and board‑level hires signal an intent to deepen affinity under‑writing and policy distribution, particularly in mature travel markets. Their membership in industry councils demonstrates a play for policy influence and traveler confidence leadership.
- Specialists such as International Medical Group (IMG) and Seven Corners — are capitalizing on international medical expertise and customizable plans for employer groups, emphasizing evacuation, cross‑border medical continuity, and group administration.
- Distribution‑focused players like Travelex Insurance Services and Travel Guard (AIG) — leverage expansive broker and retail channels to bundle travel protection with corporate travel programs, while competing on claims turnaround and customer experience.
- Newer or differentiated entrants (e.g., Berkshire Hathaway Travel Protection, Blue Cross Blue Shield Global Solutions) — stress claims efficiency, global network access, and integrated group health linkages to win corporate accounts that demand consolidated healthcare administration across jurisdictions.
Our company profiles include underwriting posture, distribution strategy, claims benchmarks, and partnership maps. Recent publicly disclosed moves — including strategic alliances and senior appointments announced in April 2026 — are analyzed for their knock‑on effects on capacity, distribution and product development cycles.
Practical intelligence contained in the full report
PW Consulting’s report is built as a decision tool, not just a reference volume. The operational modules most relevant to 2026 decisions include:
- Scenario‑based market sizing and sensitivity analysis that link travel volume scenarios to premium pools and loss ratios.
- Go‑to‑market playbooks for carriers and brokers: product blueprints, recommended pricing levers, channel segmentation, and partner selection criteria.
- Procurement templates for corporate buyers: RFP language, SLA templates for assistance services, and evaluation scorecards that prioritize duty‑of‑care outcomes.
- Claims and service benchmarking: response time standards, repatriation cost comparisons, and digital claims conversion metrics.
- Regulatory and compliance checklist across major employer jurisdictions, with operational implications for travel policy design and insurer selection.
- M&A and partnership opportunity maps informed by market concentration metrics and capability gaps; a practical guide for buyers and investors targeting tuck‑ins or capability acquisitions in 2026.
Dynamics shaping product and procurement decisions
Three dynamics deserve special attention in 2026:
- Duty of care as procurement lever — employers are increasingly using insurance selection to discharge legal and reputational responsibilities to travelers. Contract clauses and verification procedures tied to evacuation capabilities and medical network access will be standard.
- Data‑driven underwriting & pricing — carriers that invest in travel pattern analytics and telemedicine integrations will be able to segment risk more precisely, offering bespoke premiums for high‑frequency traveler cohorts and corporate programs.
- Digital customer experience — rapid triage, multilingual assistance, and frictionless claims are becoming non‑negotiable for corporations focused on traveler retention and satisfaction. Investment in digital frontdoors and API connectivity will shorten sales cycles and improve renewal economics.
Strategic recommendations for 2026
For corporate buyers
- Reframe travel insurance RFPs to emphasize outcome metrics (evacuation time, medical network breadth, employee satisfaction) rather than premium alone.
- Bundle insurance procurement with duty‑of‑care technology and medical assistance providers to create an integrated supplier ecosystem with shared KPIs.
- Run a two‑track supplier strategy: retain a core global partner for scale and compliance, and pilot niche specialists for high‑risk or high‑value itineraries.
For insurers and brokers
- Prioritize partnerships that fill capability gaps (medical networks, telemedicine, local assistance) instead of chasing commoditized distribution.
- Invest in data platforms that support traveler‑level risk scoring and dynamic pricing for frequent travelers and corporate book-of‑business accounts.
- Use SLAs and service design as a competitive weapon — demonstrable evacuation and claims performance will attract corporate renewals.
For investors and M&A teams
- Target bolt‑on acquisitions that add assistance capabilities, telemedicine, or regional medical networks rather than broad top‑line purchases; these deliver quicker integration value.
- Monitor regulatory changes in employer duty‑of‑care obligations — such shifts create windows for rapid re‑pricing and re‑contracting across corporate portfolios.
How PW Consulting’s report saves you time and risk in 2026
Decision‑makers told us they need fast, actionable inputs that translate to contracts, product roadmaps, and M&A theses. Our report combines primary interviews, underwriting benchmarks, claims analytics, and legal/regulatory mapping to produce playbooks rather than abstract forecasts. Where necessary for commercial discretion, we summarize high‑level trends and frameworks in this briefing while retaining the granular segmentation, detailed pricing models, and deal‑level data exclusively in the full report.
Next steps — where to find the full intelligence
This briefing is designed to clarify the strategic choices facing buyers, carriers and investors in 2026. To access the complete market segmentation, granular regional and application volumes, pricing matrices, and downloadable procurement templates, please visit the report landing page. The full dataset and actionable appendices are available to subscribers and licensed purchasers; they include company scorecards, modeled scenarios, and an exportable RFP pack ready for immediate use.
Closing
International business travel insurance is moving from policy issuance to integrated traveler protection. For leaders making 2026 decisions, the question is no longer whether to buy or sell coverage, but how to architect partnerships, platforms and processes that turn insurance into a corporate capability for safe, compliant, and resilient international operations. PW Consulting’s International Business Travel Insurance Plans Market report provides the field guide to do exactly that — with the granular evidence and operational templates reserved in the full publication to support immediate execution.
For detailed analysis of this topic, please visit the official page: International Business Travel Insurance Plans Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rugged Notebooks Market to Hit USD 375M by 2032 at 7.5% CAGR
By pmarketresearch, 2026-07-30
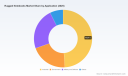
Rugged Notebooks Market: Strategic Primer for 2026 Decision-Makers
As organizations push computing out of controlled office environments and into frontline operations—from energy exploration and heavy industry to first responders and defense—rugged notebooks have shifted from niche specialty items to strategic assets. PW Consulting’s latest market study uses 2025 as a base year and combines a five-year historical view (2020–2025) with a forward-looking forecast window (2026–2032). At the macro level, the market has expanded from roughly USD 180 million in 2020 to about USD 235 million in 2025, and is modeled to continue growing at a compound annual growth rate (CAGR) of approximately 7.5% through 2032, reaching the high‑hundreds of millions in aggregate revenue by the end of the forecast period.
Rugged Notebooks Market
Why this study matters for 2026 strategic decisions
-
Operational computing is moving to the edge. The growth trajectory quantified in this study underscores the strategic imperative for capital equipment budgets to reflect edge-first computing needs—durability, sustained performance in harsh environments, and manageability across dispersed sites.
Rugged Notebooks Market -
Technology inflection points are compressing product cycles. Vendors are integrating higher-performance GPUs, AI-capable silicon, and new sensor/communications stacks into purpose-built chassis. The report translates these technological inflections into actionable procurement windows and replacement cycles.
Rugged Notebooks Market -
Fragmentation creates tactical openings. Market concentration metrics in the study highlight a fragmented vendor landscape, which creates opportunities for procurement-led consolidation, preferred-vendor relationships, and strategic partnerships rather than single-vendor lock-in.
Market trajectory and macro drivers
The historical arc captured in our study shows demand recovering and accelerating post-2021 as industries prioritized resilience and mobile digitization. This momentum is expected to sustain through the 2026–2032 forecast window. Three structural tailwinds drive that trajectory: operational digitalization across industrial sectors, geopolitical and compliance-driven re-investment in certified hardware for defense and public safety, and the integration of AI workloads into field computing—requiring higher thermal and compute envelopes in durable form factors.
On the flip side, supply-chain complexity for specialized materials and the cost-sensitivity of many enterprise buyers create persistent pressure on margins and product roadmaps. The net effect is a market that grows steadily but rewards vendors and buyers who align product capability, total cost of ownership (TCO), and certification confidence.
Technology and use-case evolution
-
AI-enabled field computing: Vendors are introducing AI-ready models with enhanced GPU and accelerator support to run inference and lightweight training at the edge. We document how thermal design, power delivery, and chassis materials are being re-engineered to support these workloads without sacrificing ruggedness.
-
Connectivity and platform convergence: Rugged devices are increasingly offered with multi-mode wireless stacks and enterprise-class OS options, supporting both Android and Windows ecosystems for field software portability and lifecycle support.
-
Standards and certifications matter more than ever: Compliance to military standards (e.g., MIL-STD family), ingress protection (IP66/IP67), electromagnetic compatibility, and industry-specific certifications (ATEX for explosive atmospheres) are decisive procurement criteria for public sector and industrial buyers. Our study maps certification requirements to common field scenarios so buyers can match specifications to operational risk tolerances.
Competitive landscape—what incumbents and challengers are doing
The vendor map in our research identifies global OEMs and specialized players that span a spectrum from broad IT incumbents to focused rugged specialists. A few high‑level patterns emerge:
-
Platform-scaled incumbents are adding rugged portfolios: Large systems vendors are extending enterprise-grade platforms into ruggedized variants, integrating higher-performance GPUs and validated ISV stacks to address data‑intensive field workflows.
-
Specialists are driving certification and mechanical innovation: Companies focused exclusively on rugged systems are advancing chassis materials, ingress protection, and MIL-STD certifications—differentiators that remain compelling for defense, emergency services, and heavy industry.
-
Product releases are converging around AI-readiness and modularity: Recent product announcements demonstrate a clear trend—new models tout AI acceleration, modular I/O, and enhanced docking solutions for vehicle and site-based deployments.
To illustrate recent momentum without divulging proprietary sizing data: notable developments include AI-focused product introductions from specialist OEMs and mainstream vendors equipping rugged lines with discrete GPUs to serve geospatial analysis, predictive maintenance, and real-time situational awareness applications. These moves reshape procurement criteria and raise the bar for device lifecycle planning.
Implications for procurement, product, and risk strategies in 2026
-
Procurement: Move beyond unit price. Our recommended procurement frameworks prioritize certified configurations, integrated support SLAs, spare‑parts logistics, and clear firmware update paths. Procurement teams should institutionalize TCO models that include field failure rates, mean time to repair, and software maintenance costs.
-
Product strategy: Invest selectively in AI-capable hardware. For organizations with on‑device inference needs, evaluate devices based on sustained thermal performance under expected computation profiles—not just peak benchmark numbers.
-
Integration & lifecycle: Standardize docking, mounting, and network authentication layers to reduce integration friction across vehicle, site, and wearable deployments. Coordinate firmware and security patch strategies across device lifecycles to avoid field vulnerabilities.
-
Supplier risk management: Given market fragmentation and specialized component sourcing, map supplier concentration for chassis, processors, and wireless modules. Build multi-sourcing or dual-sourcing contingencies for critical components.
-
M&A & alliance playbooks: For vendors aiming to scale, consolidation remains a valid route—our concentration metrics suggest that targeted bolt-ons (certification expertise, docking ecosystems, or regional service footprints) can deliver strategic scale faster than organic R&D alone.
Key risks and mitigation levers
-
Capability mismatch risk: Procurers may over-spec devices for occasional use-cases. Mitigate by mapping true duty cycles and environmental exposures to certification thresholds and by piloting fleet segments before broad rollouts.
-
Obsolescence and technical debt: The pace of AI and connectivity changes can render devices functionally obsolete even when mechanically sound. Use modular expansion paths and open standard docking/interconnects to extend device utility.
-
Regulatory and compliance drift: Standards evolve—maintain an active certification gap analysis and allocate budget for re-certification where mission-critical operations depend on compliance.
What this PW Consulting report delivers (operational depth, teaser)
The full study provides a granular playbook designed for leaders making hard choices in 2026. Highlights include:
-
A validated historical market reconstruction (2020–2025) and a detailed forecast (2026–2032) using scenario-driven demand models—anchored to the 2025 base year.
-
Vendor benchmarking that covers product roadmaps, certification portfolios, service footprints, and product-level positioning for the leading OEMs and challengers.
-
Procurement templates: RFP language, TCO calculators, and configuration-checklists tailored to common industrial, government, and defense workflows.
-
Integration playbooks: Docking, vehicle-mounting, and fleet management templates plus recommended firmware and patch governance processes.
-
Investment and M&A decision tools: Target scoring matrices, consolidation scenarios, and near-term value-capture levers.
-
Scenario analyses: Stress tests for supply-chain disruptions, component shortages, and accelerated AI adoption—translated into prioritized mitigation paths.
To preserve the commercial value of the study and to comply with our “trailer” principle, we purposely withhold the full subsegment-by-region and subsegment-by-application datasets from this public primer. These datasets—together with company-level revenue splits, price curves, and supply-chain exposure tables—are included in the full report and are essential for granular procurement and investment decisions.
Practical next steps for 2026
-
Prioritize pilots that pair AI-capable rugged devices with high-value edge use-cases (predictive maintenance, real-time imagery analysis, or mobile command post operations) to assess real-world thermal and lifecycle performance.
-
Reassess vendor SLAs and spare-part contracts to shorten mean repair times and improve uptime for frontline assets.
-
Formalize certification requirements for procurement to avoid expensive retrofits and ensure field safety and compliance from day one.
-
Use the study’s vendor benchmarking and TCO instruments to create a two-year roadmap for fleet renewal, aligning refresh cycles with technology windows rather than vendor promotion schedules.
Conclusion: The rugged notebooks market is maturing into a strategic layer of enterprise infrastructure. The market’s steady growth—rooted in rising edge workloads and stricter operational requirements—creates both opportunity and complexity for buyers and suppliers. Organizations that treat rugged devices as long‑lived, mission‑critical platforms, and that align procurement, engineering, and security disciplines, will extract disproportionate operational value.
For the full dataset, company-level profiles, and the implementation toolkit that supports these strategic choices, visit the PW Consulting report landing page and download the comprehensive market study and appendices.
For detailed analysis of this topic, please visit the official page: Rugged Notebooks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Video Editing Software Market Set for 5.6% CAGR — Growth & Opportunities
By pmarketresearch, 2026-07-30
Video Editing Software Market 2026: Strategic Imperatives for Enterprise Decision‑Makers
As enterprises prepare investment roadmaps for 2026, the video editing software market presents both incremental opportunity and disruptive risk. Our latest PW Consulting market research—anchored to a 2025 base year and projecting through 2032—shows a stable, mid‑single‑digit growth trajectory (CAGR: 5.6%) and a market that is neither a commoditized afterthought nor a winner‑takes‑all arena. This briefing explains why the study matters for C‑suite and business‑line leaders, what practical intelligence the full report delivers, and how to convert insights into decisive actions while highlighting the competitive battleground where platform owners, hardware partners, and specialist vendors are jockeying for advantage.
Video Editing Software Market
Why this research matters for 2026 decisions
Three converging trends make the timing of investment decisions critical: the mainstreaming of generative and AI‑assisted editing, renewed hardware acceleration (GPU and edge encoding), and a shift in buyer economics as subscription, one‑time, and hybrid licensing models coexist. Taken together, these dynamics create a strategic inflection point for content producers, post‑production houses, broadcasters, tech OEMs and enterprise IT organizations.
Video Editing Software Market
-
Capital allocation: The study quantifies how near‑term ROI profiles change when AI‑driven automation reduces time‑to‑final by editing stage, and it models TCO under different deployment choices (cloud, on‑premise, hybrid).
Video Editing Software Market -
Vendor selection: We analyze vendor competitive moats and show where to spend to avoid vendor lock‑in while capturing productivity gains—critical when evaluating multi‑year contracts in 2026.
-
Partner and ecosystem plays: The report identifies partnership archetypes—hardware acceleration partners, cloud platform integrators, plugin and effects ecosystems—that materially affect performance and go‑to‑market speed.
What the PW Consulting report delivers (practical, actionable content)
-
Market forecast and scenario planning: A seven‑year forecast (2026–2032) with base‑case and two stress scenarios. These let decision‑makers test capital expenditure and subscription strategies against different AI adoption curves and macroeconomic outcomes.
-
Vendor scorecards: Independent, comparative assessments across product capability, AI maturity, integration flex, pricing, and enterprise support. Vendor profiles include strategic positioning, product roadmaps, and partnership openness.
-
Use‑case economics: Layered P&L impact models for common enterprise workflows—training and certification programs, centralized media asset management, and distributed creator networks—showing breakeven and payback windows.
-
Technology deep dives: Practical advice on GPU acceleration, codec selection, cloud rendering economics, and latency‑sensitive workflows with checklist‑style guidance for procurement and devops teams.
-
M&A and investment framework: Screening criteria for targets (capability adjacencies, IP defensibility, customer stickiness), valuation sensitivities, and integration playbooks tailored to the video editing stack.
-
Implementation roadmaps: Step‑by‑step adoption blueprints for enterprises at three maturity stages—pilot, scale, and global rollout—paired with risk registers and mitigation strategies.
-
Training and skills guide: A pragmatic mapping of certification programs and training investments to competency outcomes, helping L&D and hiring teams prioritize where to upskill staff.
Market posture and competitive landscape — who matters and why
The market exhibits moderate concentration: a cluster of dominant incumbents hold strong enterprise mindshare while a broad long tail competes on price, niche features, ease‑of‑use, or regional reach. The report’s CR3 and CR5 assessments indicate industry leaders maintain meaningful influence over standards, integrations, and customer expectations, but emerging entrants with AI first‑mover advantages are creating pockets of disruption.
Key players profiled in the research include:
-
Adobe Inc. — A premium, professional platform that leverages deep creative workflows and increasingly integrates generative AI to automate repetitive tasks and accelerate content creation. Adobe’s ecosystem and cross‑product integrations remain a high‑value proposition for enterprise customers seeking end‑to‑end creative suites.
-
Apple Inc. — A differentiated offering optimized for a specific hardware and OS ecosystem, combining high performance on native hardware with a mix of one‑time licensing and new subscription approaches. Apple’s recent product cadence signals a sharpened focus on creator monetization and platform bundling.
-
Blackmagic Design — An all‑in‑one suite converging editing, color, VFX and audio with expanded AI tools. The combination of a professional feature set and aggressive pricing makes it a compelling alternative for post‑production workflows.
-
Avid Technology — A staple in broadcast and enterprise post‑production, focused on media asset management and high‑reliability enterprise workflows, where stability and deep integrations with broadcast pipelines are prioritized over consumer UX gloss.
-
Corel, Sony, Wondershare, CyberLink, TechSmith, Magix — Each occupies well‑defined niches from consumer ease‑of‑use to specialized capture‑to‑edit workflows; they are important for channel strategies and for enterprises that require multi‑tiered supplier approaches.
Recent industry shifts to factor into 2026 strategy
-
AI acceleration and vendor responses: Major vendors are rolling out generative and automation capabilities to reduce manual editing labor and shorten delivery cycles. These changes are already reshaping purchasing criteria from purely feature lists to productivity metrics tied to creative throughput.
-
Hardware and GPU partnership dynamics: Hardware vendors are showcasing accelerated, AI‑enabled workflows at industry shows, which is compressing time‑to‑final for high‑res and effects‑heavy projects. Enterprises should consider co‑investment models with hardware suppliers for GPU‑intensive rendering.
-
Licensing model evolution: New subscription options and hybrid licensing models are appearing alongside traditional perpetual licenses. The result is greater flexibility—but also more complexity when forecasting spend and modeling user churn in 2026 budgets.
-
Certification and labor market signals: Professional certification programs are maturing across major vendors, affecting procurement (preferred‑vendor skilling) and the cost of talent. Our research quantifies the time and financial investment needed to reach operational competency under different vendor stacks.
Strategic recommendations for enterprise decision‑makers
-
Adopt a use‑case first vendor evaluation. Map vendor capabilities to prioritized workflows (e.g., newsrooms, marketing studios, training content) and use PW Consulting’s vendor scorecards to shortlist vendors that meet productivity KPIs, not just feature checklists.
-
Design for mixed deployments. Most organizations will operate hybrid mixes of cloud and on‑premise tools; embed interoperability and data portability requirements into procurement language now to avoid costly rip‑and‑replace later.
-
Invest in GPU and workflow acceleration selectively. For high‑throughput content environments, co‑funding hardware acceleration or edge rendering capabilities can produce compelling TCO improvements—our case models show where this makes sense versus cloud scale‑up.
-
Prioritize skills and certification alignment. Make vendor certification a gating factor in large rollouts and quantify onboarding costs in the business case. Certification investments often unlock higher utilization and shorter ramp times.
-
Run acquisition and partnership scenarios off standardized KPIs. Use the report’s M&A framework to screen targets that complement platform capabilities—focus on API openness, data models, and customer retention signals rather than headline revenues alone.
How to use this report as a decision support tool
PW Consulting’s Video Editing Software Market study is designed to be both a strategic compass and an operational playbook. Executives will find high‑level scenario outputs and concentration metrics useful for portfolio and procurement decisions; product and IT teams will use the TCO models, integration checklists and vendor scorecards to structure RFPs and pilots. The full report also contains the granular segmentation tables and proprietary indices that support our conclusions—information we intentionally reserve for the primary release to preserve the integrity of our competitive benchmarks.
In a market growing steadily at a mid‑single‑digit compound rate and experiencing rapid capability shifts driven by AI and hardware acceleration, the cost of indecision can be measured not only in capex forgone but in time‑to‑market and creative capacity lost. PW Consulting’s research equips leaders to convert market signals into concrete 2026 plays: selective investment in acceleration, disciplined vendor evaluation, and skills‑first adoption strategies that protect flexibility while harvesting productivity gains.
Contact PW Consulting to access the full report and to schedule a tailored briefing. The detailed datasets, scenario models, and vendor benchmarking tools will enable your team to make evidence‑based commitments in 2026 with confidence.
For detailed analysis of this topic, please visit the official page: Video Editing Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Digital Scent Technology Market — A 2026 Strategic Primer for Corporate Decision‑Makers
As PW Consulting’s lead industry analyst, I present an executive introduction to our latest market study on digital scent technology — a nascent but fast‑growing segment that is shifting how brands, healthcare providers, and platform owners think about multisensory experiences. This brief distills the most consequential strategic insights for decisions you will make in 2026, explains why the topic matters to boards and business units today, and outlines how our full report converts market intelligence into executable plans.
Digital Scent Technology Market
Market trajectory: what the headline numbers tell you
Between 2020 and 2025 the market for digital scent technologies scaled from roughly USD 98.5 million to about USD 160.0 million, reflecting early commercial traction across immersive media, wellness, and B2B environmental monitoring. Our forecast, using a 2025 base and a 2026–2032 horizon, projects continuing expansion at a compound annual growth rate (CAGR) of 9.8%, with the market approaching approximately USD 305.8 million by 2032. These figures signal a transition from pilot‑led deployments toward repeatable commercial models for hardware, consumables and recurring software/analytics services.
Digital Scent Technology Market
Why corporate leaders should care in 2026
-
First‑mover option value: Organizations that clarify platform vs. component playbooks now can capture outsized licensing, content‑monetization and consumable revenue streams as adoption scales.
Digital Scent Technology Market -
Adjacency monetization: For consumer electronics, automotive, and VR/AR companies, olfactory layers unlock differentiated user engagement and new pricing tiers without replacing core products.
-
Clinical and workplace risk management: In healthcare and industrial monitoring, scent sensors are emerging as actionable inputs for diagnostic workflows and environmental safety programs — creating B2B procurement opportunities that require compliance and validation roadmaps.
-
Regulatory and reputational exposure: As the technology moves into public spaces, organizations must bake compliance, ethics, and data governance into product design and go‑to‑market strategies to avoid brand and liability costs.
Key market forces and implications
-
Technology maturation and modularization: Miniaturization of scent emitters and advances in digital scent encoding are lowering integration costs. Strategic implication: prioritize flexible APIs and consumable supply chains to maximize lifetime customer value.
-
Platform economics vs. point solutions: Market winners will either build platforms that aggregate content and hardware partners or specialize as component suppliers to platform players. Firms should define which side of the stack they intend to own before committing large R&D budgets.
-
Regulatory friction and standardization gaps: European air quality, worker safety and consumer‑safety directives already shape device requirements. The absence of global standards increases compliance complexity and slows enterprise procurement. Companies must invest in certification roadmaps and active engagement with standards bodies.
-
Public policy and incentive dynamics: Government and industry support in markets such as Japan and China accelerates innovation and can create localized centers of excellence. Multinationals should map incentive landscapes to optimize R&D and manufacturing footprints.
Competitive landscape — what to watch
The market today remains fragmented, with a mix of specialist hardware vendors, sensor innovators, AI‑first scent designers, and integrators serving different verticals. Several companies illustrate the range of strategic approaches:
-
Osmo — an AI‑first olfactory intelligence company focusing on scent design and digitization. Recent strategic moves (including a major financing round, an accelerated patent program, and a new manufacturing and R&D facility announced in 2026) indicate a bid to scale IP and production capabilities. Competitive implication: Osmo is pursuing an ecosystem play that could raise barriers to entry for molecule‑level innovation and accelerate commercialization partnerships in fragrance, healthcare and safety.
-
Aromajoin Corporation — offers controllable scent devices aimed at immersive marketing and aromatherapy. Their product focus is attractive to brands looking for marketing differentiation; partners should evaluate device interoperability and content creation toolsets.
-
Aroma Bit, Inc. — developing CMOS‑based odor imaging sensors and e‑nose solutions. If sensor imaging proves cost‑effective at scale, Aroma Bit’s tech could become a standard input for real‑time scent detection across quality control and medical diagnostics use cases.
-
Sensigent LLC — provides nanosensor OEM solutions. Their approach is particularly relevant to industrial and environmental monitoring, where the integration of sensors with robust telemetry is key.
-
Deepscent Inc. — focuses on scalable digital scent streaming and AI orchestration for B2B venues like retail and hospitality — a model emphasizing subscription revenue and content pipelines.
-
Inhalio Inc. — develops dry‑air scent delivery systems with AI platforms for homes and automotive applications, indicating a route to volumetric consumer scale through embedded device partners.
-
OVR Technology — integrates scent displays with immersive experiences, signaling a content‑centric strategy that complements VR/AR platform players.
For corporate strategists, the competitive lesson is twofold: (1) differentiate through proprietary content, IP, and platform relationships rather than hardware alone, and (2) assess whether to compete on vertical specialization (e.g., clinical monitoring) or horizontal enablement (developer tools, APIs, consumables supply).
What our full report delivers (practical, actionable content)
The full PW Consulting study is designed as an operational playbook for business leaders. Key deliverables include:
-
Robust market sizing and growth scenarios (TAM/SAM/SOM frameworks) anchored to transparent methodology, with historical baselines and 2026–2032 forecast paths to stress‑test investment timing.
-
Use‑case profit models and unit‑economics templates that quantify device margins, consumable economics, and software‑as‑a‑service trajectories for VR/AR, healthcare, retail and environmental monitoring applications.
-
Regulatory and standards playbook tailored for product teams, including required testing matrices, certification pathways, and recommended compliance milestones for major jurisdictions.
-
IP and patent landscape synthesis, with strategic options for licensing, cross‑licensing, and defensive portfolios—plus a roadmap for R&D prioritization and partnering with fragrance chemistry labs.
-
Vendor scorecards and a partner matchmaking matrix that compare hardware suppliers, sensor providers, and integrators across technical and commercial metrics.
-
Scenario‑based strategic roadmaps and M&A target shortlists for acquirers and scaleups seeking inorganic growth or capability augmentation.
Note: this executive introduction intentionally omits detailed regional, application and type share tables that are included in the full report; those granular splits and datasets are available in our online portal for subscribing clients.
Recommended strategic moves in 2026 (prioritized)
-
For platform owners and OEMs: run two‑quarter integration sprints with leading scent‑API vendors to validate UX assumptions and consumable supply logistics. Negotiate flexible, non‑exclusive arrangements that preserve optionality.
-
For component and sensor specialists: accelerate standards alignment and seek strategic OEM partnerships; prioritize robust calibration methods and interoperability to become the preferred pneumatic/sensor supplier for enterprise buyers.
-
For fragrance houses and content creators: develop digitization pipelines and licensing models for reusable scent assets; collaborate with AI partners to create catalogues of safe, regulatory‑friendly scent profiles.
-
For healthcare and industrial buyers: launch controlled pilots that pair scent detection with established diagnostics or safety metrics; predefine regulatory submission paths and evidence requirements before scaling procurement.
-
Ethics and risk mitigation: implement privacy policies for scent‑derived data, informed consent flows for consumer installations, and robust safety testing protocols for scent emissions.
How to use this study in your 2026 planning cycle
Use the study to convert uncertainty into staged bets. Short‑term (0–12 months): validate product concepts through focused pilots and secure interoperability commitments from hardware and consumable partners. Medium‑term (12–36 months): move from pilot to commercialized bundles (hardware + consumable + analytics), refining pricing and channel strategy. Long‑term (36+ months): pursue platform consolidation, licensing of proprietary scent assets, or targeted M&A to acquire missing capabilities.
PW Consulting’s full report contains the granular regional, application, and type‑level datasets, vendor matrices, and scenario models needed to implement these steps. The contribution of that granular intelligence is twofold: it reduces executional risk by identifying the highest‑velocity revenue pools, and it creates a defensible roadmap for resource allocation and partnership negotiations.
Closing
Digital scent technology is evolving from a niche novelty into a strategic lever for differentiated experiences, operational monitoring and therapeutic innovation. With established growth momentum and an expanding set of use cases, 2026 is a pivotal year to define your position in the stack. PW Consulting’s full market study translates the market’s macro trajectory — from a modest base in 2020 to rapid expansion through the next decade — into clear, actionable choices for leadership teams. Access the full dataset and implementation playbooks on our site to convert this market opportunity into measurable business outcomes.
For detailed analysis of this topic, please visit the official page: Digital Scent Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com