

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: New report predicts Epoxy Electrocoating market to expand at a 4.5% CAGR through 2032

Epoxy Electrocoating Market — Strategic Outlook 2026: PW Consulting Insights
Executive summary
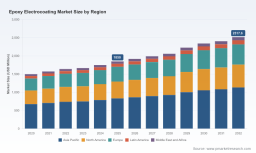
PW Consulting’s latest Epoxy Electrocoating Market report (base year 2025) delivers a forward-looking toolkit for executives making high-stakes sourcing, manufacturing, and M&A decisions in 2026. After tracking the market through the 2020–2025 historical window, our model forecasts the global epoxy e-coat market to grow at a steady compound annual growth rate (CAGR) of 4.5% over the 2026–2032 forecast horizon. The market expanded from about USD 1.5 billion in 2020 to roughly USD 1.85 billion in 2025, and is projected to surpass USD 2.5 billion by 2032 under our central scenario.
XR Imaging Waveguide Market
This release summarizes the strategic implications that matter most to C-suite and business unit leaders — while reserving proprietary, line-item segmentation and scenario tables for the full report. Consider this a high-fidelity preview: deep enough to guide near-term strategy, intentionally limited to encourage direct access to the complete dataset and decision-support materials.
Kraft Interleaving Paper Market
Market trajectory and macro drivers
-
Demand resilience and steady growth: The epoxy electrocoating market has shown consistent expansion through 2020–2025, reflecting its entrenched role in corrosion protection for automotive OEMs, industrial machinery, and durable appliances. Our base-year assessment (2025) captures the market at approximately USD 1.85 billion, with a prudent baseline projection rising to ~USD 1.92 billion in 2026 and continuing to reach roughly USD 2.52 billion by 2032 under the central-case 4.5% CAGR.
Spaceborne Multibeam Antennas Market -
Cost and supply-chain volatility: Raw-material headwinds have intensified in early 2026. Regional epoxy resin price observations in April 2026 show material cost pressures — for example, Northeast Asia pricing near USD 2.62/kg (up ~23% year-over-year in our monitoring window) and increases in Europe and the Middle East that have meaningfully raised input cost baselines. These moves are being reinforced by corporate pricing actions across the value chain.
-
Policy and trade friction: Recent regulatory actions — notably final affirmative determinations by the U.S. Department of Commerce in antidumping and countervailing duty investigations on epoxy resins from several producing countries — introduce a new layer of trade risk and cost of goods considerations for manufacturers and importers in 2026.
Dynamics shaping 2026 decisions
-
Input-cost passthrough and margin management: Manufacturers and OEMs must reassess price models and contractual terms. Our scenario workbench demonstrates that in most cases, immediate margin pressure from April–June 2026 epoxy resin inflation cannot be absorbed without operational levers or renegotiated supply agreements.
-
Sourcing diversification vs. consolidation: The ecosystem remains moderately concentrated; the top three suppliers control a clear majority of market supply, with the top five exerting near-three-quarters influence on the market. This concentration amplifies supplier-side pricing influence but also presents targeted partnership opportunities for buyers seeking security of supply.
-
Technology and application transitions: Low-temperature curing formulations, lower-voltage application systems, and sustainability-focused chemistries are gaining traction. Investments in these technology vectors reduce energy intensity and support OEM sustainability commitments — a material consideration for capex prioritization in 2026.
-
Regional demand shifts: Growth momentum in Asia-Pacific continues to shape capacity decisions, while mature markets sustain demand through replacement and aftermarket activity. Our full report quantifies these flows at a granular level and models cross-border trade under varying tariff and duty scenarios.
Competitive landscape — what the leading players are doing
We examined the strategies and capabilities of leading suppliers and technology owners to map competitive advantage across production footprint, product performance, and customer intimacy. Highlights:
-
PPG Industries, Inc. (Pittsburgh, USA) — maintains leadership through its Powercron cathodic epoxy line, emphasizing high corrosion resistance and uniform film build. Its global customer relationships in industrial and automotive sectors are a structural advantage for volume and innovation partnerships.
-
Axalta Coating Systems (Philadelphia, USA) — positions its AquaEC cathodic epoxy series toward OEMs prioritizing corrosion protection and mechanical performance. Axalta’s strength is in integrated coatings systems and OEM program alignment.
-
BASF SE (Ludwigshafen, Germany) — leverages its CathoGuard family and broad materials science platform. Recent greenfield and expansion investments underscore BASF’s intention to support automotive OEM re-shoring and regional capacity needs.
-
The Sherwin-Williams Company (Cleveland, USA) — focuses on heavy machinery and industrial applications with formulations engineered for edge coverage and substrate performance in challenging environments.
-
Nippon Paint and Kansai Paint (Japan) — together with regional specialists like KCC Corporation and Tatung Fine Chemicals, they offer strong local capabilities across Asia, often emphasizing eco-efficiency, low-temperature curing, and supply reliability for OEMs in the region.
Recent corporate actions matter for 2026 strategy. For example, BASF commissioned a new automotive coatings plant in Münster in late 2025 and expanded e-coat capacity in Mangalore in early 2026 — moves that change competitive capacity and customer lead-times in Europe and South Asia. Meanwhile, DIC Corporation’s April 2026 announcement of price increases for epoxy resins and curing agents is a leading indicator of continued upstream price volatility. These events reinforce the need for dynamic supplier engagement and scenario modeling.
What’s inside the full PW Consulting report (actionable, practitioner-focused)
The full report is structured to move teams from insight to action during 2026 planning cycles. Key deliverables include:
-
Market size and forecast model (2020–2032) with company-level roll-ups and scenario toggles — base case, upstream shock case, and accelerated electrification case.
-
Supplier risk heatmap — assessing concentration, geopolitical exposure, feedstock sensitivity, and capacity elasticity at the production-node level.
-
Cost-pass-through and margin impact calculators — sector-specific templates that allow procurement and finance teams to stress-test contracts against realistic resin-price trajectories.
-
Technology readiness assessment — performance, capex implications, and time-to-market for low-temp curing, low-VOC chemistries, and application equipment.
-
M&A and partnership playbook — prioritized target archetypes (bolt-on capacity, technology play, or channel access) and valuation benchmarks informed by concentration metrics and recent transactions.
-
Regulatory and trade impact matrix — mapping antidumping/countervailing outcomes and likely near-term trade frictions to procurement and distribution strategies.
Note: This summary intentionally preserves proprietary segmentation tables and unit economics that are included exclusively in the paid report. Those granular figures — including formulation-, region-, and end-use breakouts by revenue and volume — are available to subscribers and clients through our secure portal.
Practical recommendations for 2026
-
Immediate (0–3 months): Stabilize supply through dual-sourcing of critical resins, activate price-index clauses where feasible, and run the PW Consulting cost-pass-through calculator against current contracts to quantify near-term margin exposure.
-
Near-term (3–9 months): Prioritize small-capex pilot projects to qualify low-temperature and low-VOC formulations with key OEM customers. These pilots both reduce energy usage and create differentiators for future contracts.
-
Medium-term (9–18 months): Revisit capacity plans in light of upstream inflation and trade measures. For producers, we recommend a staged investment approach — conditional on validated off-take agreements or supply contracts that mitigate feedstock risk.
-
Strategic (12–36 months): Assess targeted M&A to plug strategic gaps — for example, acquiring regional formulation expertise or localized production to minimize tariff/duty exposures and logistics costs under stressed trade scenarios.
Methodology and data integrity
Our analysis synthesizes primary interviews with supply-chain executives, OEM procurement data, regional trade statistics, company filings, and independent price monitoring. The report uses the calendar year 2025 as the base year, covers the historical period 2020–2025, and presents a 2026–2032 forecast scenario set. Financials are reported in USD, with market values expressed in millions for comparability.
Why this matters for 2026
Two simultaneous trends define the strategic landscape for epoxy electrocoating in 2026: persistent upstream cost volatility and accelerating technology-driven product differentiation. Companies that act early — securing supply, validating energy-efficient formulations, and aligning with OEM decarbonization priorities — will convert transient pressures into durable competitive advantage. Conversely, passive actors risk margin compression and supply disruption as raw-material and trade dynamics evolve.
Next steps
PW Consulting’s full Epoxy Electrocoating Market report contains the granular segmentation, downloadable model files, supplier scorecards, and bespoke advisory options designed to support procurement, operations, and strategy teams through 2026 planning cycles. For tailored briefings, scenario workshops, or to acquire the complete dataset and modeling tools, please contact PW Consulting through our corporate channels or visit our report landing page for subscription details.
For detailed analysis of this topic, please visit the official page: Epoxy Electrocoating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com