

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Computer Consulting Services Market to Expand from USD 865.0 Billion in 2025 to USD 1.50 Trillion by 2032 at an 8.2% CAGR — North America Leads with USD 327.7B; Top‑5 Firms Hold 24.1%

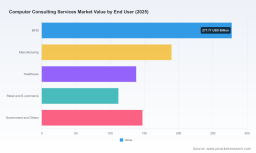
Computer Consulting Services Market 2026: Strategic Imperatives from PW Consulting
PW Consulting’s newest market research release, Computer Consulting Services Market — 2026 Edition, frames a decisive moment for CIOs, procurement chiefs, and private equity investors planning enterprise technology allocations this year. With a robust compound annual growth rate (CAGR) of 8.2% and a global services market that reached an estimated USD 865.0 Billion in our 2025 base year, our analysis projects sustained expansion through 2032 — underlining both scale and the structural shifts reshaping how organizations buy, contract and consume IT consulting services.
Digital Trunking Intercom Market
Why this report matters for 2026 decision cycles
Corporate technology roadmaps for 2026 must confront three simultaneous forces: accelerated adoption of AI and real-time data architectures; intensifying regulatory and operational resilience requirements; and continued pressure on total cost of ownership driven by labor market dynamics. PW Consulting’s study synthesizes these forces into a pragmatic playbook. The report translates macro growth (with a forecasted pathway extending to a projected market north of USD 1.5 Trillion by 2032) into tangible, time-bound actions — enabling leaders to prioritize investments that preserve optionality while capturing near-term value.
Totem Pole PFC Market
What the research reveals (high level)
- Market momentum is structural, not cyclical: the services market has expanded markedly since 2020 and our base-year analysis shows continued year-on-year growth into 2026 and beyond.
- Vendor ecosystems are expanding around data, cloud and AI platforms. Strategic M&A, platform plays and managed offerings are re-shaping competitive advantage — creating new choices but also new integration and governance imperatives for buyers.
- The provider landscape remains fragmented. Top-tier firms capture a meaningful share, yet overall concentration is moderate (our concentration analysis shows a three-firm and five-firm share that underlines available room for specialist players and new entrants).
- Regulation and labor cost trends are now first-order considerations in vendor selection, contract design, and sourcing strategy.
Practical content inside the report
This is a practitioner’s report designed to inform active procurement and strategy decisions in 2026. Core deliverables include:
AI Tool for Aviation Market
- Proprietary market-sizing and forecast model (historical 2020–2025, forecast 2026–2032) with scenario lanes for macro, technology adoption and regulatory shock events.
- A vendor assessment framework with scored dimensions for capability depth, delivery footprint, platform partnerships, IP controls, pricing models and migration velocity.
- Go-to-market playbooks and procurement templates tailored for enterprise buyers — including phased engagement models (proof-of-concept → scale → run), outcome-based contracting clauses, and performance SLAs mapped to business outcomes.
- Technology adoption timelines and capability roadmaps for AI, hybrid cloud, real-time data streaming, and cybersecurity, highlighting typical adoption lags, integration costs and break-even horizons.
- Risk registers and regulatory compliance checklists that align operational controls with the latest rules affecting IT service providers and their clients.
- Financial impact tools: TCO comparators, build-vs-buy calculators and vendor selection decision trees calibrated to industry archetypes.
To preserve strategic value, the report intentionally reserves granular regional and subsegment-level revenue tables for the full release. Readers looking to obtain deep segmentation, vendor-specific revenue splits, and downloadable model files should refer to the report subscription page.
Competitive landscape — how leading firms are positioning in 2026
The report profiles incumbent global firms and highlights how each is adapting to the era of AI, cloud-native architectures, and elevated resilience requirements. High-level takeaways:
- Accenture remains the archetypal integrator: broad industry reach, deep transformation practice, and aggressive investment in cloud, AI and industry cloud platforms. Its emphasis on outcome-oriented delivery makes it a frequent partner for large-scale modernization programs.
- IBM Consulting is doubling down on real-time data and hybrid cloud capabilities. A major strategic step in 2026 was the completion of a transformational acquisition to bolster real-time streaming and enterprise AI workflows — a capability set that materially alters turnkey options for clients building event-driven architectures.
- Deloitte continues to blend traditional consulting excellence with technology modernization services, focusing on enterprise systems modernization, cybersecurity and risk advisory — attractive for highly regulated sectors.
- Capgemini and other engineering-led firms are leveraging strong domain engineering capabilities and industry-specific IP to win complex digital engineering and cloud migration engagements.
- Tata Consultancy Services, Cognizant, Infosys and Wipro maintain scale advantages in global delivery, hybrid sourcing models and broad platform partnerships, enabling cost-competitive, rapid delivery for extensive transformation programs.
Collectively these providers define the strategic “shelf” from which most large enterprises will procure services. Yet our market-concentration analysis shows meaningful headroom for specialized firms and new entrants to capture value in niche verticals and emerging capabilities.
Recent developments shaping 2026 strategy
- Strategic M&A has accelerated platform consolidation and capability stacking across consulting leaders. Notably, a leading global consulting firm completed a high-profile acquisition in early 2026 to secure real-time data streaming and enterprise AI orchestration capabilities — a deal with significant implications for how clients source streaming architectures and agentic AI solutions.
- Smaller scale strategic acquisitions continue to re-bundle managed services, cybersecurity, and regional delivery capabilities — enabling acquirers to rapidly fill capability gaps without multiyear organic build plans.
- Regulatory milestones (described below) and ongoing labor-market pressures are driving buyers to re-evaluate risk allocation in contracts and to build stronger compliance and audit capabilities into sourcing decisions.
Regulation, labor and resilience: non-negotiable variables for 2026
Two regulatory changes and labor-market forces demand special attention in 2026 planning:
- The EU’s Digital Operational Resilience Act (DORA) has come fully into force and now applies to financial institutions and relevant ICT service providers, raising the bar for operational risk management, testing regimes and supplier oversight. Enterprises operating in, or serving, the EU must re-baseline vendor due diligence and contractual compliance clauses.
- U.S. regulatory measures governing bulk sensitive personal data transactions have expanded compliance obligations for relevant systems and providers, increasing the need for technical controls and forensic record-keeping across service deliveries.
- On the labor side, salary inflation pressures continue to bite. Average increases across technology roles are modest but meaningful; specialized skills in AI/ML and data engineering are commanding outsized premium growth compared with general IT roles. These dynamics influence near-term project costing, retention strategies and the attractiveness of managed or outcome-based contracts.
What this means for enterprise buyers — five prioritized actions for 2026
- Re-balance vendor portfolios to manage integration and regulatory risk: favor modular contracts that allow rapid substitution of components (platform, implementation partner, and managed services) without vendor lock-in.
- Price in talent premium and design for skill obsolescence: include reskilling clauses, success-based milestones and supplier retention incentives where AI and data-science expertise are central to outcomes.
- Adopt hybrid contracting models that shift more upside to outcome metrics: clients should pilot outcome-linked pricing in greenfield or low-risk domains and expand as measurement fidelity increases.
- Embed resilience and compliance KPIs into procurement checklists: require evidence of regulatory program maturity, third-party testing and incident response readiness as part of standard RFP evaluations.
- Use scenario-based forecasting to stress-test plans: leverage the report’s scenario lanes to assess implications of accelerated AI adoption, protracted supply constraints or regulatory escalations on program timing and economics.
Methodology and rigor
PW Consulting’s market model is built on a blend of bottom-up vendor analysis, top-down macro drivers, primary interviews with vendor and buyer executives, and triangulation against public filings and proprietary engagement data. Historical series cover 2020–2025, with forward-looking forecasts for 2026–2032 across three market scenarios. The report includes downloadable model worksheets for licensed clients, enabling customized sensitivity analysis aligned with a buyer’s industry, geography and technology focus.
How to use this report in your 2026 planning
Leaders planning budgets and procurement in 2026 should use this study as both a risk matrix and a prioritization instrument. The document converts large-scale market growth forecasts into recommended investment horizons, vendor engagement sequencing, and contract design patterns that reduce integration risk while preserving upside participation in AI and cloud modernization value pools.
Because the most valuable parts of the analysis are the tactical tables, vendor scorecards and downloadable financial models, PW Consulting has structured this release as a “strategic preview.” The preview demonstrates our evidence-based approach and the direction of travel without disclosing all segment-level ratios and provider revenues — encouraging investors and enterprise buyers to access the full report for operationalized intelligence.
Next steps
- Download the full report and model package from PW Consulting’s report page to obtain segment-level forecasts, vendor revenue splits, and industry-specific playbooks.
- Schedule a briefing with our senior advisors to translate findings into a one-page action plan tailored to your organization’s 2026 budget cycle.
- Engage our vendor due diligence service to validate proposed provider selections against compliance, resilience and delivery-readiness criteria.
In an environment where technology-driven advantage increasingly depends on data velocity, resilience and talent orchestration, the choices made in 2026 will compound through the decade. PW Consulting’s Computer Consulting Services Market — 2026 Edition equips leaders with the foresight and practical tools to convert market growth into defensible, measurable outcomes.
For detailed analysis of this topic, please visit the official page: Computer Consulting Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com