

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Gate Driver ICs for BLDC Motors Market to Grow at 8% CAGR from 2026, Reaching USD 2,825 Million by 2032

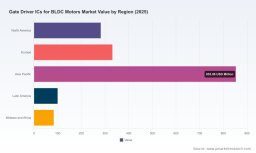
Gate Driver ICs for BLDC Motors Market: Strategic Intelligence to Shape 2026 Decisions
PW Consulting today releases an executive preview of our in-depth market research report, Gate Driver ICs for BLDC Motors Market — Base Year 2025, Forecast 2026–2032. Designed for C-suite executives, product leaders, procurement heads, and M&A teams, this analysis translates semiconductor dynamics into concrete commercial actions for 2026. The study synthesizes supply-chain realities, technology trajectories, and competitive maneuvering to show where value pools will open and which tactical moves will preserve or expand advantage.
Temperature Assured Packaging Market
Why this report matters in 2026
The gate driver IC market for BLDC motors has entered a phase of steady expansion underpinned by electrification trends across automotive, industrial and consumer segments. Our model—with 2025 as the base year—indicates the market is growing at a compound annual growth rate (CAGR) of approximately 8.0% across the 2026–2032 forecast window. By the end of the forecast period the market is projected to materially exceed the 2025 base, reflecting scaling adoption of integrated driver architectures, higher-voltage silicon and SiC enablement, and the rising complexity of motor controls in next‑generation systems.
Enfuvirtide for Injection Market
For decision-makers in 2026, this report turns growth projections into strategic choices: where to invest in product development, which supplier risks to hedge, how to calibrate pricing and inventory strategies, and what M&A or partnership moves will strengthen position without overpaying for commoditized offerings.
AI Software Tools for Finance Market
Report scope and practical deliverables
PW Consulting’s study is intentionally operational. Beyond high‑level forecasts, the report equips clients with:
- Actionable supplier risk matrices that combine lead‑time, material concentration and regulatory exposure to identify single‑point failures and prioritise dual‑sourcing or localised inventory strategies.
- Technology adoption roadmaps mapping gate driver feature sets (isolated drivers for SiC, integrated MOSFET SmartMCDs, built‑in microcontrollers and sensorless control) to specific end‑market requirements and certification barriers (automotive/industrial functional safety).
- Decision frameworks for make vs. buy, with TCO modelling that factors in rising component pricing, extended MOSFET lead times and qualification costs for automotive-grade parts.
- A competitive playbook profiling product portfolios, go‑to‑market moves, and design‑win trajectories for the major incumbent and challenger suppliers.
- Scenario analyses that stress-test strategic plans against supply-chain shocks (export controls on critical materials, tariff changes) and component price swings—enabling board‑level contingency planning.
Competitive landscape — what to watch
The market exhibits moderate concentration: the top three suppliers account for a meaningful share of addressed revenues, while the top five increases that footprint further—indicative of a market where scale and product breadth matter, but opportunities remain for niche specialists and design‑win focused entrants.
- Infineon Technologies — Strong in automotive-grade solutions, Infineon’s MOTIX™ family and recent isolated drivers for SiC motor drives underscore a strategy centered on functional safety and high‑voltage applications. Their product positioning makes them a preferred partner for OEMs that prioritise ISO 26262 compliance.
- STMicroelectronics — With integrated families that span driver + MCU and options pushing into high‑voltage domains, ST’s approach is focused on platform plays for industrial and automotive customers seeking consolidated supplier relationships.
- Toshiba Electronic Devices & Storage — Recent SmartMCD and gate driver sampling programs indicate Toshiba is accelerating into integrated MOSFET‑plus‑driver architectures for automotive body and small motor applications; these moves lower system BOM and accelerate time‑to‑market for OEMs.
- ROHM Semiconductor — ROHM’s medium‑voltage driver launches and production ramps highlight a strong play in mid‑voltage electrification use cases, particularly where robust thermal and switching performance are required.
- Texas Instruments, Allegro, Microchip, Renesas, onsemi and Monolithic Power Systems — Each of these firms brings differentiated strengths: integrated current sensing, Hall/sensor interfaces, AEC‑qualified predrivers, and platform breadth. For system houses, supplier mosaics will increasingly blend these capabilities to meet both cost and functional targets.
Our competitive chapter not only inventories product capabilities and recent launches, but also assesses route‑to‑qualification timelines, software and toolchain maturity, and the strength of distribution and design‑support programs—elements that ultimately decide design‑win velocity.
Supply chain realities that must influence 2026 strategy
Macro and micro supply risks are central to the report’s recommendations. Notable pressures include:
- Raw material and export control exposure: Restrictions on materials critical to advanced semiconductors (e.g., gallium and germanium) have introduced a new layer of geopolitical supply fragility. Firms that rely on single‑source supply lines for these inputs face escalating strategic risk.
- Component lead times: MOSFET lead times averaged well into the 20s of weeks in early 2026, with some suppliers reaching 30+ weeks. These elongated cycles materially affect production planning for gate driver assemblies and favour earlier allocation and forward buys.
- Pricing environment: Several semiconductor suppliers announced price increases in the spring of 2026. Procurement organisations must balance margin protection with end‑market price sensitivity, and consider hedging and contract structures that share risk between OEMs and supplier partners.
- Regulatory constraints: Export controls and tariffs continue to shape sourcing strategies—driving investments in alternative supply bases, on‑shore assembly, and qualification of second‑source semiconductor suppliers for critical platforms.
Our report includes a prioritized list of mitigations and procurement playbooks tailored to different company profiles: OEMs with high design rigidity, contract manufacturers with variable customer mixes, and pure‑play semiconductor vendors seeking to insulate their fabs and revenue streams.
Technology trajectories and product innovation
Technical evolution in gate driver ICs is happening along several axes that will determine which product architectures capture the most value:
- Integration — SmartMCD approaches (MOSFET integrated with driver and sometimes MCU) reduce system BOM and assembly complexity, enabling compact designs for automotive pumps, fans and small motors. This integration shortens design cycles but raises qualification intensity for safety‑critical applications.
- SiC and isolation — Isolated gate drivers designed for SiC switching and higher system voltages are becoming essential where efficiency and power density are priorities, particularly in traction and high‑power industrial applications.
- Embedded intelligence — Gate drivers with integrated current sensing, self‑diagnostics and sensorless control expand the system value proposition and support higher levels of predictive maintenance and closed‑loop control.
- Functional safety and certifications — ISO 26262 compliance and AEC‑Q100 qualification remain gating factors for large OEM opportunities; suppliers that fast‑track documentation and compliance testing unlock system design wins.
We evaluate these contrasts at a modular level to advise whether to pursue bespoke silicon, licensed IP, or partner integrations based on cost, time‑to‑market and end‑market margins.
Strategic recommendations for 2026
For executive teams making resource allocation decisions this year, PW Consulting’s core recommendations are:
- Prioritise dual‑sourcing and local buffer inventories for MOSFETs and other long‑lead inputs. Lead‑time volatility is a near‑term reality and proactive inventory strategies reduce churn at the system level.
- Invest selectively in integration where it unlocks systems margin and shortens OEM qualification cycles, but avoid overpaying for generic integration in commoditizing segments.
- Accelerate certification roadmaps (functional safety and automotive qualifications) now—design cycles and validation windows are long; early investment yields disproportionate returns in design‑win capture.
- Use partnership and JV structures to mitigate geopolitical exposure to critical materials and to create regionalised capacity for high‑volume automotive and industrial customers.
- Evaluate M&A targets that bring differentiated IP (SiC‑grade isolation, advanced sensorless algorithms) rather than scale for scale’s sake; the market’s concentration profile rewards specialty assets that expand accessible end‑market addressability.
What the preview intentionally withholds — and why
True to the “trailer” principle of this preview, we are sharing directional, high‑confidence insights while withholding the granular, monetised splits and proprietary scenario matrices that form the core of the full report. Detailed regional and application breakdowns, segment‑level revenue tables, and supplier market‑share time series are available exclusively in the full document. This is deliberate: precise segmentation and share data are the actionable intelligence organisations need for contractual negotiations, supplier scorecards and M&A valuations.
Clients and readers who require those specifics can access them via the full report, which contains downloadable tables, an interactive forecast model and supplier benchmarking tools tailored to different buyer profiles.
Next steps
PW Consulting’s Gate Driver ICs for BLDC Motors Market report is structured to support immediate strategic planning cycles in 2026. If you are preparing 2026 R&D budgets, supplier negotiations, or M&A pipeline screens, the full report will provide the calibrated inputs and scenario tools to prioritise and quantify your options. For organisations seeking bespoke workshops, PW Consulting also offers targeted briefings that overlay your company’s product roadmap and supplier footprint onto the market model to generate a 90‑day action plan.
To learn more about the full report and to schedule a briefing, please visit the PW Consulting website or contact our market intelligence team. The complete study contains the proprietary segment tables, supplier scorecards, and downloadable forecast models that underpin the strategic recommendations outlined here.
About PW Consulting
PW Consulting specialises in translating semiconductor and power‑electronics markets into board‑level strategy. Our research combines deep technical competency with rigorous commercial analysis to deliver workplans that executives can act on within quarter‑to‑quarter planning cycles.
For detailed analysis of this topic, please visit the official page: Gate Driver ICs for BLDC Motors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com