

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Rugged Notebooks Market to Hit USD 375M by 2032 at 7.5% CAGR

Rugged Notebooks Market: Strategic Primer for 2026 Decision-Makers
As organizations push computing out of controlled office environments and into frontline operations—from energy exploration and heavy industry to first responders and defense—rugged notebooks have shifted from niche specialty items to strategic assets. PW Consulting’s latest market study uses 2025 as a base year and combines a five-year historical view (2020–2025) with a forward-looking forecast window (2026–2032). At the macro level, the market has expanded from roughly USD 180 million in 2020 to about USD 235 million in 2025, and is modeled to continue growing at a compound annual growth rate (CAGR) of approximately 7.5% through 2032, reaching the high‑hundreds of millions in aggregate revenue by the end of the forecast period.
Rugged Notebooks Market
Why this study matters for 2026 strategic decisions
-
Operational computing is moving to the edge. The growth trajectory quantified in this study underscores the strategic imperative for capital equipment budgets to reflect edge-first computing needs—durability, sustained performance in harsh environments, and manageability across dispersed sites.
Rugged Notebooks Market -
Technology inflection points are compressing product cycles. Vendors are integrating higher-performance GPUs, AI-capable silicon, and new sensor/communications stacks into purpose-built chassis. The report translates these technological inflections into actionable procurement windows and replacement cycles.
Rugged Notebooks Market -
Fragmentation creates tactical openings. Market concentration metrics in the study highlight a fragmented vendor landscape, which creates opportunities for procurement-led consolidation, preferred-vendor relationships, and strategic partnerships rather than single-vendor lock-in.
Market trajectory and macro drivers
The historical arc captured in our study shows demand recovering and accelerating post-2021 as industries prioritized resilience and mobile digitization. This momentum is expected to sustain through the 2026–2032 forecast window. Three structural tailwinds drive that trajectory: operational digitalization across industrial sectors, geopolitical and compliance-driven re-investment in certified hardware for defense and public safety, and the integration of AI workloads into field computing—requiring higher thermal and compute envelopes in durable form factors.
On the flip side, supply-chain complexity for specialized materials and the cost-sensitivity of many enterprise buyers create persistent pressure on margins and product roadmaps. The net effect is a market that grows steadily but rewards vendors and buyers who align product capability, total cost of ownership (TCO), and certification confidence.
Technology and use-case evolution
-
AI-enabled field computing: Vendors are introducing AI-ready models with enhanced GPU and accelerator support to run inference and lightweight training at the edge. We document how thermal design, power delivery, and chassis materials are being re-engineered to support these workloads without sacrificing ruggedness.
-
Connectivity and platform convergence: Rugged devices are increasingly offered with multi-mode wireless stacks and enterprise-class OS options, supporting both Android and Windows ecosystems for field software portability and lifecycle support.
-
Standards and certifications matter more than ever: Compliance to military standards (e.g., MIL-STD family), ingress protection (IP66/IP67), electromagnetic compatibility, and industry-specific certifications (ATEX for explosive atmospheres) are decisive procurement criteria for public sector and industrial buyers. Our study maps certification requirements to common field scenarios so buyers can match specifications to operational risk tolerances.
Competitive landscape—what incumbents and challengers are doing
The vendor map in our research identifies global OEMs and specialized players that span a spectrum from broad IT incumbents to focused rugged specialists. A few high‑level patterns emerge:
-
Platform-scaled incumbents are adding rugged portfolios: Large systems vendors are extending enterprise-grade platforms into ruggedized variants, integrating higher-performance GPUs and validated ISV stacks to address data‑intensive field workflows.
-
Specialists are driving certification and mechanical innovation: Companies focused exclusively on rugged systems are advancing chassis materials, ingress protection, and MIL-STD certifications—differentiators that remain compelling for defense, emergency services, and heavy industry.
-
Product releases are converging around AI-readiness and modularity: Recent product announcements demonstrate a clear trend—new models tout AI acceleration, modular I/O, and enhanced docking solutions for vehicle and site-based deployments.
To illustrate recent momentum without divulging proprietary sizing data: notable developments include AI-focused product introductions from specialist OEMs and mainstream vendors equipping rugged lines with discrete GPUs to serve geospatial analysis, predictive maintenance, and real-time situational awareness applications. These moves reshape procurement criteria and raise the bar for device lifecycle planning.
Implications for procurement, product, and risk strategies in 2026
-
Procurement: Move beyond unit price. Our recommended procurement frameworks prioritize certified configurations, integrated support SLAs, spare‑parts logistics, and clear firmware update paths. Procurement teams should institutionalize TCO models that include field failure rates, mean time to repair, and software maintenance costs.
-
Product strategy: Invest selectively in AI-capable hardware. For organizations with on‑device inference needs, evaluate devices based on sustained thermal performance under expected computation profiles—not just peak benchmark numbers.
-
Integration & lifecycle: Standardize docking, mounting, and network authentication layers to reduce integration friction across vehicle, site, and wearable deployments. Coordinate firmware and security patch strategies across device lifecycles to avoid field vulnerabilities.
-
Supplier risk management: Given market fragmentation and specialized component sourcing, map supplier concentration for chassis, processors, and wireless modules. Build multi-sourcing or dual-sourcing contingencies for critical components.
-
M&A & alliance playbooks: For vendors aiming to scale, consolidation remains a valid route—our concentration metrics suggest that targeted bolt-ons (certification expertise, docking ecosystems, or regional service footprints) can deliver strategic scale faster than organic R&D alone.
Key risks and mitigation levers
-
Capability mismatch risk: Procurers may over-spec devices for occasional use-cases. Mitigate by mapping true duty cycles and environmental exposures to certification thresholds and by piloting fleet segments before broad rollouts.
-
Obsolescence and technical debt: The pace of AI and connectivity changes can render devices functionally obsolete even when mechanically sound. Use modular expansion paths and open standard docking/interconnects to extend device utility.
-
Regulatory and compliance drift: Standards evolve—maintain an active certification gap analysis and allocate budget for re-certification where mission-critical operations depend on compliance.
What this PW Consulting report delivers (operational depth, teaser)
The full study provides a granular playbook designed for leaders making hard choices in 2026. Highlights include:
-
A validated historical market reconstruction (2020–2025) and a detailed forecast (2026–2032) using scenario-driven demand models—anchored to the 2025 base year.
-
Vendor benchmarking that covers product roadmaps, certification portfolios, service footprints, and product-level positioning for the leading OEMs and challengers.
-
Procurement templates: RFP language, TCO calculators, and configuration-checklists tailored to common industrial, government, and defense workflows.
-
Integration playbooks: Docking, vehicle-mounting, and fleet management templates plus recommended firmware and patch governance processes.
-
Investment and M&A decision tools: Target scoring matrices, consolidation scenarios, and near-term value-capture levers.
-
Scenario analyses: Stress tests for supply-chain disruptions, component shortages, and accelerated AI adoption—translated into prioritized mitigation paths.
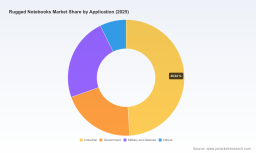
To preserve the commercial value of the study and to comply with our “trailer” principle, we purposely withhold the full subsegment-by-region and subsegment-by-application datasets from this public primer. These datasets—together with company-level revenue splits, price curves, and supply-chain exposure tables—are included in the full report and are essential for granular procurement and investment decisions.
Practical next steps for 2026
-
Prioritize pilots that pair AI-capable rugged devices with high-value edge use-cases (predictive maintenance, real-time imagery analysis, or mobile command post operations) to assess real-world thermal and lifecycle performance.
-
Reassess vendor SLAs and spare-part contracts to shorten mean repair times and improve uptime for frontline assets.
-
Formalize certification requirements for procurement to avoid expensive retrofits and ensure field safety and compliance from day one.
-
Use the study’s vendor benchmarking and TCO instruments to create a two-year roadmap for fleet renewal, aligning refresh cycles with technology windows rather than vendor promotion schedules.
Conclusion: The rugged notebooks market is maturing into a strategic layer of enterprise infrastructure. The market’s steady growth—rooted in rising edge workloads and stricter operational requirements—creates both opportunity and complexity for buyers and suppliers. Organizations that treat rugged devices as long‑lived, mission‑critical platforms, and that align procurement, engineering, and security disciplines, will extract disproportionate operational value.
For the full dataset, company-level profiles, and the implementation toolkit that supports these strategic choices, visit the PW Consulting report landing page and download the comprehensive market study and appendices.
For detailed analysis of this topic, please visit the official page: Rugged Notebooks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com