

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: ITSM Software Market Poised for 16.45% CAGR Through 2032

IT Service Management (ITSM) Software Market — Strategic Outlook for 2026
Executive summary
As enterprises move from episodic digitization to continuous digital operations, IT Service Management (ITSM) has shifted from a ticketing tool to an operational nervous system. PW Consulting’s latest ITSM Software Market research establishes a clear, data-driven foundation for strategic choices in 2026. The sector is on a steep trajectory — growing from a 2025 baseline and projected to expand at a compound annual growth rate (CAGR) of 16.45% through the 2026–2032 forecast window — with the global market approaching roughly USD 624 million by 2032. This growth is being driven by the convergence of AI-led automation, multi-cloud operations, and an urgent enterprise need to operationalize compliance and privacy at scale.
IT Service Management (ITSM) Software Market
Why this research matters for 2026 decision-makers
- Investment timing: With the market accelerating quickly, 2026 is a pivot year for CAPEX vs OPEX choices. The CAGR implies significant supplier innovation and pricing pressure; early adopters of AI-first ITSM can capture outsized operational savings, while late movers risk higher migration costs and displacement.
- Vendor selection and lock-in risk: The market is meaningfully concentrated — the leading vendors capture a majority of spend — which raises strategic supplier risk considerations for large enterprises. Choosing a platform today affects integration budgets, data residency choices, and multi-year service models.
- Operational transformation: ITSM platforms are becoming execution engines for autonomous work. Decisions taken in 2026 will determine whether organizations reap the promised labor efficiencies (ticket deflection and faster mean-time-to-resolution) or inherit brittle automation that amplifies governance risk.
Market trajectory and what the headline numbers mean
Our report uses a 2025 base year and a comprehensive historical window (2020–2025) to project the sector to 2032. The headline CAGR of 16.45% is not abstract — it reflects rapid re-platforming to cloud-native architectures, premiuming for AI-enabled capabilities, and expanding use cases beyond classical incident and asset management. Practically, organizations should expect escalating vendor feature churn, more aggressive bundled AI pricing, and richer ecosystem tie‑ins with observability, ITOM, and HR/service productivity stacks.
IT Service Management (ITSM) Software Market
For executives, the key takeaway is dual: the market’s unit economy and feature set are evolving quickly enough that procurement cycles shortened in 2024–25 will look out of date by 2027; and the total addressable value for ITSM-related operational savings (labor, incident costs, business downtime) materially grows as platforms automate higher-value workflows.
IT Service Management (ITSM) Software Market
Dynamics shaping the market
- AI-driven labor economics: Industry benchmarking shows AI-enabled ITSM capabilities can deliver 30–60% ticket deflection and 40–90% faster resolution on routine workloads. These efficiencies are reshaping staffing models for centralized and distributed IT teams and creating new ROI profiles for platform investments.
- Data privacy and compliance burden: Enterprises report a sharp rise in data subject requests and regulatory oversight, which elevates demand for ITSM platforms that embed audit trails, consent handling, and automated subject-request workflows. Compliance is now a functional requirement, not an optional bolt-on.
- Cloud and hybrid infrastructure pressures: As operations span multiple clouds and edge environments, buyers prioritize solutions that provide real-time service visibility, SLA assurance, and cross-domain automation. Cloud-first offerings are increasingly the default for large-scale deployments.
- Standards and governance: Adoption of ITIL v4 and ISO-aligned processes remains high; however, vendors are racing to reconcile these frameworks with autonomous workflows, necessitating governance layers (AI control towers, explainability, verified playbooks) to pass audit and compliance gates.
- Pricing divergence: The market exhibits bifurcated pricing dynamics — competitive mid-market offers lower entry points, while enterprise-grade, AI-enabled suites command substantially higher per-agent economics. This divergence complicates TCO modeling for heterogeneous estates.
Segmentation — what to watch (without the raw splits)
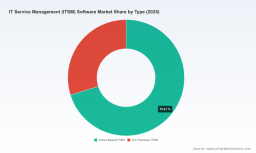
The market is commonly segmented by deployment model (cloud vs on-prem), functional modules (incident, configuration, asset, change, and others), and geography. In this preview we intentionally do not disclose the detailed split statistics — the full report contains the complete segmentation tables and forward-looking share scenarios. For strategic planning, the critical insight is not merely which segment is largest today, but which combinations of deployment model, functionality, and procurement model create sustainable advantage for your organization by 2028.
Competitive landscape — leaders, challengers, and strategic moves
The vendor landscape combines global platform leaders, specialized challengers, and systems integrators delivering verticalized solutions. Market concentration metrics indicate that top-tier vendors hold a commanding position, while a larger set of mid-market and niche vendors compete on speed, verticalization, and cost.
- ServiceNow: As a platform leader, ServiceNow continues to push enterprise-grade autonomy with initiatives introduced in early 2026 (Autonomous Workforce, EmployeeWorks, and the Otto unified AI experience). These moves accelerate the convergence of conversational AI, governed workflows, and cross-domain automation — creating both opportunity and lock-in for large enterprises that can invest in deep platform integrations.
- BMC: BMC’s Helix line emphasizes proactive, AI-enabled operations across complex, multi-cloud estates. Their focus on change management and operational resiliency appeals to regulated industries.
- Atlassian (Jira Service Management): Positioned strongly with developer-centric ops and DevOps toolchain integration, recent feature updates reinforce its pull for engineering-led service models and agile incident response.
- Ivanti: Ivanti’s recent release of agentic conversational AI capabilities and modern UX enhances its competitive posture for organizations prioritizing rapid automation adoption and modern user experiences.
- Freshworks, ManageEngine, Microsoft, Broadcom, and others: Each vendor pursues differentiated routes — mid-market speed, unified workplace integrations, or deep ITOM tie-ins. Partnerships and OEM relationships (for example, enterprise deployments powered by third-party platforms) are recurring themes.
Recent product launches and feature cycles are more consequential than in prior periods — they materially change integration scopes and operational playbooks. The report annotates these developments with practical implications for procurement, architecture, and migration sequencing.
What’s inside the full PW Consulting report (practical contents, not just high-level commentary)
- Actionable vendor selection frameworks that map business objectives (cost reduction, customer experience, compliance) to platform capabilities and sourcing models.
- Implementation playbooks and phased migration templates for re-platforming from legacy or on-prem stacks to cloud-native, AI-enabled ITSM, including change-management checklists to protect service continuity.
- TCO and ROI models that incorporate labor deflection, incident-cost avoidance, and automation uplift — configurable for industry and estate complexity.
- Governance design for AI in ITSM: control towers, audit trails, model validation checkpoints, and escalation matrices to ensure autonomous workflows remain auditable and compliant.
- Negotiation levers and contract playbooks that reflect current pricing dynamics and bundling practices, with templates for SLAs and exit strategies to limit vendor lock-in.
- Vendor profiles and scenario-based vendor shortlists tailored for enterprise size, industry regulation, and cloud footprint.
Strategic recommendations for 2026
- Prioritize governance early: If you plan to adopt autonomous capabilities, implement an AI control tower and audit-ready process definitions before scaling automation.
- Design for composability: Favor platforms that expose robust APIs, support hybrid integration fabrics, and avoid deep proprietary extensions that impede portability.
- Adopt a phased value-first approach: Start with high-frequency, low-risk workflows to capture labor savings quickly, then reinvest realized savings into broader, higher-risk automations.
- Reconsider labor models: Use conservative scenarios in workforce planning that account for substantial ticket deflection and faster resolution times observed in early AI adopters.
- Embed compliance as a product requirement: Procurement must include privacy and data-subject-request capability as mandatory evaluation criteria, not optional features.
Use the report as your operational blueprint — and why you’ll need the full data
This article previews the strategic implications and high-level numbers that should shape your 2026 decisions. However, actionable vendor shortlists, segmented market forecasts, pricing band matrices, and implementation templates are deliberately excluded here to preserve the “trailer” intent: to demonstrate analytical depth while guiding buyers to the full research. The full PW Consulting report contains the granular segmentation, scenario models, and downloadable artifacts necessary to execute vendor selection and migration with confidence.
Next steps
For CISOs, CIOs, procurement leads, and transformation sponsors preparing 2026 budgets and roadmaps, the immediate priority is to validate whether your current ITSM architecture and vendor agreements can support an AI-first, multi-cloud operating model. Use this briefing to align your leadership on the horizon and then consult the full PW Consulting ITSM Software Market report for the detailed breakouts, playbooks, and vendor-by-vendor analysis required to operationalize your strategy.
For detailed analysis of this topic, please visit the official page: IT Service Management (ITSM) Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com