

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: PVD Coaters Market to Grow at 6.2% CAGR Through 2032

PVD Coaters Market 2026: Strategic Preview for Executive Decision-Making
Market snapshot — what the numbers tell senior leaders
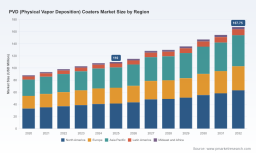
Physical Vapor Deposition (PVD) coaters remain a compact but strategically important industrial equipment market. Between 2020 and 2025 the global market expanded from approximately USD 88.1 Million to USD 110.0 Million (base year 2025). Under the forecast window (2026–2032) PW Consulting projects a steady recovery and structural growth, with the market advancing to roughly USD 167.75 Million by 2032 at a compound annual growth rate (CAGR) of about 6.2%.
PVD (Physical Vapor Deposition) Coaters Market
These macro figures mask important inflection points that will determine winners and losers in 2026: accelerating regulatory pressure on wet and chrome-based finishes, rising adoption of PVD alternatives in high-value manufacturing, and a supply-chain realignment for specialty target materials. This preview explains why those dynamics matter for your 2026 strategy while intentionally withholding the granular segment-by-segment tables — our full report provides the detailed splits executives use to model capex, procurement, and M&A decisions.
PVD (Physical Vapor Deposition) Coaters Market
Why this research matters for 2026 enterprise decisions
- Capex prioritization — Purchasing teams and plant managers need to time equipment acquisition against both regulatory deadlines and vendor delivery lead times. The market’s mid-single-digit CAGR and 2026 regulatory milestones create a narrow window to secure preferred configurations and service contracts.
- Product roadmap alignment — OEMs supplying components or finished products that rely on PVD coatings must align materials and design roadmaps to coating availability constraints and evolving environmental compliance requirements.
- M&A and partnership timing — Fragmentation trends and pockets of consolidation create tactical opportunities for acquiring technology, accessing regional service networks, or securing consumables. Our market concentration analysis shows a moderate top-tier share that leaves room for strategic bolt-ons and regional roll-ups.
- Supply chain risk mitigation — Specialty sputtering target materials have concentrated sources. Procurement teams must incorporate alternative sourcing, strategic inventory, and recycling options into 2026 budgets ahead of potential disruptions or tariff shifts.
Practical contents of the full PW Consulting report (high-level)
Clients use this study as an operational playbook rather than a theoretical overview. The full deliverable includes:
PVD (Physical Vapor Deposition) Coaters Market
- Verified market sizing (historical 2020–2025 and base-year 2025) and a granular forecast (2026–2032) with scenario outputs for demand shocks and technology substitution.
- Segment-level demand models by type, application and region plus sensitivity levers for material pricing, capex deferral, and regulatory tightening (note: detailed segment tables and model inputs are available in the full report).
- Vendor benchmarking and product feature matrices covering reliability, throughput, energy intensity, modularity, and aftermarket economics.
- Procurement playbooks for target-material sourcing, total cost of ownership (TCO) calculators that capture energy, consumables, and compliance cost trajectories, and supplier scorecards to support RFQs.
- Regulatory impact assessment and compliance roadmaps tailored to EU and U.S. rule sets, with step-by-step actions for transitioning to zero-effluent or low-VOC process flows.
- Investment decision frameworks: capex timing templates, break-even analyses for retrofits vs. greenfield assets, and risk-adjusted IRR models for different adoption scenarios.
- Strategic M&A and partnership playbook, including prioritized target archetypes (technology innovators, regional service platforms, and consumable producers) and a due-diligence checklist focused on process reproducibility and target-material contracts.
Competitive landscape — patterns and strategic takeaways
The PVD equipment vendor space is characterized by a mix of specialized engineering houses, industrial platform providers, and a growing number of modular-system vendors. The market concentration metrics show that the top three firms account for roughly one-third of the market, while the top five firms approach about half — a structure that supports both organic differentiation and targeted consolidation.
- VaporTech (Longmont, Colorado) — Recognized for advanced PVD and PECVD/DLC platforms, VaporTech competes on systems that balance throughput with flexible chamber architectures. For industrial users, their V.MAX and VTi series demonstrate how modularity shortens time-to-production for specialty runs.
- PVD Products, Inc. (Wilmington, Massachusetts) — A precision-deposition specialist whose portfolio includes magnetron sputtering, pulsed laser deposition, and thermal evaporation. They are a frequent partner for R&D-to-production scale-up projects where process reproducibility and tight film properties are gating features.
- Vergason Technology (Van Etten, New York) — Following its integration into a broader tribology portfolio, Vergason strengthens offerings around wear-resistant PVD and vacuum metalizing, combining product breadth with aftermarket services relevant to tooling and industrial components.
- Hauzer Techno Coating (Venlo, Netherlands) — Known for modular batch and inline platforms optimized for both decorative and low-friction functional coatings. Their recent investments in digital configuration tools signal a push toward commercializing a service-led model for remote commissioning and lifecycle support.
- Oerlikon Balzers Coating AG (Pfäffikon, Switzerland) — A high-performance systems supplier with platform portfolios positioned for tool, automotive and high-volume decorative segments. Their strength lies in scale, service networks, and cross-selling coatings know-how to equipment customers.
Strategic takeaway: 2026 favors vendors that combine robust process performance (yield, repeatability), sustainable process footprints (low effluent/VOC), and business models that monetize uptime — service, consumables, and digital support. Buyers should evaluate vendors on integrated TCO, not just upfront capex.
Recent vendor developments that shift the competitive calculus
- Hauzer’s platform investments and its "digital configuration" launch point to faster quote-to-order cycles and reduced commissioning risk for complex specs — a material commercial advantage when lead times matter.
- Consolidation moves — exemplified by the acquisition of a U.S. vacuum metalizing specialist by an industrial group — reconfigure access to aftermarket revenue and cross-sell channels for tribology and surface-engineering solutions.
- Across the vendor set, product updates and trade-show participation in 2026 indicate an emphasis on systems that reduce effluent, support alternative target materials, and integrate monitoring dashboards — all attributes buyers should prioritize in procurement language.
Near-term forces and risks that will shape actionable strategy in 2026
- Raw material concentration — Key sputtering target metals (including some rare or strategically sensitive elements) exhibit geographically concentrated supply chains. Procurement teams must model price and availability shocks and consider multi-source or recycling strategies.
- Regulatory acceleration — New regulatory developments (including tighter VOC limits and phase-outs of certain chromium chemistries) accelerate the shift to PVD and zero-effluent systems. Corporate compliance calendars must be synchronized with capital planning to avoid forced retrofits under compressed timelines.
- Technology substitution — In some high-value applications, PVD is displacing older wet chemistries; this is most visible where device yield or environmental restrictions create economic pressure to change process architecture. Firms should quantify switching costs and time-to-qualified production.
- Service and consumables as differentiation — As equipment capabilities converge, aftermarket service contracts, spare-part availability, and consumable supply-security become decisive purchasing criteria.
Strategic playbook — prioritized executive actions for 2026
- Run a 12–18 month procurement window analysis linking regulatory milestones to vendor lead times; favor suppliers with digital commissioning and remote diagnostics to shorten ramp-up.
- Reassess supplier contracts for strategic target materials and insulate critical production lines with dual-sourcing and inventory buffers that are sized by scenario stress tests.
- Expand capital evaluation to include environmental compliance savings (lower effluent handling, avoided remediation costs) and product yield improvements — use our TCO templates to capture these levers quantitatively.
- Pursue bolt-on acquisitions or partnerships focused on aftermarket services, consumable supply, or digital lifecycle platforms rather than only on new system-builds.
- Institute a cross-functional steering committee (engineering, procurement, sustainability, regulatory) to govern PVD transitions and to accelerate technology pilots from lab to production within defined KPIs.
Closing — how PW Consulting can accelerate your 2026 moves
This executive preview draws on our proprietary market sizing and competitive workstreams to highlight where 2026 decisions will generate disproportionate value. The market’s steady growth to 2032 at a roughly 6.2% CAGR signals durable demand, but the strategic gradients — regulation, supplier concentration, and service models — create critical near-term inflection points.
PW Consulting’s full PVD Coaters Market report contains the data tables, regional and application splits, vendor scorecards, and executable templates that manufacturing executives and investors use to finalize 2026 budgets and M&A playbooks. For access to the detailed segmentation, supplier-by-supplier benchmarking, and the downloadable TCO models, please consult the full report and our advisory team to translate the insights above into a prioritized implementation plan.
For detailed analysis of this topic, please visit the official page: PVD (Physical Vapor Deposition) Coaters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com