

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Hardware Encryption Devices Market Poised for 9.6% CAGR Through 2032

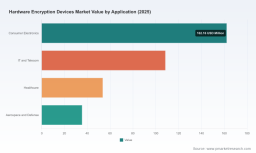
Hardware Encryption Devices Market: Strategic Briefing for 2026 Decision‑Makers
Executive preview — why this briefing matters to your 2026 agenda
As organisations accelerate digital transformation and regulatory scrutiny tightens, hardware encryption devices — from compact portable HSMs to enterprise-class modules — have moved from niche security tooling to core infrastructure. This PW Consulting briefing synthesises proprietary modelling and vendor intelligence to show where value will accrue through 2026 and beyond, and to frame the boardroom trade‑offs executives must resolve this year.
Hardware Encryption Devices Market
We adopt a “trailer” approach: this article presents high‑conviction, data‑driven insights and practical implications while intentionally withholding the granular, segment‑level tables and procurement tools that are available in the full report. Consider this an executive map: enough detail to shape policy and sourcing strategy; the full dataset and vendor scorecards are provided in the complete publication.
Hardware Encryption Devices Market
Market snapshot: trajectory, scale and concentration
PW Consulting’s baseline is 2025. Between 2020 and 2025 the market nearly doubled in scale, reflecting accelerated adoption across cloud, payments and regulated verticals. Our bottom‑up model establishes 2025 as the base year and projects the market forward through 2032 under multiple scenarios.
Hardware Encryption Devices Market
- The market exhibits structural momentum: our central forecast implies a mid‑single digit to low‑double digit compound expansion in the 2026–2032 window, driven by compliance refresh cycles, cloud migration of cryptographic workloads, and early enterprise investment in post‑quantum readiness.
- Under the central scenario the market grows at a compound annual rate of approximately 9.6% through the forecast window, more than offsetting near‑term supply adjustments and providing durable tailwinds for vendors that align product roadmaps with regulatory and cloud operator needs.
- Concentration is material: the top three vendors account for roughly two‑thirds of market revenue, and the top five represent over eighty percent. This structure creates clear leader advantages on scale, validation effort and ecosystem integration, while leaving pockets of opportunity for specialised challengers.
Industry dynamics shaping 2026 buying decisions
Four converging forces will dominate procurement and architecture decisions in 2026:
- Regulatory tightening. U.S. federal standards now require higher FIPS validation baselines for cryptographic modules, and industry‑specific standards (notably payments) have updated device requirements. These deadlines force a short, predictable vendor rationalisation and create a bifurcation between validated incumbents and those still on the compliance ladder.
- Standards and certification activity. New versions of payment‑centric HSM requirements and Common Criteria certifications in key jurisdictions have altered the compliance map. Organisations with cross‑border operations must overlay multiple certification requirements into a single procurement specification.
- Post‑quantum transition. Vendors are shipping post‑quantum algorithm support in firmware and appliance form factors; but readiness is uneven. The practical impact for 2026 is not immediate replacement but staged capability adoption tied to key lifecycle events (certificate renewals, PKI migration windows, cloud contract renewals).
- Infrastructure acceleration. Policy and permitting actions that speed data‑centre and edge deployments reduce lead times for appliance deployment and increase the value of scalable, multi‑tenant HSM platforms that can be deployed in hybrid environments.
Competitive landscape: who matters and why
The market is led by a group of established security vendors and a handful of specialised challengers. Our competitor analysis focuses on product differentiation, certification posture, cloud interoperability and commercial models.
- Thales Group (France) — Thales’ Luna series spans network, PCIe, USB and cloud‑native HSMs. Their roadmap emphasises validated modules, comprehensive key lifecycle tooling and an early, standardised approach to post‑quantum algorithms. Thales continues to prioritise enterprise and regulated use cases.
- Entrust Corporation (United States) — Entrust’s nShield family targets enterprise deployments with appliance and cloud options. Their focus on certified toolkits, developer SDKs and managed cryptographic services keeps them competitive in large corporate and government deals.
- Utimaco GmbH (Germany) — Utimaco positions its u.trust and CryptoServer lines as high‑assurance, multi‑tenant platforms with a strong emphasis on physical tamper resistance and compliance. Their recent product introductions and validation achievements make them a go‑to for the most demanding regulatory environments.
- Yubico (United States) — Yubico’s compact HSM offerings are designed for developer and edge scenarios where form factor and simplicity matter. They are an option where integration speed and portability trump scale.
- Futurex (United States) — Futurex provides enterprise HSMs and centralized key management with focus on payment and POS ecosystems and on integration with legacy estates.
- IBM Corporation (United States) — IBM brings quantum‑safe HSM solutions that blend classical cryptographic support with early post‑quantum algorithms, aimed at customers pursuing an explicit quantum migration roadmap.
- Atos SE (France) — Atos delivers secure HSM solutions focused on data protection and high assurance mission profiles, often bundled with broader data security services.
- Securosys SA (Switzerland) — Securosys offers Primus HSMs and cloud HSM services with attention to post‑quantum readiness and developer ergonomics for cloud operators and MSPs.
Recent vendor developments reinforce the competitive shape: multi‑tenant high‑assurance product launches, firmware releases standardising post‑quantum implementations, and ongoing updates to payment HSM requirements. Together these moves compress the window for evaluation and procurement in 2026.
What our full report contains — practical tools for 2026 execution
The full PW Consulting Hardware Encryption Devices Market study is built for practitioners and includes the following operational deliverables (summarised):
- Proprietary market model with historical reconciliation (2020–2025) and scenario forecasts to 2032, including sensitivity runs tied to regulatory and cloud adoption levers.
- Vendor scorecards assessing certifications, performance profiles, management ecosystems, cloud marketplace footprints and support models — designed to accelerate vendor short‑listing.
- Procurement playbooks and an RFP template keyed to multi‑jurisdiction compliance, performance SLAs and lifecycle migration clauses.
- Deployment blueprints for common migration paths (on‑prem to cloud HSM, appliance upgrade cycles, hybrid cryptographic fabrics), with sample timelines and cost buckets for CapEx/Opex trade‑offs.
- TCO and risk matrices that map certification gaps to remediation costs and implementation time — enabling procurement teams to stress‑test vendor proposals against compliance deadlines.
- Scenario planning and M&A briefing notes identifying consolidation vectors and potential targets for strategic buyers or partnerships.
We intentionally do not disclose granular segment splits or unit prices here: those model rows and downloadable templates are part of the complete report package designed to support procurement and security teams through RFP and integration phases.
Strategic implications for 2026 decision cycles
Based on our analysis, boards and CISOs should prioritise four near‑term decisions this year:
- Certification first: embed certification timelines (FIPS, PCI, Common Criteria) in all procurement and renewal decisions. For many buyers, a validated baseline by the end of 2026 materially reduces compliance risk and total cost of ownership over a three‑ to five‑year window.
- Adopt a hybrid posture: a mixed on‑prem and cloud HSM architecture balances regulatory constraints with operational agility. Shortlist vendors that provide validated cloud HSM offerings plus consistent tooling for key lifecycle management.
- Plan for quantum migration now, execute later: inventory cryptographic dependencies, prioritise critical assets for early post‑quantum protection, and align certificate renewal windows to minimise re‑encryption events.
- Vendor and ecosystem strategy: weigh the benefits of consolidation against the lock‑in risks of single‑vendor stacks. Given the market concentration dynamics, strategic partnerships or multi‑vendor strategies can preserve negotiating leverage while ensuring redundancy for high‑value keys.
Actionable next steps for 90‑day and 12‑month horizons
- 90 days: complete a validated inventory of HSM dependencies and certificate lifecycles; issue an RFP using our template to close gaps with at least two validated vendors.
- 6–12 months: finalise procurement with contractual certification commitments and migration milestones aligned to regulatory deadlines; pilot post‑quantum integrations in non‑production PKI streams.
- 12 months+: transition to an operational model that integrates HSM metrics into security KPIs and procurement scorecards, and evaluate consolidation or strategic partnership opportunities identified by the scenario analysis.
Conclusion — what to expect in 2026 and where PW Consulting adds value
Hardware encryption devices will remain a critical control point for enterprise security, regulated data protection and payments infrastructure through 2026 and beyond. The market’s projected trajectory and the evolving compliance landscape create windows of opportunity for disciplined buyers and well‑prepared vendors. PW Consulting’s full report provides the calibrated datasets, vendor evaluations and procurement tooling needed to turn that window into sustained advantage.
To access the complete market model, vendor scorecards, practical playbooks and downloadable RFP templates, please consult PW Consulting’s Hardware Encryption Devices Market report. The full package contains the granular segmentation analyses and supporting spreadsheets that operational teams require to execute with confidence.
For detailed analysis of this topic, please visit the official page: Hardware Encryption Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com