

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: VOC Rotor Market to hit USD 259M by 2032 at 4.85% CAGR

VOC Rotor Market 2026: Strategic Imperatives from PW Consulting’s VOC’s Rotor Market Study
As companies plan capital allocation, supply-chain resilience, and product roadmaps for 2026, the VOC (volatile organic compound) concentrator rotor market has shifted from a niche engineering solution to a strategic lever for cost, compliance, and competitiveness. PW Consulting’s latest VOC’s Rotor Market study distils five years of historical performance and a forward-looking forecast to 2032, delivering the commercial context executives need to make decisive investments next year. This executive introduction highlights the study’s strategic value while intentionally withholding granular segmentation tables and proprietary scorecards—those items are available in full from the source report.
VOC's Rotor Market
Market at a Glance: Growth, Scale and Concentration
-
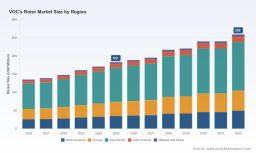
Market trajectory: The global VOC rotor market expanded consistently through 2020–2025, moving from a small base to a materially larger installed market. The 2025 base year is calibrated at USD 183.0 Million (revenue unit: Million, USD), reflecting maturation across semiconductor, automotive, and industrial end markets.
VOC's Rotor Market -
Near- to mid-term outlook: Our forecast uses a compound annual growth rate of 4.85% for 2026–2032, projecting a market approaching USD 259.0 Million by 2032. The growth pattern is steady and characterized by episodic upgrades tied to regulatory cycles and capacity expansions in semiconductor and chemical sectors.
VOC's Rotor Market -
Market structure: Concentration metrics indicate a moderately consolidated supplier landscape—CR3 at approximately 45% and CR5 near 65%—leaving meaningful room for regional specialists and technology-focused entrants to carve niches.
Why 2026 Is a Pivotal Decision Year
Three converging dynamics make 2026 a strategic inflection point for buyers, OEMs, and investors:
-
Regulatory inflection: Energy-efficiency mandates and updated guidelines for solvent-cleaning and VOC concentration devices are accelerating demand for selective adsorption solutions that reduce energy intensity per unit of emission removed. Compliance windows and the capital planning cycles of large industrial players converge in 2026, prompting procurement and retrofit waves.
-
Technology economics: Advances in high-silica zeolites and more durable honeycomb substrates are improving rotor life, reducing maintenance windows, and narrowing the TCO delta versus traditional abatement approaches. These improvements materially influence buy vs. retrofitting decisions in 2026 CAPEX cycles.
-
Operational pressures: Automation-driven labor constraints and higher uptime requirements in semiconductor and automotive production lines increase the value of low-maintenance, high-reliability concentrator rotors—pushing decision-makers to prioritize systems that blend adsorption performance with serviceability.
Strategic Themes for 2026 Decision-Makers
Companies need frameworks that translate the market view into executable choices. The study organizes actionable recommendations across five decision vectors:
-
Procurement and supplier segmentation: Move beyond price-per-unit to total cost-of-ownership models that factor energy consumption, regeneration cycles, rotor life, spare-part lead times, and service contracts. The market’s CR3/CR5 dynamics suggest that strategic supplier partnerships—including exclusive replenishment or managed-service agreements—can yield both pricing and continuity advantages.
-
Technology selection and portfolio positioning: Zeolite-based honeycomb rotors and activated-carbon approaches each deliver competitive advantages depending on feedstock profile, concentration, and duty-cycle. For 2026, prioritize pilot deployments and lifecycle testing for any new rotor chemistry; the TCO inflection often appears only after two to three full service cycles.
-
Manufacturing and retrofit planning: Expect a growing installed-base retrofit market as plants align to updated efficiency mandates. Pre-approved retrofit packages and modular rotor units reduce downtime exposure. Our analysis shows that a staged retrofit strategy—combining pilot lines, regional service hubs, and standardised installation kits—minimizes production disruption.
-
M&A and partnership plays: Mid-sized suppliers with proprietary zeolite mixes or unique honeycomb substrate formulations are attractive bolt-on targets for larger systems integrators aiming to raise CR3. Conversely, well-capitalized regional players can win share via service differentiation and localized supply chains.
-
Risk management and compliance: Integrate rotor performance into corporate emissions monitoring and energy dashboards. Given tightening norms and ISO-referenced expectations for solvent-cleaning equipment, non-compliant assets can attract operational restrictions—accelerating depreciation and forcing earlier-than-planned capital replacement.
Competitive Landscape: Who Matters and Why
The market is shaped by a mix of global integrators, specialist materials firms, and regional equipment makers. The report profiles the leading players and teases strategic implications for 2026 sourcing and product strategies:
-
Seibu Giken Corporation (Japan): A technology leader in honeycomb rotor concentrators, Seibu Giken’s solutions are positioned for semiconductor and high-spec industrial applications where energy-efficiency and low leakage are critical. For buyers, Seibu Giken represents premium performance with engineered systems expertise—suitable where reliability and regulatory certainty outweigh capital sensitivity.
-
Huashijie Environment Technology (HSJ) (China): HSJ’s focus on molecular sieve adsorption rotors combined with RTO systems targets cost-effective fixed-source industrial abatement. Their offerings are relevant for manufacturers prioritizing integrated thermal-desorption workflows within regional compliance regimes.
-
Nichias Corporation (Japan): With its HONEYCLE HZ series and long-standing product pedigree, Nichias emphasizes robust honeycomb zeolite solutions for solvent cleaning and low-concentration emissions. Their product lifecycles and service literature make nichias a pragmatic partner for long-term maintenance planning.
-
Munters (Sweden): Munters’ zeolith rotor concentrators are designed for high-volume, low-concentration streams. Their expertise in engineered adsorbent blends makes them a compelling partner where performance per square meter of rotor is a primary procurement metric.
-
Taikisha Ltd. (Japan): Taikisha brings systems integration strength through rotary RTO systems and rotor components. They are a natural partner for complex retrofit projects where HVAC, heat recovery, and rotor staging must be engineered end-to-end.
-
ProFlute AB (Sweden): As a specialist in PPM molecular sieve and silica gel rotors, ProFlute targets desiccant and niche abatement applications that support VOC removal in humidity-sensitive processes. Their niche focus can be attractive for R&D collaborations or regionally specialized contracts.
Operational Realities: Materials, Standards and the Supply Chain
Material inputs and standards are practical constraints that executives often underestimate. Key supply-side realities to factor into 2026 planning include:
-
Raw materials: Modern concentrator rotors are constructed from honeycomb inorganic paper substrates impregnated with high-silica zeolites, activated carbons, or molecular sieves. Sourcing of high-grade zeolite and consistent substrate manufacturing quality materially affects rotor life, adsorption performance, and replacement cadence.
-
Standards and maintenance norms: ISO-referenced standards for solvent cleaning and concentration devices emphasize routine inspection and performance verification. Buyers should require documented maintenance protocols, test-data at commissioning, and contractual response times as part of procurement.
-
Service economics: Energy efficiency mandates raise the value of rotors that reduce regeneration energy and heat loss. Lifecycle energy modelling—incorporated into procurement evaluation—often flips the decision from replacing to retrofitting existing capture systems.
What the VOC’s Rotor Market Study Delivers (Practical Components)
The full PW Consulting study is intentionally operational. Key deliverables designed for 2026 decision cycles include:
-
Proprietary market model: Scenario-based forecasts (base, accelerated regulation, and slower CAPEX) through 2032 with sensitivity to energy prices and regional compliance timing.
-
Supplier scorecards: Comparative assessments across technology, capacity, service footprint, warranty terms, and supply-chain risk—designed to plug into RFP evaluations.
-
TCO calculators: Configurable templates to compare zeolite vs activated-carbon rotor solutions across duty cycles and energy tariffs.
-
Retrofit playbooks: Step-by-step guidance to plan pilot-to-scaling rollouts with downtime mitigation, mechanical interfaces, and commissioning checklists.
-
Risk heatmaps: Concentration of regulatory and raw-material risks by region and application class—presented to support executive risk registers.
How Executives Should Use This Intelligence in 2026
For procurement leaders: use the TCO models to convert vendor claims into lifecycle outcomes; require pilot validation for new rotor chemistries.
For manufacturing and operations: prioritize modular retrofit contracts and pre-negotiated spare-part inventories to reduce mean time to repair.
For corporate development and strategy: identify midsize materials players with differentiated zeolite blends or honeycomb manufacturing as primary M&A targets to consolidate technical advantage.
For sustainability and compliance functions: integrate rotor performance into emissions accounting and capital planning to avoid unexpected asset stranding as standards tighten.
Next Steps and How to Access Full Intelligence
This introduction outlines the strategic imperatives PW Consulting has surfaced for 2026. The full VOC’s Rotor Market study contains the detailed segmentation tables, regional and application modelling, unit-price decks, supplier contract exemplars, and the downloadable TCO calculator that underpin recommended actions. Those proprietary datasets (including exact regional and application splits and supplier-level financials) are intentionally withheld from this preview to preserve their operational value.
To obtain the complete report, model files, and an advisory session tailored to your business, please visit the VOC’s Rotor Market report page or contact PW Consulting’s industry practice. Armed with the study, executive teams can turn the 2026 inflection into a strategic advantage—optimizing capital, reducing compliance risk, and positioning operations for the next wave of regulation and demand.
For detailed analysis of this topic, please visit the official page: VOC's Rotor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com