

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Logistics Services (3PL & 4PL) Market Poised for 9.25% CAGR Through 2032

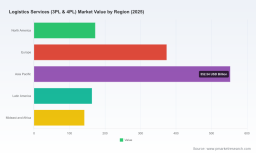
Logistics Services (3PL & 4PL) Market — Strategic Preview for 2026 Decision-Makers
This preview presents the high-level implications of PW Consulting’s forthcoming Logistics Services (3PL & 4PL) Market study and explains why the analysis will be a decision-critical input for corporate strategy teams in 2026. Built on a 2025 base and a 2026–2032 forecast horizon, our modeling shows a continued, material expansion of the outsourced logistics economy at a compound annual growth rate of approximately 9.25 percent. After recovering from pandemic-era disruption, the total industry value climbed from roughly USD 902 billion in 2020 to about USD 1.40 trillion by 2025 and, under the central case, approaches roughly USD 2.61 trillion by 2032. That scale and pace reshape sourcing priorities, capital planning, and competitive positioning for shippers, logistics providers and investors alike.
Logistics Services (3PL & 4PL) Market
Why this study matters for 2026 strategy
-
Prioritizing investment: With double-digit growth on a multi-year horizon, firms must be selective about where to deploy capital—automation, control tower capabilities, and logistics orchestration are common high-return bets. Our study quantifies payoff timelines under alternate demand and cost scenarios so CFOs can sequence expenditures to preserve liquidity while capturing efficiency gains.
Logistics Services (3PL & 4PL) Market -
Supplier and partner strategy: Fragmentation remains a structural feature of the market, creating both arbitrage and risk. The report gives procurement teams a practical vendor-selection framework and negotiation playbook geared to 3PL/4PL engagements—emphasizing outcome-based KPIs, risk-sharing terms, and transition safeguards.
Logistics Services (3PL & 4PL) Market -
Network and footprint decisions: As omnichannel fulfillment proliferates, the right warehouse footprint and transportation mix can be the difference between competitive cost-to-serve and margin erosion. Our location-optimization models translate market growth and regional demand trends into actionable siting scenarios.
-
Resilience and volatility management: Recent industry indicators show capacity contraction in key corridors and continued labor pressure. The study provides scenario-based contingency plans—inventory buffers, dual-sourcing templates, and dynamic routing playbooks—to help executives harden supply chains without permanently bloating operating costs.
-
M&A and portfolio plays: For investors and corporate development teams, our report highlights where scale matters and where niche specialization wins, helping to prioritize targets and structure earnouts tied to operational KPIs rather than top-line vanity metrics.
Macro dynamics shaping 3PL & 4PL through 2026 and beyond
-
E-commerce and omnichannel complexity continue to be structural demand engines. These shifts increase the share of fulfillment and last-mile complexity in many shippers’ cost stacks, pushing them towards integrated 4PL orchestration for end-to-end visibility.
-
Labor scarcity and technology acceleration operate in tandem. Most providers are investing in automation and software-driven control towers to offset labor constraints and to deliver measurable service improvements. Industry studies and practitioner surveys repeatedly cite labor and technology as co-equal forces transforming provider capabilities.
-
Capacity signals are mixed and volatile. Recent freight and capacity indices indicate intermittent contraction in some segments even as aggregate demand grows—creating upward pressure on spot rates and incentivizing longer-term contracts for critical lanes.
-
Regulatory and sustainability drivers are rising up the agenda. Compliance, decarbonization roadmaps, and traceability requirements are widening the services that strategic 3PLs and 4PLs must offer, from emissions reporting to circular logistics for returns management.
-
Market structure remains moderately fragmented: the concentration metrics in our analysis show that while large global integrators hold meaningful capabilities, a long tail of regional specialists continues to capture meaningful volumes—creating options for both cost and service customization.
What PW Consulting’s full report delivers (practical, executable outputs)
-
Executive and Board Briefs — concise, slide-ready narratives linking macro scenarios to company-specific actions.
-
Forecast Engine — a reproducible model with base-case and stress-case outputs across the 2026–2032 horizon (built on transparent assumptions and tested against historical patterns).
-
Operational Playbooks — procurement templates, service-level agreements, transition risk checklists and KPI dashboards tailored to both 3PL and 4PL engagements.
-
Technology Prioritization Matrix — ROI-backed sequencing for control towers, warehouse automation, and AI-enabled transportation orchestration.
-
Network Optimization Tools — scenario-based facility siting and inventory-placement models to support CAPEX decisions and contract structuring.
-
Competitive Benchmarking — qualitative and quantitative scorecards for leading providers, with due-diligence questions for partnership and acquisition candidates.
-
Risk & Compliance Framework — regulatory impact assessments and ESG implementation roadmaps for logistics operations.
-
Case Studies & Implementation Timelines — real-world examples and 90/180/540-day workplans for pilots and rollouts.
Competitive landscape: what leading providers are doing now
The competitive field blends global integrators, contract-logistics specialists, and regional champions. Established players are converging on three strategic moves: (1) embedding technology and control-tower capabilities to offer 4PL orchestration, (2) deploying automation and robotics in contract logistics, and (3) expanding service portfolios to include reverse logistics, fulfillment and sustainability services.
-
C.H. Robinson is accelerating its software and orchestration capabilities — most recently introducing an AI-driven system to autonomously manage multi-modal 4PL shipments — positioning itself to capture value from customers seeking automated decisioning across ocean, air, rail and truck flows.
-
GXO Logistics continues to emphasize contract logistics and warehouse automation, pairing robotics deployments with process redesigns to raise throughput and reduce cost-per-order for large retail and industrial customers.
-
Expeditors and traditional freight-forwarding leaders are leveraging customs expertise and integrated forwarding to upsell higher-margin supply-chain management services.
-
Global network operators such as Kuehne + Nagel, DHL Supply Chain and DSV are doubling down on 4PL orchestration and industry-specific platforms, betting that end-to-end digital offerings will win larger enterprise partnerships.
-
U.S.-focused operators like XPO and J.B. Hunt are exploiting modal strengths—intermodal and last-mile—to defend and expand commercial relationships in high-density markets.
-
Regional and specialist players such as Geodis and CEVA continue to thrive by integrating vertical-specific expertise (e.g., automotive, life sciences) with flexible contract terms, offering an alternative to the “one-size-fits-all” global integrator model.
Recent industry signals to watch in 2026
-
AI and autonomy are moving from pilots to production for orchestration and planning — the industry’s attention at trade shows this spring confirmed technology adoption is now a board-level topic.
-
Conferences and forums in 2026 focused heavily on volatility management and collaboration models, reflecting an immediate need for providers and shippers to co-invest in capacity smoothing mechanisms.
-
Independent indicators show the U.S. 3PL market continuing to expand and that the U.S. 4PL segment remains an emergent but fast-growing component of overall logistics spend—both trends underscoring rising demand for orchestration services.
-
Capacity indices are signaling intermittent tightening, which should push negotiators to build flexibility clauses and surge-capacity arrangements into contracts offered in 2026.
How to convert this intelligence into a 90/180/540-day plan
-
First 90 days — stress-test current contracts, run a supplier capability heatmap, and launch two targeted pilots: one for control-tower orchestration and one for warehouse automation ROI measurement.
-
Next 180 days — standardize commercial terms across your carrier and contract logistics portfolio, renegotiate critical lanes with indexation and performance incentives, and establish a cross-functional deployment team for the highest-value automation pilot.
-
By 540 days — finalize network optimization decisions informed by pilot data, execute phased rollouts of orchestration tech, and pursue strategic alliances or acquisitions only where they deliver clear, measurable improvements in service or cost-to-serve.
Where we draw the line in a public preview
To preserve the utility of the report for commercial decision-making, this preview intentionally omits the granular regional and application-level breakouts, and it does not reproduce the detailed segment tables and proprietary model outputs. Those items — segmented projections, country- and application-level demand curves, provider scorecards with quantified capability ratings, and downloadable modeling spreadsheets — are included in the full PW Consulting Logistics Services (3PL & 4PL) Market report and the companion data package available via our report portal.
Next steps for readers
If your organization is updating sourcing strategies, planning discrete automation investments, or building a 4PL partnership roadmap in 2026, PW Consulting’s full study will deliver the specific inputs and playbooks you need to convert market trends into profitable action. The full report contains the segmented forecasts, provider comparisons and financial models referenced here; request access through our report page to obtain the detailed tables, scenario models and implementation toolkits.
For detailed analysis of this topic, please visit the official page: Logistics Services (3PL & 4PL) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com