

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: GNSS Market Eyes USD 480.3B by 2032 with 9.48% CAGR

GNSS Market 2026: Strategic Imperatives for Executives — A PW Consulting Preview
Executive teaser
The global GNSS market has entered a phase of renewed strategic importance for enterprise leaders. After expanding from roughly USD 163 billion in 2020 to USD 256.2 billion in 2025, the sector is forecast to continue robust growth into the next decade — approaching USD 480 billion by 2032 at a 9.48% compound annual growth rate (2026–2032). These headline numbers disguise a much more complex competitive and regulatory environment: technology-driven jumps in availability and resilience, new firmware- and software-centered business models, and shifting regulatory prescriptions around interference and spoofing are rewriting the playbook for product, M&A, and platform strategies.
GNSS Market
Why PW Consulting’s GNSS Market research matters for 2026 decisions
- Strategic clarity: The market’s strong macro trajectory creates attractive growth corridors, but the value has migrated from pure hardware to integrated systems (firmware, corrections, and services). Senior leaders must align investment choices to capture recurring service revenue and defend margin against commoditization.
- Risk management: Updated regulatory guidance and validated jamming/spoofing test results require near-term technical and compliance responses — both to protect existing deployments and to enable new use cases in safety-critical segments.
- M&A timing: The sector remains comparatively fragmented at the top (top-5 share in the mid‑20s percent range), which creates windows for consolidation and capability acquisition — particularly for players looking to scale resilient, multi-constellation solutions quickly.
- Go-to-market choices: Volume markets demand modular, low-cost solutions while mission-critical segments continue to prize certified high-reliability stacks. A one-size-fits-all approach exposes vendors to pricing pressure and missed revenue pools.
Macro and regulatory dynamics to watch in 2026
Three interlinked dynamics will drive board-level choices this year:
GNSS Market
- Resilience and safety regulation: Aviation and other safety-critical sectors have new guidance that elevates GNSS interference risk to an operational priority. The March 2026 update on GPS/GNSS interference, jamming, and spoofing is already influencing procurement specifications and certification roadmaps.
- Technology-enabled availability gains: Recent product and firmware advances are materially improving signal availability in challenging environments. Case in point: firmware enhancements introduced in early 2026 that capture additional signals have produced measurable availability uplifts, validating software as a high-leverage intervention to improve field performance.
- Validation and standardization: Industry testing campaigns and independent jammertests have validated resilience claims for select suppliers, accelerating procurement cycles in defense, aerospace, and industrial robotics. These results are influencing both public sector standards and private purchasing thresholds.
Competitive landscape — what the leaders are doing and why it matters
The competitive map is bifurcated: a set of specialized, technology-led vendors focus on high-reliability and premium applications, while a broad group of module and system suppliers address high-volume commercial and consumer markets. Recent strategic moves illustrate two clear playbooks.
GNSS Market
- Capability consolidation and resilience: The acquisition activity and product integrations pursued by major players underscore a shift toward vertically integrated positioning stacks for mission-critical customers. A notable transaction completed in 2025 brought a specialist resilient-GNSS provider under the umbrella of a larger systems integrator, accelerating that integrator’s path to deliver “assured positioning” for autonomy and defense use cases.
- Software and service differentiation: Firmware upgrades and corrective services are now tangible levers for performance differentiation. Suppliers that combine robust signal processing with correction and subscription services are capturing higher-margin, recurring revenue — while simultaneously raising switching costs for their customers.
How specific vendors exemplify these trends:
- u-blox (Thalwil, Switzerland): Continuing to strengthen its high-precision chip and module portfolio, with clear emphasis on automotive ADAS, industrial robotics, and precision agriculture where integration of sensor stacks and software-defined features matters.
- NovAtel (Calgary, Canada): Scaling OEM receiver capability and value-added correction services; recent firmware releases have focused on improving reliability in contested environments — a meaningful differentiator for aerospace and defense buyers.
- Septentrio (Leuven, Belgium): Known for resilient multi-frequency, multi-constellation receivers; product family extensions into ultra-compact modules underscore a two-track approach — premium performance and migration to higher-volume deployments.
- Topcon Positioning Systems (Tokyo, Japan): Maintaining a strong position in surveying, construction and agriculture through integrated receiver/base/rover solutions and targeted product launches that localize capability for high-growth agricultural markets.
- Trimble (Colorado, USA): Leveraging broad systems expertise across surveying, construction and automated vehicles — combining hardware, cloud services and applications to lock in enterprise customers.
- Quectel (Shanghai, China): Focused on scalable GNSS modules and integrated IoT offerings to capture volume-driven automotive and machine-control opportunities.
Practical, board-level implications for 2026
- Reprioritize R&D and product roadmaps around resilience and software — allocate 2026 investment to firmware, signal-processing IP, and correction-service capabilities that materially improve availability in degraded RF environments.
- Move from transactional sales to subscription-led monetization where possible — design product bundles that combine hardware, firmware updates, and correction services to create sticky recurring revenue.
- Treat certification and standards leadership as strategic assets — sponsoring standards work, participating in government-industry rulemaking forums, and aligning engineering roadmaps with newly updated regulatory guidance will reduce procurement friction in safety-critical segments.
- Use targeted M&A to fill capability gaps — with the market’s top concentration relatively low, disciplined acquisitions of resilient-sensor designers or regional correction networks can accelerate market entry more cost‑effectively than greenfield R&D.
- Reassess supply-chain and sourcing strategies — for high-volume modules, cost-down and manufacturing scalability are must-win battles; for mission-critical platforms, having dual-source, certified components is essential to satisfy procurement and safety regimes.
What PW Consulting’s full GNSS Market report delivers (practical contents)
Our comprehensive market study is structured to convert insight into action. Key deliverables include:
- Demand models and scenario forecasts with base year 2025 and a detailed 2026–2032 outlook to support budgeting and capital allocation.
- Competitive benchmarking: supplier scorecards, technology roadmaps, and go-to-market motions for leading vendors.
- Segment playbooks for product design, pricing, and channel strategies across consumer, industrial and safety-critical customers.
- Regulatory impact assessments and certification timelines to inform compliance, testing, and advocacy planning.
- M&A target lists and diligence templates derived from capability gaps and concentration dynamics.
- Supply-chain risk heatmaps and mitigation playbooks for component scarcity, certification bottlenecks, and manufacturing scale.
- Practical implementation checklists and 90/180/360-day action plans tailored for executive teams.
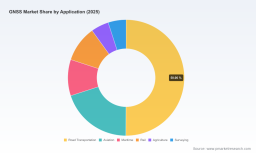
Note: this preview highlights the strategic themes and macro traction that matter for 2026 planning. The full report contains the detailed segment and regional breakdowns, datasets and model inputs that executives use to build precise financial scenarios and operational plans; those granular figures are intentionally reserved for the full deliverable.
How to use this research in your 2026 planning cycle
- Scenario planning: Use the report’s forecasting scenarios to stress-test product roadmaps and service-revenue targets under differing regulatory and technology-adoption assumptions.
- Budget alignment: Translate the forecast and competitive benchmarks into R&D, certification, and go‑to‑market budgets that prioritize resilience and software monetization.
- M&A screening: Apply our capability-gap matrix to shortlist inorganic opportunities that accelerate time-to-market for assured-positioning solutions.
- Regulatory engagement: Align internal compliance milestones with the latest guidance on interference and spoofing to avoid procurement disqualification in critical accounts.
Closing — the strategic choice for 2026
The GNSS market’s growth curve creates a rare moment: the underlying market is expanding rapidly, yet leadership is still defined by capability, integration and regulatory alignment more than scale alone. Executives who reposition their organizations around resilient positioning stacks, software-driven differentiation and carefully timed capability acquisitions will convert market growth into defensible value. For teams preparing 2026 budgets and board materials, PW Consulting’s full GNSS Market report supplies the granular segmentation, scenario modeling, and execution templates needed to move decisively — while this preview surfaces the strategic priorities that should be debated at the top of the house.
To access the full dataset, regional and application splits, and proprietary benchmarks that power our recommendations, please consult the complete GNSS Market report on the PW Consulting research portal.
For detailed analysis of this topic, please visit the official page: GNSS Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com