

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Chemical & Materials
PW Consulting: 1,2‑Pentanediol Market to Grow at 6.5% CAGR (2026–2032)
By pmarketresearch, 2026-07-13
Strategic Outlook — 1,2-Pentanediol Market: A 2026 Decision Brief
Executive snapshot
As companies calibrate capital allocation and commercial strategies for 2026, 1,2-pentanediol (pentylene glycol) is emerging as a strategic intermediate that links shifts in personal care formulation, sustainability mandates, and petrochemical feedstock volatility. Our PW Consulting study — anchored on a 2025 base year, a 2020–2025 historical review, and a 2026–2032 forecast horizon — synthesizes market economics, supplier dynamics, regulatory friction points, and technology pathways to create an operationally useful roadmap for decision makers.
1,2-Pentanediol Market
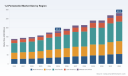
Key macro takeaways you need immediately: the market has grown steadily from the early 2020s into mid-decade and, under our base forecast trajectory, is set to continue expanding through 2032 at a compound annual growth rate aligned with mid-single digits. That trajectory translates into meaningful scale expansion for incumbents and new entrants alike, while also increasing the economic incentives for vertical integration and feedstock innovation.
1,2-Pentanediol Market
Why 2026 is a strategic inflection
-
Convergence of demand drivers: Growth in personal care formulations, renewed R&D in pharmaceutical excipients and pesticide intermediates, and incremental uptake in industrial applications are collectively broadening the total addressable market.
1,2-Pentanediol Market -
Sustainability as a differentiator: Biobased and upcycled feedstock routes have shifted from marketing plus to commercial necessity for a set of premium buyers; buyers are increasingly willing to pay for certified, lower-carbon inputs.
-
Supply-side complexity: Price and availability of traditional petrochemical feedstocks have become more volatile due to regional geopolitical events, feedstock export constraints, and shifts in naphtha/LPG/natural gas markets — increasing the value of diversified sources and regional footprint resilience.
-
Regulatory tightening: A complex regulatory landscape across cosmetic, pharmaceutical and food-contact pathways is creating longer supplier qualification cycles and raising the bar for documentation, testing, and certification.
Market trajectory (what the numbers say)
Our historical reconstruction (2020–2025) demonstrates steady recovery and expansion through mid-decade, reflecting both volume growth and premiumization in specific applications. Using 2025 as the base year, the report models multiple forecast scenarios across 2026–2032. Under the central case, the market grows at a mid-single-digit CAGR to reach materially higher scale by 2032. These aggregated dynamics mask pockets of accelerated growth — and pockets of cyclicality — that are explored in the full study via scenario banding and sensitivity testing.
Key strategic implications for 2026 planning
-
Procurement & commercial protection: Buyers should reassess contract tenors and indexation clauses. The combination of feedstock volatility and regional supply interruptions raises the value of blended procurement strategies: longer-term agreements for core volumes, combined with flexible spot exposure for opportunistic sourcing.
-
Capacity investment decisions: For manufacturers and private-equity owners, the question is not simply whether to add capacity, but where (geography & grade) and which technology route to prioritize. Biobased production lines command a price premium in some customer segments, but they also require distinct feedstock certifications and longer qualification timelines.
-
Product & portfolio strategy: C-suite teams should identify which grades and formulations will capture the sustainability and performance premiums over the next two to four years. Cosmetic-grade and specialty derivatives tied to lower-carbon feedstocks are structurally advantaged with certain global buyers, but industrial applications remain cost-sensitive and exposed to petrochemical price swings.
-
M&A and alliance playbook: The market’s structural maturation favors bolt-on acquisitions that provide feedstock security, regional market access, or specialized downstream capabilities (e.g., formulation services for personal care). Joint development agreements and tolling partnerships are an efficient way to de-risk new biobased routes without committing full capex.
-
Regulatory & quality assurance: Expect extended supplier qualification timelines. Firms entering or scaling in this market must invest in regulatory dossiers, third-party testing, and traceability systems to meet customer and jurisdictional requirements.
Competitive landscape — players to watch
The supplier map is a mix of specialized regional producers and global ingredient houses that are moving up the value chain. A few differentiated strategic plays emerge from recent corporate activity and public disclosures:
-
Large ingredient houses that pair marketing reach with dedicated biobased production units are using that capability to accelerate adoption among multinational personal care brands. Dual-site manufacturing and demonstrable upcycling credentials are serving both reliability and sustainability narratives.
-
Specialized chemical manufacturers in Asia continue to anchor cost-competitive supply and quick fulfillment for industrial users, while also investing in regional biobased capacity to capture higher-margin cosmetic demand.
-
Technology differentiation is increasingly commercial: product provenance (e.g., upcycled sugarcane bagasse) and vertically integrated feedstock pathways are shortening supplier selection lists for premium customers.
Recent notable developments include the commissioning of additional biobased production capacity by a major ingredient supplier in Europe, modeled on an existing U.S. site, and industry recognition for sustainability credentials that emphasize upcycled agricultural residues. These moves signal a strategy shift from pilot-scale sustainability proofs to full commercial roll-outs — and they will materially alter supplier selection dynamics for multinational buyers.
Risk map — what keeps CEOs and procurement chiefs awake
-
Feedstock and price volatility: Exposure to n-pentene and other petrochemical-derived inputs creates margin vulnerability for producers and price risk for buyers during geopolitical disruptions.
-
Certification bottlenecks: Sourcing biobased or upcycled feedstocks requires validated chains of custody; delays in certification slow customer qualification and limit near-term market share gains.
-
Regulatory heterogeneity: Diverging rules across cosmetic, pharmaceutical and agrochemical jurisdictions require bespoke compliance strategies, increasing time-to-market.
-
Concentration effects: While a small set of suppliers offers scale and branded biobased grades, regional suppliers retain influence in cost-sensitive segments. This creates a two-speed market where premium and commodity pathways coexist.
What our PW Consulting report delivers — the practical toolkit
This study is designed as an actionable playbook for executives who must make capital, sourcing or go-to-market decisions in 2026. Key deliverables include:
-
Scenario-based demand and price models for 2026–2032, with sensitivity to feedstock price paths and regulatory outcomes.
-
Supply-side intelligence: vetted supplier profiles, capacity maps, and qualitative assessments of operational resilience and feedstock security.
-
Commercial tools: supplier scorecards, contract clause templates (tenor, indexation, force majeure), and a bidding framework for RFP design.
-
Investment decision frameworks: unit-economics templates for greenfield vs. brownfield investments, and an M&A screening matrix that prioritizes feedstock access, technology fit, and customer overlap.
-
Regulatory playbook: jurisdiction-level compliance checklists, expected qualification timelines, and testing/validation roadmaps for cosmetic and pharmaceutical applications.
-
Risk management artifacts: hedging strategies, procurement levers, and a supply-disruption response playbook aligned to board-level crisis scenarios.
To preserve commercial value for subscribers and prospective buyers, the report intentionally positions headline macro trajectories and strategic implications in this brief while retaining the full, granular segmentation tables, supplier-level financials, and proprietary demand models in the full deliverable.
How to use the analysis in 2026 decision cycles
-
Board and Investment Committees — use the scenario models to stress-test capex proposals and to define go/no-go thresholds tied to feedstock price and certification timelines.
-
Commercial & Procurement — reframe supplier negotiations around blended supply strategies and include sustainability credentials in commercially weighted scorecards.
-
R&D and Product Teams — prioritize formulation work that leverages biobased grades where margin uplift is validated; accelerate customer trials with dual-sourced samples to shorten qualification windows.
-
M&A teams — prioritize targets that provide immediate feedstock security or accelerate biobased manufacturing scale without long permitting lead times.
-
Risk & Compliance — build a compliance calendar mapped to customer qualification lead times and regulatory milestones to avoid lost sales from protracted approvals.
Final perspective — an operational judgment
The 1,2-pentanediol market in 2026 is less about an either/or between petrochemical and biobased supply and more about orchestration: producers, buyers and investors who align feedstock strategy, regulatory preparedness, and customer qualification timelines will capture the lion’s share of near-term upside. The market’s growth path creates both opportunity and complexity — rewarding those who use granular supplier intelligence, scenario planning, and disciplined procurement playbooks.
PW Consulting’s full 1,2-Pentanediol Market report provides the data, models, and executable templates that procurement leads, strategy teams, and corporate development groups need to convert this strategic moment into measurable value. For access to the proprietary segmentation, supplier-level forecasts, and the decision-ready toolkits referenced above, consult the full report page or contact your PW Consulting representative.
For detailed analysis of this topic, please visit the official page: 1,2-Pentanediol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: DVB Market to reach USD 1,305.85 Million by 2032 at 5.67% CAGR
By pmarketresearch, 2026-07-13
Divinylbenzene (DVB) Market — Strategic Outlook for 2026 Decision-Making
Introduction
As companies refine their 2026 investment plans, procurement strategies, and product roadmaps, a pragmatic, forward-looking view of the divinylbenzene (DVB) market is indispensable. This briefing, drawn from PW Consulting’s comprehensive DVB Market study (base year 2025, forecast 2026–2032), highlights the strategic value of that research for executive decision-makers. It illustrates the actionable intelligence contained in the full report while intentionally withholding granular segment figures — a “trailer” designed to demonstrate analytic depth and to guide you to the full dataset and tactical tools.
Divinylbenzene (DVB) Market
Executive snapshot: the market in context
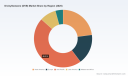
DVB is a mature specialty monomer used primarily as a cross‑linker in ion‑exchange and chromatographic media, in adhesives and coatings, and across a range of engineered polymer applications. From 2020 to 2025 the industry expanded steadily from roughly USD 674 million to USD 888 million (revenue unit: Million USD, base year 2025). Our modelling indicates continued expansion through the forecast window, reaching an estimated market size in excess of USD 1.3 billion by 2032 under a central-case compound annual growth rate (CAGR) of 5.67% for 2026–2032.
Divinylbenzene (DVB) Market
Concentration metrics point to a moderate level of market consolidation: the top three suppliers account for just under half of market sales while the top five capture roughly two thirds. These dynamics create a market where regional supply security, product quality tiers (standard vs. high‑purity grades), and supplier relationships drive commercial outcomes.
Divinylbenzene (DVB) Market
Why DVB decisions matter in 2026
-
Cross‑linking chemistry remains foundational for water treatment resins, biopharmaceutical chromatography media, and a set of high‑value specialty plastics. Small shifts in DVB quality or availability can cascade into downtime, qualification delays, or margin compression for resin manufacturers and their downstream customers.
-
Regulatory and sustainability pressure is rising: manufacturers face more stringent handling, emissions, and disposal requirements that affect operating costs and capital choices. These considerations are becoming core to make/buy and location decisions.
-
Feedstock volatility — particularly styrene and ethylbenzene — introduces cost variability that directly affects producer margins and can quickly reshape competitive advantage between integrated petrochemical players and specialized producers of high‑purity grades.
What the PW Consulting DVB report delivers — practical, transaction‑ready intelligence
The full study is built for leaders who must translate market intelligence into executable actions. Key deliverables include:
-
Transparent market sizing and demand‑model architecture (2020–2025 historicals, 2026–2032 forecast) with scenario toggles and sensitivity analytics;
-
Price and margin modeling that links crude/petrochemical feedstock scenarios to producer-level EBITDA under alternate pass‑through regimes;
-
End‑use demand maps (resins, chromatographic media, coatings, elastomers) with adoption curves and technology‑substitution risk scoring;
-
Supply side diagnostics: plant‑level capacity, utilization benchmarks, impurity‑control capabilities (critical for chromatography and biopharma grades), and de‑bottlenecking potential;
-
Regulatory & compliance playbook (REACH, TSCA, food‑contact rules, emissions controls) showing cost impacts, timeline risks, and certification requirements;
-
Competitive benchmarking and supplier scorecards including technical capability, geographic footprint, and commercial terms;
-
Deal and investment tools: transaction valuation templates, capex decision trees, NPV/IRR scenarios for brownfield vs greenfield expansions, and negotiation playbooks for long‑term off‑take agreements;
-
Risk heatmaps and an early‑warning indicator set operators can monitor weekly to quarterly.
To preserve commercial value for our clients, this high‑level brief intentionally omits the granular split tables and region/application shares available in the full report.
Competitive dynamics — who matters and why
The DVB supply landscape is shaped by a mix of regional chemical incumbents and specialty monomer specialists. Strategic moves over 2024–2025 show the market bifurcating between scale/integration advantages and specialist premium offerings:
-
Specialty producers with advanced purification capability have moved to secure upstream feedstock and to certify product quality for biopharma chromatography — an attractive, higher‑margin end market. Examples include recent capacity and purification upgrades by firms focused on tighter impurity control to serve premium resin manufacturers.
-
Integrated chemical groups are leveraging broader petrochemical value chains to maintain cost advantages at standard purity points, while selectively investing to supply industrial water‑treatment and coatings segments.
-
Regional players and acquisitions have reshaped North American supply security: recent asset transfers and consolidations were executed to preserve local availability for water‑treatment and specialty coatings customers.
These strategic movements have immediate implications for sourcing risk and pricing volatility: buyers reliant on a narrow set of suppliers for high‑purity grades face different risks than purchasers of standard grades where integrated producers can balance feedstock swings across larger portfolios.
Supply chain, feedstock risk and regulatory tailwinds
-
Feedstock linkage — DVB production is dependent on upstream benzene derivatives (notably ethylbenzene and styrene). Price swings in crude and naphtha translate into variable production economics for DVB makers and require active hedging or contractual pass‑through mechanisms for downstream customers.
-
Regulatory pressure is accelerating: REACH and TSCA impose handling and waste‑management obligations that increase compliance costs for producers; food‑contact rules require specific approvals for styrene/DVB systems used in certain bead products; and recent policy discussions around taxable listings may raise manufacturing or product costs in selected jurisdictions starting early 2026.
-
Environmental limits on aromatics emissions are shaping location and technology choices for capacity expansions — permitting risk is now a material input to capital planning and cycle time estimates.
Strategic considerations for 2026 plans — practical next steps
Below are the high‑impact strategic questions executives should answer in 2026, supported by the analyses included in the full PW Consulting study.
-
Supply security vs cost: Should you pursue long‑term off‑take contracts with specialist suppliers (premium for high‑purity) vs spot purchases from integrated producers? Use scenario NPV to compare cost of inventory, service level, and qualification risk for biotech customers.
-
Capex posture: Is de‑bottlenecking or selective debottleneck investment preferable to greenfield expansion? Our capex decision tree helps prioritize brownfield projects where permitting timelines and regulatory risk are lower.
-
Product strategy: Where to position portfolio — pursue certification and premium pricing for chromatography/biopharma grades, or double down on scale for commodity resin markets? The answer depends on your technical capability, access to feedstock, and tolerance for extended qualification cycles.
-
Commercial & pricing: Shift from cost‑plus to value‑based pricing in segments that prize low impurity and traceability. Negotiate clauses that allow feedstock cost pass‑throughs but cap downside risk in extended low‑price environments.
-
M&A and partnerships: Target bolt‑ons that add purification IP, analytical capability, or regional supply nodes rather than low‑value capacity. Recent asset transfers show premium for assets that secure local supply and IP.
-
Compliance & ESG: Build a regulatory roadmap and allocate contingency capital for emissions controls and handling upgrades — noncompliance could be more costly than proactive investment.
-
Monitoring & KPIs: Establish a compact dashboard (weekly feedstock price delta, supplier fill rate, grade‑specific inventory coverage, time‑to‑qualify for new grades, permit lead times).
How PW Consulting’s DVB study supports your 2026 decisions
The full report equips executives with the withheld granular segmentation by region, type, and application (available in the paid study), plus transaction‑ready tools that convert market intelligence into board‑level recommendations:
-
Supplier scorecards and comparative total cost of ownership (TCO) models;
-
Scenario‑based pricing and margin models that translate petrochemical price paths into producer and buyer economics;
-
Regulatory timelines aligned to capital planning, with cost estimates and mitigation options;
-
Deal playbooks for long‑term offtake contracts, JV structures, and acquisition target screening.
We intentionally present this executive trailer without the full regional and application splits: those datasets and the supporting spreadsheets are central to the licensed report and to bespoke advisory work targeted at specific investment or procurement choices.
Conclusion — the strategic value in 2026
For decision‑makers, DVB is more than a commodity monomer: it is a strategic lever in resin and specialty polymer value chains. Between feedstock volatility, rising regulatory costs, and an evolving competitive landscape, 2026 will be a year where the right mix of supplier strategy, selective investment, and product positioning creates outsized competitive advantage. PW Consulting’s DVB Market study transforms that complexity into operational choices — mapping which decisions move the needle and offering the analytic tools to execute them. To access the full segmentation tables, financial models, and supplier scorecards necessary for transaction‑level decisions, visit our report page or contact PW Consulting’s strategy team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Divinylbenzene (DVB) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vinylidene Chloride Market Poised for 4.8% CAGR Through 2032
By pmarketresearch, 2026-07-13
Vinylidene Chloride Market — Strategic Briefing for 2026 Decisions
Executive snapshot
As companies plan capital allocation and product strategy for 2026, understanding the vinylidene chloride (VDC) market’s macro trajectory and operational headwinds is essential. Our analysis at PW Consulting shows a market that has steadily expanded through 2020–2025 and is projected to continue growing across the 2026–2032 forecast window at a compound annual growth rate (CAGR) of approximately 4.8%. Using 2025 as the analytical base year, the market sits at roughly USD 250 Million (revenue unit: Million), and our forecast projects progressive growth through 2032 in nominal terms.
Vinylidene Chloride Market
Why this matters to executive decision-makers in 2026
-
Portfolio prioritization: Vinylidene chloride feeds high-barrier polymers, coatings and specialty intermediates. Even moderate annual growth can alter the ROI timeline for new capacity and downstream product launches.
Vinylidene Chloride Market -
Supply-chain resilience: The molecule’s production is sensitive to chlorinated feedstock dynamics and environmental compliance costs, making supplier selection and vertical integration decisions consequential.
Vinylidene Chloride Market -
Regulatory and operational risk: Stringent worker safety rules and environmental controls in major jurisdictions are driving capital expenditure and process redesigns that affect unit economics.
Market trajectory: the macro numbers you can’t ignore
Between 2020 and 2025 the market recorded steady growth, with a notable acceleration in the mid-decade years that left the sector poised for a multi-year recovery and expansion phase. From a base of about USD 195 Million in 2020, the market reached roughly USD 250 Million in 2025. Our 2026–2032 forecast—anchored to the 2025 base year—assumes a 4.8% CAGR, cumulatively compounding to materially higher nominal market value by 2032. This growth is underpinned by continuing demand for high-barrier packaging solutions and select industrial applications that require VDC-based chemistries.
Key market dynamics shaping 2026 strategy
-
Raw material and feedstock volatility: Regional swings in ethylene and ethylene dichloride pricing have a first-order effect on production cost for VDC. For example, supply tightness in North America drove a pronounced rise in certain feedstocks in late 2025, while Asia experienced price softening earlier in 2025 due to inventory build-up and dampened demand. These divergent trends create arbitrage opportunities but also raise the bar on risk management for buyers and producers.
-
Regulatory tightening and compliance CAPEX: Environmental regulation of chlorinated hydrocarbons and tightened occupational exposure limits (notably under U.S. OSHA frameworks) are increasing operating and compliance costs. Firms that proactively invest in lower-emission processes, monitoring systems and worker protection protocols will reduce regulatory tail risk but must balance that CAPEX against near-term margin pressure.
-
End-market shifts and product substitution risk: The dominant applications for VDC—high-barrier polymer systems and specialty intermediates—face substitution pressure from alternative barrier technologies and formulation innovations. Understanding where VDC offers an enduring technical advantage (e.g., ultra-high barrier film requirements, certain pharmaceutical packaging) is a prerequisite to defensible investment.
-
Inventory and demand cyclicality: The market’s short-cycle inventory behavior in key manufacturing hubs induces pricing volatility. Tactical procurement strategies and agile tolling/contracting models can protect margins during demand troughs and enable rapid upside capture in recoveries.
Competitive landscape — who matters and why
The VDC industry is a mix of global majors and regional specialist producers. Market presence is concentrated enough that actions by a few large firms can materially influence supply balances and pricing. Broadly, top producers combine scale production assets, downstream integration into PVDC and coatings, and geographic footprints that span mature and emerging demand centers. Examples of prominent players include:
-
Dow Inc. (United States) — Integrated production footprint with recent capacity moves aimed at meeting rising demand for high-performance polymers. (Source: Dow recent development, Jan 2026)
-
Kureha Corporation (Japan) — Specialist in PVDC resins and high-barrier film solutions, leveraging proprietary resin technologies for premium packaging applications.
-
Asahi Kasei Corporation (Japan) — Focused on emulsion polymerization routes and applications that span medical and packaging coatings.
-
Solvay S.A. (Belgium) — Strong in pharmaceutical-grade barriers and coating systems, with an active stance on regulatory compliance and sustainability in chlorinated chemistries.
-
Chinese producers (several regional firms) — Provide capacity for bulk PVDC intermediates and emulsions that serve fast-moving consumer goods and industrial markets in Asia.
These producers display differentiated strategies: some compete on scale and integration, others on niche resin science or customer intimacy in specialized applications. Importantly, capacity expansions by a major player (the January 2026 expansion by Dow in Texas) show how a single investment can influence regional supply balances and pricing dynamics across the chain.
What the full PW Consulting report delivers — operationally focused
Our full market study moves beyond high-level narrative to provide practical decision support for 2026 planning cycles. Key deliverables include:
-
A validated market-sizing model (base year 2025) with scenario-driven forecasts across 2026–2032. The model is built for sensitivity testing against feedstock costs, regulatory scenarios, and demand shocks.
-
Risk-adjusted investment appraisal templates that translate forecast volatility into NPV and payback ranges for greenfield and brownfield options.
-
Supply-chain stress tests and procurement playbooks that specify hedging, tolling and strategic inventory hedges for both buyers and sellers.
-
Commercial playbooks for downstream differentiation, identifying where VDC-based solutions deliver defensible value versus competing barrier technologies.
-
A competitive intelligence dossier on leading producers, with capability maps, recent capacity moves, and likely strategic responses under alternative demand scenarios.
Note: to preserve commercial sensitivity and to drive actionable engagements, this introductory briefing intentionally omits the granular regional and application-level allocation tables that appear in the full report. Those tables are available in the complete deliverable and are essential for transaction-level decisions.
Strategic implications and recommended actions for 2026
-
Re-evaluate capacity timing vs. demand certainty: With a mid-single-digit CAGR projected for the medium term, aggressive greenfield commitments should be stress-tested under downside scenarios. Consider phased or modular capacity options and tolling partnerships to retain optionality.
-
Lock in feedstock advantage where possible: Vertical integration or long-term feedstock contracts can insulate margins from the feedstock swings observed across regions. Pricing arbitrage in 2025–2026 illustrates how regional feedstock moves can flip competitiveness.
-
Prioritize regulatory-forward investments: Early investment in emissions control and worker safety systems reduces regulatory disruption risk and preserves access to premium customers (e.g., pharmaceutical packaging buyers demanding stringent compliance).
-
Differentiate through formulation and value-added services: Suppliers that pair VDC supply with polymer science, coating expertise, or application engineering will command superior commercial terms compared with undifferentiated commodity supply.
-
Adopt dynamic contracting models: Use a mix of short and medium-term contracts, indexation clauses linked to feedstock costs, and performance-based tolling to manage volatility exposure.
How to use this intelligence in the C-suite and for investor committees
For CEOs and CFOs, the focus is on calibrating capital deployment to a market that is growing, but exposed to feedstock and regulatory variability. For commercial leaders, the task is to sharpen value propositions where VDC’s barrier properties are non-substitutable. For procurement and operations, instituting flexible contracting and investing in compliance provides downside protection.
Closing — what we recommend next
Vinylidene chloride is not a mass-commodity where scale alone wins; it is a specialty intermediate whose market outcomes are determined by feedstock economics, regulatory posture, and downstream performance differentiation. PW Consulting’s full report contains the granular, transaction-ready data tables, regional and application breakdowns, and scenario models required to make 2026-capex and commercial decisions with confidence. This briefing reveals the strategic contours; the full study provides the operational map.
To unlock the complete dataset, scenario models, and supplier-level assessments that underpin these executive recommendations, request the full PW Consulting Vinylidene Chloride Market report and accompanying decision toolkits.
For detailed analysis of this topic, please visit the official page: Vinylidene Chloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sodium Borohydride Market to hit USD 232.9 Million by 2032 at 5.7% CAGR
By pmarketresearch, 2026-07-13
Sodium Borohydride Market: Strategic Briefing for 2026 Decision‑Makers
Executive snapshot
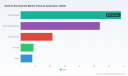
As companies plan for 2026 and beyond, sodium borohydride is moving from a niche reagent toward a strategically important specialty chemical with multiple industrial and clean‑tech touchpoints. Our PW Consulting study—anchored on a 2025 base year and a 2026–2032 forecast horizon—finds the global market expanding at a compound annual growth rate (CAGR) of 5.7%. Measured in USD Million, total market revenue grew from roughly 128.6 in 2020 to 160.7 in 2025 and is projected to reach approximately 232.9 by 2032. These headline numbers conceal an active market architecture: concentrated supply, high technical barriers to entry, and differentiated end‑use dynamics that together create distinct opportunity sets and supply risks for industrial buyers, chemical producers, and strategic investors.
Sodium Borohydride Market
Why this briefing matters in 2026
-
Timing: 2026 is a hinge year. Recent capacity moves by tier‑one producers and elevated attention to hydrogen, pharmaceuticals, and pulp/paper bleaching are reshaping demand composition. Firms that position procurement and capacity strategy this year will capture advantaged access to fast‑growing niches.
Sodium Borohydride Market -
Supply risk: Concentration metrics show a market where the three largest players account for a substantial majority and the top five consolidate an even greater share. This concentration amplifies the impact of single‑site outages, planned expansions, and regional raw‑material constraints on price and availability.
Sodium Borohydride Market -
Investment horizon: Given capital‑intensive synthesis routes and specialized handling needs, greenfield entry is expensive and slow. Strategic decisions in 2026 about capacity expansions, long‑term offtakes, and vertical integration will reverberate through 2032.
Market dynamics and what they mean
-
Upstream raw‑material geography: Sodium borohydride synthesis is materially dependent on boron feedstock (commonly sourced as borax). Global boron reserves are highly concentrated; one country holds the lion’s share of documented reserves. This geological concentration creates an asymmetric supply vulnerability—especially where logistics or export policy shifts intersect with demand spikes.
-
Complex, capital‑intensive synthesis: The standard industrial routes require multiple feedstocks (including sodium hydride and organoboron intermediates) plus advanced process control. This raises barriers to entry, favors incumbents with process know‑how, and limits the pace at which new capacity can be commissioned—an important consideration for firms evaluating near‑term procurement contracts versus longer‑term equity stakes.
-
Demand drivers are diverse and asynchronous: End uses range from pharmaceutical API hydrogenation and specialty reducing applications to paper deinking/bleaching and emerging clean‑energy roles (e.g., as a hydrogen carrier or in fuel‑cell related chemistries). These end markets exhibit different cyclicality, regulatory exposures, and margin profiles—creating both risk diversification and the need for tailored go‑to‑market strategies.
-
Price and margin dynamics: Given capacity concentration and feedstock dependencies, price moves tend to be lumpy and respond to both feedstock shocks and single‑player capacity announcements. Buyers should model scenarios that include regional feedstock disruptions, step‑change demand from a single end market, and staggered ramp‑ups of new production lines.
Competitive landscape — who matters and why
The market is dominated by a set of specialized chemical manufacturers with varied strategic profiles: long‑standing pulp/paper and water‑chemicals incumbents, custom‑synthesis pharmaceutical suppliers, and North American process‑chemical players specializing in safe handling and large‑volume production. Recent noteworthy moves include a mid‑2025 capacity expansion by a major European producer, which illustrates how targeted investment in powder production lines can shift regional supply balances when brought online.
-
Kemira Oyj (Helsinki, Finland) — A differentiated player with both an alkaline aqueous product for pulp and deinking applications and a higher‑purity powdered offering for pharmaceutical/industrial reductions. Their recent decision to add a dedicated powder line at a Finnish site (investment decision in mid‑2025, ramping to full operation around late‑2026) is a strategic example: it addresses quality‑segmented demand and reduces reliance on cross‑border supply for specialty grades.
-
Ascensus Specialties LLC (US) — A large‑scale producer focusing on broad hydride portfolios and industrial reducing agents. Their value proposition centers on scale, regulatory know‑how, and safe handling capabilities—attributes attractive to industrial accounts demanding large, consistent volumes and predictable logistics.
-
Montgomery Chemicals (Conshohocken, PA, US) — A solutions‑oriented supplier with branded sodium borohydride solutions for textile, paper, and wastewater markets. Their strength lies in application engineering and formulated product offerings that reduce customer integration friction.
-
Shandong Guobang Pharmaceutical Co., Ltd. (China) — A supplier of high‑purity hydrides aimed at pharmaceuticals and specialty industries. Their presence underscores the global sourcing dynamics: tight quality specifications in pharma can be met by specialized Asian suppliers, but procurement must evaluate regulatory and supply‑chain risk trade‑offs.
Implications for procurement, operations, and corporate strategy
-
Supplier risk management: With high market concentration and geographically clustered raw materials, organizations should adopt multi‑vector procurement strategies. That includes dual‑sourcing where feasible, retaining spot flexibility for surges, and negotiating capacity reservation clauses for multi‑year needs.
-
Make vs. buy calculus: For companies whose margins are highly sensitive to input availability (e.g., specialty pharma and clean‑tech OEMs), investing in partial vertical integration—such as toll manufacturing agreements, co‑location of reduction steps, or minority stakes in production lines—can be value‑accretive versus exposure to market tightness.
-
Product strategy: The market rewards product differentiation—high‑purity powders for pharma, aqueous formulations for pulp/paper, and packaged solutions for industrial users. Firms should map their margin pools against required handling, regulatory certification, and logistics costs before selecting which product forms to prioritize.
-
Regulatory and sustainability lens: End markets like pharmaceuticals and water treatment place rising emphasis on traceability, impurity control, and environmental footprint. Capital investments that lower lifecycle emissions or improve solvent recovery will increasingly influence customer selection criteria and can command price premium.
What the full PW Consulting report delivers
Our report is designed as a decision‑oriented toolkit for executives preparing 2026 strategies. Key deliverables include:
-
Top‑line market sizing and a year‑by‑year revenue model from 2020 through 2032 (base year 2025; forecast period 2026–2032) with scenario variants driven by end‑market demand shocks and supply interruptions.
-
Proprietary concentration analysis (CR3/CR5) with supplier profiles, capacity maps, and a timeline of announced versus operational lines—essential for procurement contingency planning.
-
Value‑chain and cost‑build models that break down feedstock and synthesis step economics, enabling accurate margin simulations for greenfield, brownfield, and tolling options.
-
Commercial playbooks tailored to buyers, producers, and investors—covering contract structures, hedging approaches, and M&A screening criteria.
-
Regulatory, safety, and sustainability risk matrices, and a prioritized list of technical due‑diligence items for any intended partnership or acquisition.
-
Primary research: interviews with plant operations, procurement heads, and technical R&D leaders across producing regions to validate capacity ramp schedules and commercial intents.
Strategic moves recommended for 2026
-
For buyers with scale exposure: secure rolling offtake agreements with volume flex corridors, build inventory buffers tied to validated safety cases, and pursue supplier collaboration for co‑optimized logistics.
-
For chemical producers: prioritize incremental capacity in high‑purity powder production or differentiated solution grades where margins and switching costs are higher; evaluate partnerships with incumbent technology owners to accelerate time‑to‑market.
-
For private‑equity and strategic acquirers: screen for assets that provide immediate access to specialty grades or regional supply nodes—especially assets with modular ramp potential and validated process knowledge.
-
For R&D and product teams: invest in process intensification and impurity control technologies that reduce energy and solvent footprints; these investments increasingly translate to commercial preference in regulated end markets.
The PW Consulting advantage
Our analysis merges bottom‑up plant economics, primary interviews with market participants, and scenario stress‑testing against realistic feedstock and capacity shocks. The report is intentionally structured as an operational playbook rather than an academic exercise: each analytic module is paired with tactical next steps and template contractual language that procurement and corporate development teams can implement immediately.
Next steps — where to get the full intelligence
This briefing is a strategic “trailer”—it surfaces the structural drivers and pressing choices that should inform 2026 decisions while withholding granular segment disclosures and company revenue tables to protect proprietary modelling integrity. The full report and underlying Excel model include detailed segment‑level forecasts, regional and application tables, supplier revenue breakdowns, and downloadable scenario engines. For organizations that require actionable, transaction‑grade diligence or a tailored workshop to convert these findings into a 90‑day action plan, PW Consulting offers bespoke briefings and data licensing.
To access the complete dataset, segmentation tables, and company‑level financial implications, please visit the source page (report portal) or contact PW Consulting’s advisory desk for an executive briefing scheduled in 2026.
For detailed analysis of this topic, please visit the official page: Sodium Borohydride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Industrial and Institutional Cleaning Market: Strategic Briefing for 2026 Decision‑Makers
Executive snapshot
As PW Consulting’s flagship intelligence on Industrial & Institutional (I&I) Cleaning, this briefing synthesizes the macro trajectory, competitive dynamics, regulatory turning points, and practical playbooks that will shape capital allocation and commercial strategy in 2026. The market we model uses 2025 as the base year and projects through 2032: following steady growth from 2020, the industry is expected to expand at a compound annual growth rate (CAGR) of 4.72% through our forecast horizon. Total industry revenues grew from the low‑50s (USD Million) in 2020 to an estimated USD 63.4 Million in 2025 and are projected to approach the high‑80s (USD Million) by 2032. Those headline figures frame a market that is mature but adaptive — where raw material shocks, regulatory resets, and service‑led differentiation will reallocate value.
Industrial and Institutional Cleaning Market
Why this matters for 2026 planning
-
Timing: 2026 is not just another forecasting year. It is the inflection moment when post‑pandemic hygiene demand normalizes while structural pressures — notably raw material cost volatility and tightened chemical regulation — accelerate margin compression and compel reformulation or premiuming strategies.
Industrial and Institutional Cleaning Market -
Decision leverage: Procurement, R&D prioritization, and portfolio reshaping decisions taken in 2026 will determine supplier relationships and margin profiles for the next business cycle. Firms that preemptively redesign formulations, renegotiate supply terms, or shift toward service/recurring revenue models will capture asymmetric returns as the market rebalances.
Industrial and Institutional Cleaning Market -
Risk window: New regulatory measures and intensified scrutiny of persistent bioaccumulative toxins will drive short‑term compliance costs and medium‑term ingredient substitution. These risks are quantifiable and manageable — but only with scenario‑based planning and prioritized mitigation actions.
Market dynamics shaping 2026
-
Raw material and energy volatility: 2026 has seen pronounced price shocks across key input streams. Leading suppliers have implemented significant price increases in response to supply chain and energy disruptions. These moves compress formulators’ gross margins unless offset by pricing discipline, reformulation, or operational efficiencies.
-
Regulatory tightening: Authorities in major markets are progressing risk evaluations and enacting amendments that target several widely used industrial chemicals. The evolving regulatory environment elevates compliance costs and introduces phase‑out timelines for certain legacy solvents and specialty agents. Firms must prioritize chemical inventory audits, alternative‑ingredient testing, and regulatory scenario modeling.
-
Service and systems shift: End‑users increasingly value integrated solutions — automated dispensing, data‑enabled hygiene verification, and sustainability assurances. This is translating into demand for bundled hardware‑software‑chemical offerings and service contracts that improve retention and margin resilience.
-
Consolidation and concentration: The market shows a material degree of concentration among major global suppliers. Competitive advantage is shaped by scale in raw material procurement, formulation IP, and channel reach into institutional customers. For many buyers and smaller suppliers, this concentration raises supplier dependency and negotiating complexity.
-
Customer segmentation evolution: Buyers — from healthcare and foodservice to manufacturing and commercial property managers — are differentiating requirements around efficacy, traceability, and sustainability. This creates premiuming opportunities for validated high‑efficacy or low‑environmental‑impact formulations, while commoditization risks persist in basic surface care categories.
Competitive landscape — who moves markets
The competitive arena blends ingredient majors, specialty formulators, and hygiene system providers. The list of global players we profile includes multinational chemical suppliers and operational hygiene leaders. Each offers distinct strategic assets:
-
BASF SE (Ludwigshafen, Germany) — a full‑spectrum supplier of surfactants, enzymes and specialty additives, active across both raw material supply and formulation support. Recent unilateral price adjustments underscore the company’s leverage over upstream cost pass‑through dynamics.
-
Ecolab Inc. (St. Paul, Minnesota, USA) — a service‑led hygiene company combining chemical portfolios with dispensing systems and digital monitoring. Its strength is in cross‑industry penetration and contractually recurring revenues.
-
Diversey Holdings Ltd. (Charlotte, North Carolina, USA) — focused on sustainable, tech‑enabled cleaning solutions for healthcare, hospitality and food service, emphasizing lifecycle cost and compliance advantages.
-
The Clorox Company (Oakland, California, USA) — through its professional line, leverages brand recognition and scale in disinfectants and institutional wipes to serve managed facilities and healthcare segments.
-
Dow Inc., Clariant AG, Huntsman, Stepan, Solvay and others — these firms supply critical surfactants, solvents, polymers and additives that feed the formulation layer. Their strategic positioning centers on raw material innovation, stable supply, and sustainability roadmaps.
-
Kimberly‑Clark Corporation — differentiated by nonwoven and wipe products for institutional hygiene, combining material science with distribution strengths.
Together, this cohort controls a substantial proportion of professional‑grade supply and sets the market’s price and innovation agenda. Recent public moves — notably large price increases by a major provider to offset material and energy cost volatility — illustrate the speed at which upstream shocks can feed through to end markets.
Report contents — actionable intelligence (what’s inside)
Our full market study is built as a practitioner’s toolkit. Highlights include:
-
Top‑down and bottom‑up market sizing with transparent assumptions (base year 2025), and an integrated model projecting to 2032 using a 4.72% CAGR scenario plus high/low cases for sensitivity testing.
-
Supply chain stress testing: supplier concentration analysis, critical‑raw‑material mapping, and a supplier risk heatmap that identifies single‑source exposures and substitution pathways.
-
Regulatory impact matrix: scenario narratives and quantified P&L impacts for likely regulatory outcomes, including compliance timelines and cost pathways for ingredient substitution.
-
Price and margin playbooks: tactical options for cost recovery (contract terms, indexation, tiered pricing), product mix optimization, and route‑to‑market adjustments for 2026 shocks.
-
Technology and service monetization frameworks: go‑to‑market blueprints for transitioning from product sales to recurring revenue via dispensing systems, SaaS sanitation verification, and managed services.
-
M&A & partnership lens: target profiles, valuation heuristics for strategic and financial buyers, and integration checklists for technology or raw material acquisitions.
-
Customizable dashboards and Excel models for board presentations and investment committees that help quantify tradeoffs across price, volume, and margin scenarios.
Strategic imperatives for 2026
-
Lock in upstream protection: Negotiate multi‑year supply contracts with index mechanisms, qualify secondary suppliers, and accelerate testing of alternative chemistries to reduce exposure to single‑source price spikes.
-
Prioritize regulatory preparedness: Build a short list of likely ingredient phase‑outs, fund accelerated substitution R&D for the most at‑risk formulations, and establish regulatory monitoring to shorten reaction time.
-
Shift to service‑led models where feasible: Pilot automated dispensing and hygiene verification offerings with high‑value customers to transition a portion of revenue to recurring streams that are more resilient to raw material swings.
-
Recalibrate pricing architecture: Move from across‑the‑board hikes to differentiated pricing tied to formulation cost, efficacy claims, and service bundling to preserve volume in price‑sensitive accounts.
-
Invest in data and traceability: Deploy batch‑level traceability and performance analytics to support premium claims (sustainability, efficacy) and to defend pricing to institutional buyers.
-
Prepare M&A and partnership options: Identify bolt‑on targets that accelerate access to sustainable chemistries, digital dispensing, or regional distribution networks to shore up market position as competitors pursue consolidation.
How to use this briefing — practical next steps
-
Operational leaders: run a 90‑day supplier audit and a 180‑day reformulation pipeline for exposed SKUs; prioritize negotiations with top suppliers and model cash flow impact of various indexation formulas.
-
Commercial teams: segment customers by price elasticity and service appetite; pilot premium service bundles with a subset of accounts to test willingness to pay and churn impact.
-
R&D and sustainability leads: fast‑track testing of non‑restricted chemistries and allocate validation resources to high‑volume institutional applications that face imminent regulatory risk.
-
Finance and corporate development: use the report’s valuation heuristics and scenario outputs to assess opportunistic M&A or partnership plays that can be executed before competitors reposition.
Final note — why you should read the full report
This briefing outlines the strategic topography of the I&I cleaning market as you enter 2026, but intentionally omits granular regional and application‑level distributions that drive transactional decisions. The complete PW Consulting report delivers those subsegment matrices, supplier‑by‑sku exposure tables, and downloadable scenario models designed for direct use in procurement negotiation rooms and board decks. If your 2026 planning requires executable detail — not just directional intelligence — the full study contains the calibrated numbers and playbooks to act decisively.
For executives preparing budgets, negotiating with suppliers, or evaluating product and service pivots, the right combination of macro outlook, supplier intelligence, and operational playbooks is the difference between cost pass‑through and market share capture. PW Consulting’s full Industrial & Institutional Cleaning Market study provides that combination — ready to be deployed in Q1 2026 planning cycles.
For detailed analysis of this topic, please visit the official page: Industrial and Institutional Cleaning Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Quartz Stone Market Poised for 11.6% CAGR in 2026–2032
By pmarketresearch, 2026-07-13
Quartz Stone Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Chief Industry Analyst, I present an executive preview of our latest Quartz Stone Market study. This note is deliberately structured as a strategic “trailer”: it demonstrates the analytical depth and practical orientation of our research while withholding the granular segment tables and proprietary breakdowns that are included in the full report. Use this briefing to assess the study’s relevance for 2026 planning — and to decide which parts of the full intelligence you will need to unlock competitive advantage.
Quartz Stone Market
Market snapshot: scale, trajectory, and what it means
Using 2025 as the base year, our market-level view frames quartz stone as a growth industry undergoing structural expansion. The global market more than doubled over the 2020–2025 historical window and continues to scale in our forecast horizon. At an 11.6% compound annual growth rate (CAGR) through 2032, the sector is projected to reach a materially larger global valuation by the end of the forecast period. These headline numbers tell a simple story: demand drivers remain strong and investor attention will intensify.
Quartz Stone Market
For corporate strategists, three macro takeaways follow immediately:
Quartz Stone Market
- Scale creates strategic options: rising market size enables new investment theses for vertically integrated manufacturers, contract fabricators, and branded premium players.
- Growth is not uniform: while headline CAGR is compelling, the growth pattern and margin dynamics differ significantly by route-to-market, product format, and regulatory exposure — the granular view in our report is essential to translate headline growth into profitable choices.
- Time matters: 2026 is a pivotal year for strategic positioning because short-to-medium-term regulatory and trade events will materially alter sourcing economics and go-to-market calculus.
Key demand-side dynamics
Three demand vectors are driving volume and mix shifts:
- Residential renovation and premium new-build demand continue to push consumption of quartz surfaces that emphasize durability and design consistency.
- Commercial and architectural adoption is accelerating where engineered surfaces provide large-format, low-maintenance alternatives to natural stone.
- Spec and certification-sensitive segments (healthcare, hospitality, education) are increasingly selecting products certified to strict low-crystalline-silica and indoor-emissions standards — a feature that changes specification pathways and adds a non-price dimension to competition.
For executives, the lesson is straightforward: product positioning that bundles design, performance, and compliance credentials will capture both premium pricing and lower procurement friction in regulated end-markets.
Supply-side realities and raw-material considerations
Supply-chain dynamics for quartz surfaces are shaped by raw-material sourcing, processing footprint, and capacity utilization across a global value chain. The sector’s upstream is anchored by high-purity quartz production in established pegmatite districts and by the industrial processing steps that create engineered formulations and slabs.
Our research maps current sourcing nodes, processing bottlenecks, and near-term capacity expansions. These maps identify where single-source risk is concentrated and where investment in alternate feedstock or local processing unlocks resilience. Practical applications include prioritized supplier-development programs for fabricators and capital allocation templates for manufacturers considering greenfield or brownfield expansions.
Trade, regulation, and compliance — the 2026 inflection
Recent trade and policy activity has elevated regulatory risk into a core strategic variable. Notable developments include public hearings and policy considerations by U.S. authorities on imports of quartz surface products and an ongoing trade-policy overlay that includes existing tariffs applied to certain origins. Separately, certification regimes (e.g., Greenguard Gold, NSF) and tightening definitions of permissible crystalline silica exposure in residential and public projects are changing procurement specifications.
Implications for 2026 decisions:
- Procurement teams must re-price supplier relationships to incorporate potential safeguard measures and import duty volatility.
- Manufacturers should fast-track product lines that can be certified to stricter health standards if they intend to serve sensitive end-markets.
- Investors and M&A teams need trade-policy scenario overlays embedded in valuation models; an otherwise accretive acquisition can flip if a safeguard remedy reshapes cross-border economics.
Competitive landscape — what the leaders are doing
The quartz surface market remains fragmented relative to many industrial commodities: top-three and top-five concentration metrics indicate substantial room for local champions and nimble innovators. Leading firms exhibit a mix of strategies that illustrate how to compete at scale:
- Cambria (United States) — a family-owned, U.S.-based player that competes on an American-made value proposition, premium design, and brand storytelling. Their emphasis on domestic manufacturing reduces exposure to import tariffs and appeals to projects prioritizing local content.
- Spectrum Quartz (United States) — an engineered-quartz specialist that leverages intellectual property (patents) and proprietary processes to replicate natural veining and premium finishes. Product differentiation through technology is central to protecting margins in commoditizing markets.
- Cosentino (Spain) — a diversified surfaces group with a portfolio that includes mineral-based Silestone and ultra-compact Dekton surfaces. Their multinational footprint and broad application set reflect a strategy of product and channel diversification to capture both architectural and residential demand.
- Dal-Tile (United States) — a tile and surfaces leader that markets quartz under branded lines focused on natural aesthetics and low maintenance. Their integrated distribution network and channel relationships (trade, retail) are defensive advantages in a competitive landscape.
Each of these firms offers a playbook component that incumbents and entrants can adapt: vertical integration to control cost and speed-to-market; proprietary design and IP to defend pricing; certifications and localized production to neutralize trade friction.
Recent events to watch (immediate strategic implications)
- Public hearings and deliberations by U.S. trade authorities on quartz surface imports — these proceedings can lead to safeguard or remedial measures that change the cross-border cost basis for many supply chains.
- Industry product launches and technology rollouts — new engineered collections emphasize realism and design fidelity, challenging natural-stone premium positioning and changing specification conversations.
- Regulatory and standards updates — evolving certification requirements for low-crystalline-silica products will affect acceptability in sensitive end-markets and public procurement.
What the PW Consulting Quartz Stone Market report delivers
Our full study is designed for immediate operationalization by commercial and corporate strategy teams. Highlights include:
- Demand-model workbook (2020–2032) with scenario toggles for trade-policy shocks and adoption curves — ready to integrate into capital planning and sales forecasting systems.
- Supply-chain heat map and supplier-risk matrix that prioritize mitigation actions by probability and impact.
- Pricing and margin model calibrated to raw-material inputs, transport and tariff scenarios, and channel mix assumptions.
- Regulatory-impact playbook outlining certification pathways, compliance timelines, and procurement-spec migration strategies for regulated end-markets.
- Competitor benchmarking and go-to-market blueprints, including a shortlist of strategic partners and acquisition targets (ranked by strategic fit and integration complexity).
- M&A and partnership decision framework tailored for 2026 conditions, with integration checklists and post-close value-capture templates.
To preserve the research value for subscribers, the report intentionally withholds proprietary segment tables and specific region/application revenue splits in this preview. These granular outputs are included in the full deliverable and are presented with both static tables and interactive models to support board-level decision-making.
Strategic recommendations for 2026 — prioritized actions
For leadership teams contemplating choices this year, we recommend a three-tiered agenda:
- Near-term (0–6 months) : Run a rapid tariff and certification stress-test against your top suppliers and largest contracts. Recalibrate procurement terms and hold contingency inventory for critically exposed SKUs.
- Medium-term (6–18 months) : Accelerate product certification pathways for low-crystalline-silica and indoor-emissions standards if you serve healthcare, education, or public projects. Where practical, pilot near-shore or domestic fabrication capacity to de-risk import exposure.
- Strategic (18–36 months) : Evaluate targeted M&A or JV opportunities to secure access to proprietary engineered technologies or to consolidate regional fabrication footprints. Prioritize targets that close gaps in certification, distribution, or IP.
Each of these steps maps directly to templates and models inside our report — from tariff-adjusted margin calculators to acquisition valuation scenarios under multiple trade-policy outcomes.
Why this research is mission-critical for 2026 planning
2026 presents a confluence of accelerating demand, regulatory refinement, and trade policy uncertainty. Organizations that act from insight — not intuition — will preserve pricing power, avoid costly supply disruptions, and convert regulatory compliance into a competitive asset. Our Quartz Stone Market study is structured to inform those actions with data, scenarios, and executable playbooks.
If your 2026 plan includes capital allocation, channel expansion, or M&A in surfaces and stone, this study is a necessary input to de-risk execution and sharpen ROI expectations.
Next step
This preview demonstrates the breadth and practical orientation of PW Consulting’s market research. The full report (base year 2025; historical 2020–2025; forecast 2026–2032) contains the proprietary segmentation tables, interactive models, and supplier shortlists referenced above. For access to the complete intelligence and to schedule a briefing with our advisory team, please visit the PW Consulting Quartz Stone Market page or contact your engagement director.
Strategic decisions in 2026 will determine who captures the next wave of value in the quartz surface industry. Use the right data and scenario tools to ensure your organization is one of them.
For detailed analysis of this topic, please visit the official page: Quartz Stone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Photographic Paper Market to reach USD 187.65 Million by 2032
By pmarketresearch, 2026-07-13
Photographic Paper Market: Strategic Preview for 2026 Decision‑Makers
As companies plan priorities for 2026, the photographic paper market presents a stable-growth, consolidation-aware opportunity set for manufacturers, distributors, and downstream print service providers. PW Consulting’s forthcoming Photographic Paper Market research (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes market dynamics, supply‑chain stress points, regulatory inflection points and competitor strategy into an actionable framework for board-level and business‑unit decisions. This preview explains the research’s strategic value without revealing the granular splits reserved for the full report.
Photographic Paper Market
Data snapshot: a market that is growing — steadily, predictably
- Historical momentum: the market expanded from USD 118.8 Million in 2020 to USD 144.55 Million in 2025, reflecting recovery and professional/personal imaging mix shifts over the pandemic recovery period.
- Near-term projection: our 2026 point forecast is USD 153.55 Million, with a forecast horizon running through 2032.
- Longer-term trajectory: the model embeds a compound annual growth rate (CAGR) of 3.85% across the forecast window (2026–2032), producing an expected market size of USD 187.65 Million by 2032.
- Market structure: concentration metrics indicate a top-three share consistent with a consolidated market (CR3 ≈ 64%), and the top five raise concentration further (CR5 ≈ 72%), signaling that scale and channel reach remain decisive competitive advantages.
Why this report matters for 2026 decisions
- Timing and precision: with 2025 as the base year and monthly/quarterly inputs through early 2026, the forecast captures recent shocks and near‑term policy changes that will affect procurement cycles and CAPEX decisions.
- Actionable supply‑chain intelligence: our cost-driver analysis isolates the key inputs that move margins — pulp, coatings, chemical emulsions, and freight — and models pass‑through scenarios under differing commodity-price regimes.
- Regulatory foresight: the study overlays evolving Extended Producer Responsibility (EPR) requirements and packaging laws on cost and product-design choices, so firms can prioritize compliance-ready investments and circularity initiatives ahead of enforcement timelines.
- Competitive playbooks: we translate competitor capabilities into tactical choices for market entry, premiumization, and channel consolidation that maximize return on capital in a modest‑growth environment.
What’s inside (practical, usable elements)
- Top-down and bottom-up forecasting: transparent modeling with scenario and sensitivity layers (base, upside, downside) so CFOs can stress-test budgets under multiple demand and input-cost trajectories.
- Cost-to-serve and margin benchmarks: granular cost models (raw materials, chemistry, coatings, packaging, logistics) and margin breakouts for premium vs. commodity lines to guide pricing and portfolio pruning.
- Supply‑chain heatmap: supplier concentration, single‑sourcing risks, and near‑term bottlenecks (including pulp and specialty-chemical availability), plus mitigations such as dual‑sourcing and strategic inventory policies.
- Regulatory & circularity playbook: compliance pathways for EPR frameworks, product eco‑design checklists, and business models for closed‑loop and take‑back programs aligned to upcoming legislative shifts.
- Commercial go‑to‑market plans: channel segmentation, dealer economics, and digital marketing prescriptions for premium photographic and fine‑art papers versus volume-oriented consumer channels.
- Deal and partnership checklist: M&A targets typology, integration scorecards, and JV structures to accelerate access to geographic footprints or specialty product lines without excessive capital intensity.
- Risk register and monitoring KPIs: eight leading indicators (commodity indices, EPR milestones, trade measures, distributor defaults) designed for board dashboards and rolling reforecast triggers.
Industry dynamics shaping 2026 strategy
- Input-cost pressure: wood pulp, a core feedstock, remains a material margin driver. The Producer Price Index for wood pulp reached 200.297 in March 2026, a level that raises the breakeven for commodity product lines and accelerates interest in alternate fiber blends and recycled content.
- Regulatory acceleration: multiple U.S. jurisdictions are advancing or enacting EPR schemes for packaging and paper products. These frameworks increase compliance overhead for producers and place a premium on materials that demonstrate lower end‑of‑life costs.
- Premiumization vs. volume: demand for archival-grade and fine-art media has held up better than entry-level consumer segments. Strategic product differentiation — coatings, archival certifications, ink compatibility — can sustain higher margins even as overall growth remains moderate.
- Consolidation opportunities: observed concentration metrics imply that scale matters for distribution and raw‑material purchasing. Mid‑sized players face margin compression unless they identify niche differentiation or partner with larger distributors.
Competitive landscape: who to watch and why
The market exhibits a mix of global incumbents and specialized independents. The full report contains company scorecards and capability matrices; below are concise strategic postures to inform immediate competitive response.
Photographic Paper Market
- Fujifilm Holdings Corporation (Tokyo, Japan — https://holdings.fujifilm.com/en): Strong in silver-halide and archival-grade papers. Their integrated film-to-paper capability and brand reputation make them a natural leader in professional and archival segments.
- Eastman Kodak Company (Rochester, NY, USA — https://www.kodak.com/en/): Focused on professional inkjet and archival media with deep distribution in North America and Western Europe. Kodak’s legacy brand supports premium pricing in professional channels.
- Canon Inc. (Ota, Tokyo, Japan — https://global.canon/en/): Dominant in inkjet media for digital imaging; Canon’s printer ecosystem offers cross-selling leverage for paper and consumables.
- Epson Corporation (Suwa, Nagano, Japan — https://corporate.epson/en/): Specializes in papers optimized for wide‑format and professional inkjet workflows; Epson’s technical alignment with printheads and inks is a competitive moat.
- FOMA BOHEMIA spol. s r.o. (Hradec Králové, Czech Republic — https://www.foma.cz/en): Niche leader in black‑and‑white silver‑ halide products for analog and archival customers; strong credibility in specialist communities.
- ADOX Fotowerke GmbH (Bad Saarow, Germany — https://www.adox.de/en/): Focus on analog photographers with in‑house chemistry and film production; plays to vintage/analog revival trends.
- Hahnemühle FineArt GmbH (Hamburg, Germany — https://www.hahnemuehle.com/en/): Premium fine‑art inkjet media with age‑resistance certifications; a top pick for galleries and museums requiring proven longevity.
- Ilford Imaging Europe GmbH (Bergisch Gladbach, Germany — https://ilford.com/): Premium inkjet and professional printing media with strong brand equity among photographers and labs.
- Mitsubishi Paper Mills Limited (Tokyo, Japan — https://www.mpm.co.jp/eng/): Established in silver‑halide papers and inkjet media; benefits from manufacturing scale and raw‑material procurement capabilities.
- Shantou Xinxie Photo Materials Co., Ltd. (Shantou, China — corporate profile): Supplier of digital photo papers and specialty materials serving regional and export markets; price competitiveness and flexible production are strengths.
- HYMN Image Materials Co., Ltd. (China — https://www.hymn-image.com/): Manufacturer of inkjet and silver‑halide papers for both professional and consumer segments; able to serve high-volume regional demand.
Strategic implications and recommended actions for 2026
- Prioritize procurement resilience: given elevated pulp PPI and transport volatility, adopt a dual‑sourcing strategy, renegotiate indexation clauses, and stress-test supplier SLAs. Maintain a strategic safety stock for critical coatings and emulsions to avoid production downtime.
- Pursue premium adjacency: if your margins are under pressure, accelerate development of archival/fine‑art lines and certified longevity claims that justify price premiums and reduce sensitivity to commodity swings.
- Embed EPR readiness into product development: anticipate packaging and end‑of‑life compliance by 2026–2028. Invest in recyclable or reusable packaging, and pilot take‑back schemes with key retailer partners to reduce future compliance costs.
- Optimize portfolio via SKU rationalization: use our cost‑to‑serve dashboards to retire low-margin, low‑volume SKUs and redeploy working capital into high-margin specialty papers or service offerings (e.g., finishing, printing-as-a-service).
- Consider bolt‑on acquisitions or strategic alliances: for mid‑sized producers, M&A can secure specialty process know‑how or geographic distribution. For larger players, partnerships with fine‑art brands can accelerate premium entry without full integration risk.
- Invest selectively in digital channels and lab automation: target pro‑photographer and institutional buyers with subscription models and value‑added finishing services to create recurring revenue and improve lifetime customer value.
- Measure and report sustainability outcomes: transparent life‑cycle metrics and certified recycled content will be commercial differentiators under expanding EPR regimes and among institutional buyers like museums and universities.
How PW Consulting helps
Our full Photographic Paper Market report delivers the detailed region/application splits, supplier maps, pricing ladders, and competitor scorecards that corporate development, procurement, and strategy teams need to make defensible 2026 investment decisions. This preview intentionally withholds granular segment shares to protect the analytic value that subscribers expect; the full study provides downloadable models and an implementation roadmap tailored to executive needs.
Photographic Paper Market
If your 2026 plan requires defensible scenarios for CAPEX, M&A, or product repositioning — or a compliance-ready pathway for EPR — the complete PW Consulting study converts market signals into executable steps with quantified ROI and risk buffers. Contact PW Consulting to obtain the full report, underlying datasets, and a tailored executive briefing that aligns the market forecast to your balance‑sheet priorities.
For detailed analysis of this topic, please visit the official page: Photographic Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PV Glass Market to Hit USD 51.65B by 2032 at 18.46% CAGR
By pmarketresearch, 2026-07-13
PV Glass (Solar Photovoltaic Glass) Market — 2026 Strategic Preview
As governments accelerate clean-energy targets and module manufacturers chase incremental efficiency gains, photovoltaic (PV) glass has moved from a commoditized input to a strategic raw material. This preview summarizes the strategic value of PW Consulting’s full PV Glass Market study for corporate decision-making in 2026. It highlights the market’s macro trajectory, competitive dynamics, policy inflection points and the practical, playbook-style intelligence that executives will need to convert market growth into durable advantage — while deliberately withholding the granular segmentation tables and plant-level financials that are contained in the full report.
PV Glass (Solar Glass; Solar Photovoltaic Glass) Market
Macro trajectory you must plan around
The PV glass market is on a steep growth path. Our base-year framework (historical 2020–2025; base year 2025) shows the industry accelerating from a multi‑billion dollar market in 2020 to a materially larger market by 2025, and our forecast (2026–2032) projects continued robust expansion. PW Consulting’s forecast shows sustained high‑teens growth over the medium term (the modeled forecast CAGR is 18.46% for the forecast period), producing transformative scale by the end of the decade. That growth is driven by a mix of utility‑scale installations, new module types that demand higher-performance glass, and a renewed policy focus on domestic clean‑tech manufacturing in several large markets.
PV Glass (Solar Glass; Solar Photovoltaic Glass) Market
Why this research matters for 2026 corporate decisions
- Capital allocation: With the market growing rapidly, choices about greenfield versus brownfield capacity, modular line investments (tempering, AR-coating, TCO capability) and timing have multi-year payback profiles. Our study maps where and when incremental capacity is likely to be absorbed under multiple demand scenarios.
- Procurement and price risk: Volatility in key feedstocks and periodic trade interventions can swing landed costs. The report gives a transparent price‑build model and hedging playbook so procurement leads can lock economically sensible multi‑year agreements without overpaying for optionality.
- Supply security for module manufacturers: Module OEMs face a new reality — glass availability and specification choice materially affect cell efficiency and BOS costs. The study supplies supplier scorecards and recommended contracting terms architects and buyers can operationalize in 2026.
- M&A and partnership targets: We identify the profile of acquisition targets and JV structures that generate rapid scale and market access, and include an M&A screening tool that ranks opportunities by strategic fit and integration complexity.
- Regulatory and trade strategy: With tariffs, anti‑dumping remedies and industrial incentives changing rapidly, the research provides a decision checklist for trade counsel and government affairs teams to prioritize lobbying, localization and tariff-mitigation strategies.
What’s in the full report (practical, operational content)
- Top‑line and bottom‑line market forecasts (2026–2032) with scenario variants and sensitivity analysis linked to module demand, glass pricing and feedstock cost curves.
- A supply‑demand model at line and plant level (availability, ramp schedules, utilization thresholds and likely export flows) — presented with visual dashboards and downloadable Excel modules.
- Price‑build and input‑cost model (including soda ash and silica trends), and supplier‑negotiation templates for fixed, index‑linked and hybrid contracting.
- Supplier scorecards and capability matrices (capacity, technology stack: float/tempered/AR/TCO, quality, vertical integration) with an acquisition/partner suitability index.
- Regulatory tracker and policy impact assessment covering tariffs, trade remedies and industrial incentive programs across key markets.
- Capex timelines, typical greenfield and brownfield economics, and a playbook for rapid line commissioning with risk checklists for permitting, utilities and feedstock logistics.
- Three forward scenarios (base, upside, downside), an executive risk matrix, and an actionable 90‑day strategic checklist for executive teams.
Market dynamics and near‑term catalysts
Several forces are converging in 2026 to re‑shape supplier economics and customer strategies:
PV Glass (Solar Glass; Solar Photovoltaic Glass) Market
- Policy-driven localisation: Industrial policies in major economic blocs are nudging procurement and capex towards domestic or preferential suppliers. This is creating near-term demand pockets for locally produced PV glass and encouraging module OEMs to rethink sourcing footprints.
- Trade interventions and tariff timing: Several trade remedies and tariff regimes remain active or are scheduled for review in 2026. These create windows of procurement risk and opportunity for firms that calibrate contracts and inventory proactively.
- Feedstock cost volatility: Soda ash and other raw-material price swings have periodically reset margins. During 2025 soda ash experienced downward pressure from oversupply; procurement teams should bake in scenario buffers, but also seek to capture cost advantages where they appear.
- Technology segmentation: Different glass technologies (ultra‑clear float, AR‑coated, TCO coatings, tempered/textured surfaces) are not interchangeable from a module performance standpoint. Upstream producers that can cost‑effectively deliver specific glass specs will command premium access to high‑value module programs.
- Consolidation and market concentration: The industry exhibits a moderate level of concentration at the top. The three largest players control a significant share of global capacity, and the top five command a clear majority — a structure that influences price discovery, contractual norms and the speed of technology diffusion.
Competitive landscape — strategic implications from the leader set
Understanding incumbent strategies is essential to anticipate capacity moves, pricing behavior and technology adoption. Key dynamics we highlight:
- Xinyi Solar Holdings : A dominant global player with a material share of the market and strong scale in low‑iron tempered glass. Its investments in Southeast Asia capacity expansion are intended to combine cost competitiveness with proximity to major module assembly hubs. For competitors and buyers, Xinyi’s moves mean capacity discipline and aggressive fulfilment timelines—module OEMs should evaluate long‑term supply contracts and contingency plans.
- Flat Glass Group : A large producer prioritizing ultra‑clear float and AR‑coated glass. Its technology focus positions it well to serve high‑efficiency c‑Si module programs. For investors, Flat’s strategy underlines the premium for AR capability in higher‑value segments.
- NSG Group (Nippon Sheet Glass) : With expertise in TCO‑coated products suited to thin‑film technologies, recent commissioning of a TCO line in the United States is a tactical response to thin‑film OEM demand and localization trends. Module manufacturers contemplating thin‑film adoption or expansion should view NSG as a potential strategic partner.
- AGC Inc. : AGC competes on ultra‑clear float and AR coatings designed for high‑efficiency modules. Its product set is attractive to OEMs pursuing incremental efficiency and lower LCOE through optical gains.
- Borosil Renewables : A leading domestic player in India that recently received board approval to expand capacity. The company’s domestic position and agility give it an advantage in a market where trade remedies and import measures materially affect sourcing economics.
- Guardian Industries : With product lines marketed for utility and concentrator applications, Guardian is an important supplier to North American utility‑scale projects and specialized module formats.
Collectively, these firms demonstrate three strategic playbooks that matter for 2026: (1) scale + cost leadership, (2) technology differentiation (AR/TCO/textures), and (3) geographic/localization plays aligned with trade policy. Your response should be calibrated to which playbook your company can credibly aspire to.
Scenario planning & risk matrix (executive highlights)
- Base case: Continued strong demand growth consistent with high‑teens CAGR in the forecast window; orderly capacity additions and moderate feedstock price movements. Contracts and procurement strategies that lock multi‑year volumes at indexed prices perform well.
- Upside: Faster module adoption and higher‑than-expected deployment cause a temporary tightness in supply for premium glass specs. This scenario favors firms with agile capacity expansions, fast commissioning, or exclusive off‑take agreements with module OEMs.
- Downside: Prolonged trade restrictions, delayed tariffs expirations or sharp raw‑material inflation compress margins and re‑orient flows towards protected/domestic suppliers. Here, companies with diversified supplier bases and in‑region production win.
90‑day playbook for 2026 executive teams
- Quantify exposure: Map your volume exposure to top suppliers and to products that have differentiated specs (AR, TCO, textured). Run the supplied sensitivity templates for price and lead‑time shocks.
- Secure optionality: Negotiate layered contracts (short‑term float + long‑term tranche) and include force‑majeure and tariff‑pass‑through clauses where appropriate.
- Capex prioritization: Re‑test any planned greenfield investments against our utilization thresholds and ramp‑risk checklist; consider brownfield acquisitions to accelerate time‑to‑market.
- Regulatory engagement: Align government affairs and procurement around the policy windows available in 2026 — especially where local content rules or incentives materially change landed cost economics.
- Competitor watch: Track announced and rumored capacity moves from leading players and module OEM programs that require premium glass; prioritize intelligence that impacts your 18‑month supply visibility.
Conclusion — the decision moment for 2026
For executives planning capital, procurement and market expansion in 2026, PV glass is no longer a background commodity risk — it is a strategic lever. PW Consulting’s full market study combines forecast rigor (2026–2032 outlook and an 18.46% forecast CAGR), supplier intelligence, regulatory tracking and executable playbooks to convert market trends into discrete decisions. The public preview above demonstrates the type of thinking we apply; the full report contains the detailed segmentation, plant‑level timelines, supplier scorecards, price models and Excel tools you will need to operationalize a winning 2026 strategy.
To access the complete dataset, model files and our confidential supplier scorecards that underpin the recommendations in this preview, visit the PW Consulting report page or contact our industry team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: PV Glass (Solar Glass; Solar Photovoltaic Glass) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Metal Bellows Market to Reach USD 326.1 Million by 2032 at 6.2% CAGR
By pmarketresearch, 2026-07-13
Metal Bellows Market — 2026 Strategic Preview: Trajectory, Risks, and Executive Playbook
As companies prepare budgets and product roadmaps for 2026, understanding where the metal bellows market is headed — and why — becomes a practical imperative. Our latest PW Consulting market research uses a 2025 base year and a 2026–2032 forecast window to translate technical complexity into boardroom-ready choices. The headline: the global metal bellows market is on a steady expansion path at roughly a 6.2% compound annual growth rate, rising from a mid‑hundreds USD million base in 2025 to a materially larger industry by the early 2030s. This preview explains why that growth is credible, where strategic risk clusters will concentrate, and how manufacturers, OEMs, and tiered suppliers should prioritize investments in 2026 to capture value.
Metal Bellows Market
Why 2026 is a Pivotal Year for Strategy
Three converging forces make 2026 a strategic inflection point. First, demand drivers across high‑precision segments — aerospace, semiconductor, and energy — are recovering into structurally higher baselines following cyclical softness earlier in the decade. Second, regulatory tightening and updated harmonized standards are raising compliance thresholds, imposing engineering and testing costs but also creating barriers to entry that incumbent producers can exploit. Third, raw material volatility and supply chain consolidation are compressing supplier options and compressing margin levers for producers who cannot adapt their procurement and design strategies.
Metal Bellows Market
For executives, the business question is straightforward: do you treat 2026 as a year to defend margin through operational efficiency, or a year to invest in capability upgrades (e.g., edge‑welding automation, qualification labs) that will underpin growth through the forecast horizon? The optimal path depends on your exposure to regulated, high‑value applications and on your relative position in the supplier concentration curve.
Metal Bellows Market
Market Trajectory: A Demand‑Side Synthesis
-
Growth profile: The market’s steady mid‑single‑digit CAGR reflects a mix of resilient replacement demand and incremental new demand from electrification, additive manufacturing supply chains, and higher‑temperature applications. The forecast envelope suggests a consistent climb from the 2025 base year into the early 2030s, driven by applications that value reliability and materials performance more than raw price.
-
Application mix matters: While commodity‑grade bellows continue to compete on price, the fastest value accrual occurs where design margins are defensible — specialty alloys, tight tolerances, and certified expansion joints for pressure systems. Buyers in regulated industries are willing to pay for demonstrated qualification and traceability.
-
Concentration signal: Market concentration data show a modestly consolidating industry: the top three and top five suppliers account for a meaningful share of revenue, underlining both the scale advantages of established players and the strategic room for regional or technical specialists to capture niche premium positions.
Competitive Dynamics — Who Wins and Why
The competitive landscape is heterogeneous, composed of long‑established western engineering houses, specialist U.S. edge‑welded producers, and cost‑focused manufacturers in Asia. Each cluster has distinct strategic playbooks:
-
Heritage engineering houses (e.g., UK and U.S. specialists): They win on application expertise, certification track records, and relationships in aerospace and power generation. Their chief advantage is the ability to monetize integrated assemblies and certified testing packages for safety‑critical uses.
-
High‑precision U.S. suppliers: These firms often focus on edge‑welded and electroformed bellows tailored to semiconductor and vacuum applications. Their proximity to key OEMs and control over manufacturing tolerances support premium pricing in cleanroom and vacuum environments.
-
Volume and cost players in Asia: Competitive on price and lead times for standard expansion joints and corrugated compensators, these producers expand through industrial piping and marine opportunities. Their trajectory depends on moving up the value chain via certifications and export credentials.
From a 2026 decision perspective, incumbents should prioritize: (a) accelerating qualification pathways that capture regulated contract wins, (b) selectively automating processes that reduce unit cost without degrading certification capability, and (c) tightening supply agreements for critical alloys to insulate margins.
Regulation, Standards and Certification: The New Baseline
Regulatory changes are not theoretical — they alter procurement and qualification calendars. The recent European harmonized standard for metal bellows expansion joints, updated into the mid‑2020s, tightens safety and testing expectations for pressure applications. Simultaneously, long‑standing directives covering pressure equipment continue to inform design verification and product liability exposure.
Implication for 2026: suppliers that already embed certified engineering processes will outcompete newcomers in regulated tenders. Buyers should demand evidence of harmonized standard compliance early in the RFQ phase to avoid costly late‑stage rework. Investors evaluating M&A opportunities should stress‑test target portfolios against the incremental CapEx and OPEX needed for compliance.
Raw Materials and Cost Volatility
Material choice drives performance and margin. Stainless steels remain the workhorse for many applications, but nickel and titanium alloys dominate where heat and chemical exposure demand superior properties. Those alloys introduce two operational realities: longer lead times and higher unit cost; and in some cases, slower approval cycles when used in regulated assemblies.
For 2026 planning, procurement teams must shift from reactive spot buying to multi‑tiered sourcing strategies: lock in strategic contracts for critical alloys, develop validated secondary suppliers, and explore alloy substitution where technically feasible. Engineering teams should quantify lifecycle benefits (reduced maintenance, longer MTBF) to justify alloy premium in customer quotes.
Practical Contents of the Full Report (What You Get)
Our full PW Consulting Metal Bellows report is designed for immediate operational use by strategic planners, commercial teams, and M&A professionals. It includes:
-
Robust market sizing and forward projections using a base year of 2025 and a forecast period through 2032, with transparent methodology and sensitivity scenarios;
-
Buyer decision maps for aerospace, semiconductor, oil & gas and power generation purchasers — including qualification timelines, sample inspection protocols, and contract negotiation levers;
-
Supply chain heat maps that identify single‑source risks, key alloy exposures and logistics bottlenecks;
-
Actionable pricing playbooks aligned to product type and application criticality, designed to help commercial teams defend margin while competing on value;
-
Scenario planning modules that quantify the P&L impact of certification costs, alloy price shocks, and demand shifts across high‑value end markets;
-
A competitive intelligence annex profiling leading suppliers with capability matrices, strategic strengths, and likely near‑term moves;
-
Integration checklists for M&A and partnership diligence, including recommended warranty frameworks and post‑acquisition integration milestones.
Company‑Level Strategic Readouts
Based on recent public developments and capability signals, the mid‑2020s competitive battlefield will reward firms that combine certification agility with focused product differentiation:
-
Specialist edge‑welded providers that serve aerospace and semiconductor clients should deepen engineering partnerships with major OEMs, institutionalize co‑development frameworks, and invest in cleanroom qualification racks.
-
Manufacturers of expansion joints and piping compensators should emphasize lifecycle cost models for buyers — showcasing inspection intervals and failure‑mode economics rather than competing solely on list price.
-
Regional manufacturers should prioritize accredited testing and export compliance to access high‑value western tenders, while also exploring modular manufacturing arrangements with global partners.
Recent Developments — Tactical Signals to Watch
Two developments provide immediate tactical cues: a new product line launch focused on high‑temperature applications by an established supplier, and the publication of an updated European harmonized standard for metal bellows used in pressure applications. Together they underscore a larger theme — technical innovation and regulatory alignment are co‑evolving, and firms that can demonstrate both will command privileged access to regulated projects.
How to Use This Research in a 2026 Playbook
-
For CEOs and CFOs: stress‑test CapEx plans against certification and alloy price scenarios included in our sensitivity modules. Use the market trajectory to justify selective capacity investments and to set realistic revenue milestones across regulated vs. commodity segments.
-
For Heads of Product and Engineering: map product roadmaps to buyer qualification cycles — prioritize resources for products with the best combination of technical defensibility and addressable market growth.
-
For Commercial Teams: rework RFP templates to require early proof of compliance with applicable harmonized standards; adopt value‑based quoting for safety‑critical assemblies.
-
For M&A and Partnerships: use the competitive annex and integration checklists to identify acquisition targets that close capability gaps (certification, alloy processing, application expertise) rather than simply adding volume.
Next Steps — Accessing the Full Intelligence
This preview is expressly structured to demonstrate analytic depth while preserving the granular segmentation and proprietary model outputs for the full report. If your strategic planning for 2026 depends on differentiated positioning — whether through technology investment, go‑to‑market changes, or M&A — the complete PW Consulting Metal Bellows Market study contains the structured scenarios, supplier scorecards, and procurement playbooks you will need.
Contact PW Consulting to arrange an executive briefing and to obtain the full dataset and modelling tools that underpin the conclusions summarized here. Use the briefing to align 2026 budgets, prioritize capability investments, and operationalize the scenarios most relevant to your end‑market exposure.
For detailed analysis of this topic, please visit the official page: Metal Bellows Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Mechanical & Electronic Fuzes Market to Reach USD 2,010M in 2025 (CAGR 5.8%)
By pmarketresearch, 2026-07-13
Mechanical and Electronic Fuzes: Strategic Imperatives for 2026 — A PW Consulting Preview
The mechanical and electronic fuzes market is transitioning from a component-centric, cost-managed sector into a strategic fulcrum for defense procurement, industrial policy and alliance-level supply-chain resilience. Our latest market study — base year 2025 — frames that transition with quantitative clarity and operationally focused insights. In 2025 the market is estimated at USD 2010 Million (report unit: Million USD). Under the scenarios modelled for 2026–2032, a compound annual growth rate (CAGR) of 5.8% drives the market through near-term volume and capability inflections, creating a multiyear window for decisive commercial and industrial action.
Mechanical and Electronic Fuzes Market
Why this study matters to executives in 2026
- Timing: 2026 is the inflection year when procurement backlogs, component bottlenecks and emergent regional production capacity converge. Decisions taken this year on sourcing, capacity expansion and industrial partnerships will lock in cost and availability profiles for the next 5–8 years.
- Risk-management: Recent policy moves and supply constraints have created asymmetric risks across the fuze value chain — from rare earths and magnet supply to microelectronic lead times — making proactive mitigation essential to sustain readiness and program schedules.
- Opportunity: Technology maturation in proximity sensing, safety-and-arming (S&A) devices and electronic miniaturisation opens new product and retrofit agendas. Firms that combine supply assurance with targeted R&D stand to capture premium positions as customers demand smarter, safer munitions.
Market dynamics at a glance (strategic frame, not raw segmentation)
- Steady growth, uneven distribution: While the headline market expands at mid-single-digit CAGR, growth pockets driven by modernization programs, munition recapitalization and new ammunition types create differentiated demand by product families and functions. The overall trajectory offers scale for incumbents and an opening for well-capitalised entrants.
- Fragmented competitive structure: Concentration metrics show a market that is not highly concentrated — market leadership exists, but no single player dominates. This fragmentation amplifies opportunities for consolidation, strategic alliances and capability-focused M&A.
- Procurement and qualification friction: Long qualification and integration cycles for new fuzes continue to delay the practical delivery of capability, even when design and production ramp-up occur. Program managers must reconcile acquisition cycles with industrial lead-times and certification windows.
Supply chain and regulatory headwinds shaping 2026 choices
- Critical materials and export controls: Export restrictions on key rare earths and magnetic materials implemented by major producers, together with a proliferation of import/export constraints on critical minerals, have materially increased sourcing risk. Buyers and suppliers must account for traceability and alternative materials in contract and design decisions.
- Semiconductor scarcity: Extended lead times for semiconductor components (industry data indicating multi-month waits) are influencing production cadence, particularly for electronic fuze microcontrollers and sensor arrays. Program-level buffers and supplier co-investment are now pragmatic necessities.
- Trade policy volatility: Rising trade frictions have pushed some customers to front-load orders and re-evaluate supplier footprints. This behavioral change affects pricing dynamics, inventory strategies and the feasibility of single-source models.
- Qualification complexity: NATO and allied qualification regimes—complex and sometimes protracted—mean that technical readiness does not guarantee field deployment. Early engagement with certification authorities and modular testing strategies reduce calendar risk.
Competitive landscape — what incumbents and challengers are doing
The market roster includes specialised micromechanics houses, systems integrators and major defense primes. Established European and North American manufacturers remain core suppliers for high-reliability applications, while regional producers and new-capacity entrants are expanding to capture localized demand.
Mechanical and Electronic Fuzes Market
- Strategic partnerships and local production: Recent examples include a Central/Eastern Europe production joint venture established to produce electronic fuzes for large-calibre ammunition, paired with long-term alliance contracts. Such moves signal a pragmatic shift: close-to-customer production to shorten logistics, comply with local-content expectations and secure program awards.
- Industrialisation and indigenisation: National defence industrialisation programs are accelerating local assembly and mid-life support capabilities. Where successful, these programs reduce foreign-dependency risk but introduce technology-transfer negotiations and IP management challenges.
- Prime-led advanced fuze development: Large systems integrators continue to invest in sensor fusion, safety-and-arming improvements and digital integration (e.g., smart arming/logistics data) to differentiate offerings for precision munitions. These technology bets increase value-capture beyond pure manufacturing.
Selected strategic moves in the marketplace (indicative)
- Joint ventures to scale capacity and secure contracts in alliance markets — an example of firms combining regional presence with established technology.
- Factory expansions and new assembly lines for electronic fuzes, sometimes formalised through multi-year manufacturing contracts with technology partners — a clear signal that long-term production lanes are being created to support large programs.
- Partnerships between speciality micromechanical firms and systems integrators to blend precision mechanical design with electronic capability, thereby reducing integration friction for customers.
What PW Consulting’s full report delivers (actionable, execution-oriented)
Our comprehensive study translates the market’s macro trajectory into practical tools decision-makers can use in 2026:
Mechanical and Electronic Fuzes Market
- Proprietary demand-forecast model with scenario toggles for geopolitical disruption, policy shifts and component lead-time stress; this model is designed for procurement planning and capex timing.
- Supplier and capability maps detailing where specific technologies and manufacturing competencies reside (including redundancy and single-point-of-failure analysis), enabling targeted sourcing and supplier development programs.
- Technology roadmaps for mechanical and electronic fuzes, aligned with integration and certification milestones to compress fielding timelines where possible.
- Commercial playbooks — procurement templates, contract language to hedge raw-material exposure, recommended inventory and contractual approaches to mitigate semiconductor and magnet lead-time risk.
- Deal flow and M&A heatmaps highlighting potential consolidation targets and partnership archetypes, paired with valuation and integration considerations tailored for strategic buyers.
- Operational checklists for program managers: qualification risk matrices, recommended test/regression plans and a phase-gated timeline to synchronise supply ramp-up with qualification milestones.
Strategic choices for 2026 — recommended actions
- Prioritise supply-path diversity now: Locking in multiple qualified suppliers across geography and process tiers reduces the probability of program-level stoppages driven by single-source failures or export constraints.
- Contract for predictability: Move from spot buys to multi-year capacity agreements with clear escalation and pass-through provisions for critical materials; couple contracts with technical collaboration to secure priority allocation.
- Invest selectively in localisation or co‑investment: Where program awards hinge on sovereign supply, co-investment in regional production — possibly via JVs — is often the lowest-risk route to winning business while protecting IP.
- Accelerate modular design and digital verification strategies: Modular S&A designs and broader use of digital twins and hardware-in-the-loop testing can materially shorten qualification cycles and reduce rework costs.
- Embed raw-material and component intelligence into sourcing decisions: Integrate raw-material traceability and alternative-material qualification into engineering and procurement workflows to respond quickly to export restrictions and tariff shocks.
What to expect if you delay
Delay in 2026 risks three outcomes: higher spot-market exposure to scarce components, missed delivery windows due to protracted qualification, and disadvantaged contract terms as suppliers prioritise partners with secured, forward-committed volume. Given the market’s fragmentation and the relatively modest concentration among top players, those who move early to build complementarities between production assurance and technology leadership can capture outsized position gains.
How PW Consulting can help
We position this study as a “decision acceleration” tool for executives and program managers. The public preview you’re reading demonstrates methodological depth and market-wide perspective; the full report contains the executable detail — supplier lists, scenario-tuned forecasts, operational playbooks and deal-ready analyses — required to convert insight into contract or capex decisions in 2026.
For teams planning procurement commitments, industrial investments or M&A activity this year, the full study reduces uncertainty by translating macro trends (growth trajectory and supply constraints) into discrete operational choices and timelines.
Next step
PW Consulting’s full Mechanical and Electronic Fuzes Market report provides the detailed segment analytics, supplier benchmarking and executable playbooks referenced here. Access the complete report to obtain the granular, source-level data and practical tools needed to implement the strategies outlined in this preview.
For detailed analysis of this topic, please visit the official page: Mechanical and Electronic Fuzes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com