

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: 1,2‑Pentanediol Market to Grow at 6.5% CAGR (2026–2032)

Strategic Outlook — 1,2-Pentanediol Market: A 2026 Decision Brief
Executive snapshot
As companies calibrate capital allocation and commercial strategies for 2026, 1,2-pentanediol (pentylene glycol) is emerging as a strategic intermediate that links shifts in personal care formulation, sustainability mandates, and petrochemical feedstock volatility. Our PW Consulting study — anchored on a 2025 base year, a 2020–2025 historical review, and a 2026–2032 forecast horizon — synthesizes market economics, supplier dynamics, regulatory friction points, and technology pathways to create an operationally useful roadmap for decision makers.
1,2-Pentanediol Market
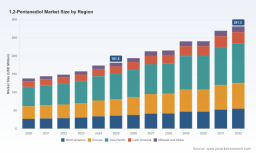
Key macro takeaways you need immediately: the market has grown steadily from the early 2020s into mid-decade and, under our base forecast trajectory, is set to continue expanding through 2032 at a compound annual growth rate aligned with mid-single digits. That trajectory translates into meaningful scale expansion for incumbents and new entrants alike, while also increasing the economic incentives for vertical integration and feedstock innovation.
1,2-Pentanediol Market
Why 2026 is a strategic inflection
-
Convergence of demand drivers: Growth in personal care formulations, renewed R&D in pharmaceutical excipients and pesticide intermediates, and incremental uptake in industrial applications are collectively broadening the total addressable market.
1,2-Pentanediol Market -
Sustainability as a differentiator: Biobased and upcycled feedstock routes have shifted from marketing plus to commercial necessity for a set of premium buyers; buyers are increasingly willing to pay for certified, lower-carbon inputs.
-
Supply-side complexity: Price and availability of traditional petrochemical feedstocks have become more volatile due to regional geopolitical events, feedstock export constraints, and shifts in naphtha/LPG/natural gas markets — increasing the value of diversified sources and regional footprint resilience.
-
Regulatory tightening: A complex regulatory landscape across cosmetic, pharmaceutical and food-contact pathways is creating longer supplier qualification cycles and raising the bar for documentation, testing, and certification.
Market trajectory (what the numbers say)
Our historical reconstruction (2020–2025) demonstrates steady recovery and expansion through mid-decade, reflecting both volume growth and premiumization in specific applications. Using 2025 as the base year, the report models multiple forecast scenarios across 2026–2032. Under the central case, the market grows at a mid-single-digit CAGR to reach materially higher scale by 2032. These aggregated dynamics mask pockets of accelerated growth — and pockets of cyclicality — that are explored in the full study via scenario banding and sensitivity testing.
Key strategic implications for 2026 planning
-
Procurement & commercial protection: Buyers should reassess contract tenors and indexation clauses. The combination of feedstock volatility and regional supply interruptions raises the value of blended procurement strategies: longer-term agreements for core volumes, combined with flexible spot exposure for opportunistic sourcing.
-
Capacity investment decisions: For manufacturers and private-equity owners, the question is not simply whether to add capacity, but where (geography & grade) and which technology route to prioritize. Biobased production lines command a price premium in some customer segments, but they also require distinct feedstock certifications and longer qualification timelines.
-
Product & portfolio strategy: C-suite teams should identify which grades and formulations will capture the sustainability and performance premiums over the next two to four years. Cosmetic-grade and specialty derivatives tied to lower-carbon feedstocks are structurally advantaged with certain global buyers, but industrial applications remain cost-sensitive and exposed to petrochemical price swings.
-
M&A and alliance playbook: The market’s structural maturation favors bolt-on acquisitions that provide feedstock security, regional market access, or specialized downstream capabilities (e.g., formulation services for personal care). Joint development agreements and tolling partnerships are an efficient way to de-risk new biobased routes without committing full capex.
-
Regulatory & quality assurance: Expect extended supplier qualification timelines. Firms entering or scaling in this market must invest in regulatory dossiers, third-party testing, and traceability systems to meet customer and jurisdictional requirements.
Competitive landscape — players to watch
The supplier map is a mix of specialized regional producers and global ingredient houses that are moving up the value chain. A few differentiated strategic plays emerge from recent corporate activity and public disclosures:
-
Large ingredient houses that pair marketing reach with dedicated biobased production units are using that capability to accelerate adoption among multinational personal care brands. Dual-site manufacturing and demonstrable upcycling credentials are serving both reliability and sustainability narratives.
-
Specialized chemical manufacturers in Asia continue to anchor cost-competitive supply and quick fulfillment for industrial users, while also investing in regional biobased capacity to capture higher-margin cosmetic demand.
-
Technology differentiation is increasingly commercial: product provenance (e.g., upcycled sugarcane bagasse) and vertically integrated feedstock pathways are shortening supplier selection lists for premium customers.
Recent notable developments include the commissioning of additional biobased production capacity by a major ingredient supplier in Europe, modeled on an existing U.S. site, and industry recognition for sustainability credentials that emphasize upcycled agricultural residues. These moves signal a strategy shift from pilot-scale sustainability proofs to full commercial roll-outs — and they will materially alter supplier selection dynamics for multinational buyers.
Risk map — what keeps CEOs and procurement chiefs awake
-
Feedstock and price volatility: Exposure to n-pentene and other petrochemical-derived inputs creates margin vulnerability for producers and price risk for buyers during geopolitical disruptions.
-
Certification bottlenecks: Sourcing biobased or upcycled feedstocks requires validated chains of custody; delays in certification slow customer qualification and limit near-term market share gains.
-
Regulatory heterogeneity: Diverging rules across cosmetic, pharmaceutical and agrochemical jurisdictions require bespoke compliance strategies, increasing time-to-market.
-
Concentration effects: While a small set of suppliers offers scale and branded biobased grades, regional suppliers retain influence in cost-sensitive segments. This creates a two-speed market where premium and commodity pathways coexist.
What our PW Consulting report delivers — the practical toolkit
This study is designed as an actionable playbook for executives who must make capital, sourcing or go-to-market decisions in 2026. Key deliverables include:
-
Scenario-based demand and price models for 2026–2032, with sensitivity to feedstock price paths and regulatory outcomes.
-
Supply-side intelligence: vetted supplier profiles, capacity maps, and qualitative assessments of operational resilience and feedstock security.
-
Commercial tools: supplier scorecards, contract clause templates (tenor, indexation, force majeure), and a bidding framework for RFP design.
-
Investment decision frameworks: unit-economics templates for greenfield vs. brownfield investments, and an M&A screening matrix that prioritizes feedstock access, technology fit, and customer overlap.
-
Regulatory playbook: jurisdiction-level compliance checklists, expected qualification timelines, and testing/validation roadmaps for cosmetic and pharmaceutical applications.
-
Risk management artifacts: hedging strategies, procurement levers, and a supply-disruption response playbook aligned to board-level crisis scenarios.
To preserve commercial value for subscribers and prospective buyers, the report intentionally positions headline macro trajectories and strategic implications in this brief while retaining the full, granular segmentation tables, supplier-level financials, and proprietary demand models in the full deliverable.
How to use the analysis in 2026 decision cycles
-
Board and Investment Committees — use the scenario models to stress-test capex proposals and to define go/no-go thresholds tied to feedstock price and certification timelines.
-
Commercial & Procurement — reframe supplier negotiations around blended supply strategies and include sustainability credentials in commercially weighted scorecards.
-
R&D and Product Teams — prioritize formulation work that leverages biobased grades where margin uplift is validated; accelerate customer trials with dual-sourced samples to shorten qualification windows.
-
M&A teams — prioritize targets that provide immediate feedstock security or accelerate biobased manufacturing scale without long permitting lead times.
-
Risk & Compliance — build a compliance calendar mapped to customer qualification lead times and regulatory milestones to avoid lost sales from protracted approvals.
Final perspective — an operational judgment
The 1,2-pentanediol market in 2026 is less about an either/or between petrochemical and biobased supply and more about orchestration: producers, buyers and investors who align feedstock strategy, regulatory preparedness, and customer qualification timelines will capture the lion’s share of near-term upside. The market’s growth path creates both opportunity and complexity — rewarding those who use granular supplier intelligence, scenario planning, and disciplined procurement playbooks.
PW Consulting’s full 1,2-Pentanediol Market report provides the data, models, and executable templates that procurement leads, strategy teams, and corporate development groups need to convert this strategic moment into measurable value. For access to the proprietary segmentation, supplier-level forecasts, and the decision-ready toolkits referenced above, consult the full report page or contact your PW Consulting representative.
For detailed analysis of this topic, please visit the official page: 1,2-Pentanediol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com