

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Metal Bellows Market to Reach USD 326.1 Million by 2032 at 6.2% CAGR

Metal Bellows Market — 2026 Strategic Preview: Trajectory, Risks, and Executive Playbook
As companies prepare budgets and product roadmaps for 2026, understanding where the metal bellows market is headed — and why — becomes a practical imperative. Our latest PW Consulting market research uses a 2025 base year and a 2026–2032 forecast window to translate technical complexity into boardroom-ready choices. The headline: the global metal bellows market is on a steady expansion path at roughly a 6.2% compound annual growth rate, rising from a mid‑hundreds USD million base in 2025 to a materially larger industry by the early 2030s. This preview explains why that growth is credible, where strategic risk clusters will concentrate, and how manufacturers, OEMs, and tiered suppliers should prioritize investments in 2026 to capture value.
Metal Bellows Market
Why 2026 is a Pivotal Year for Strategy
Three converging forces make 2026 a strategic inflection point. First, demand drivers across high‑precision segments — aerospace, semiconductor, and energy — are recovering into structurally higher baselines following cyclical softness earlier in the decade. Second, regulatory tightening and updated harmonized standards are raising compliance thresholds, imposing engineering and testing costs but also creating barriers to entry that incumbent producers can exploit. Third, raw material volatility and supply chain consolidation are compressing supplier options and compressing margin levers for producers who cannot adapt their procurement and design strategies.
Metal Bellows Market
For executives, the business question is straightforward: do you treat 2026 as a year to defend margin through operational efficiency, or a year to invest in capability upgrades (e.g., edge‑welding automation, qualification labs) that will underpin growth through the forecast horizon? The optimal path depends on your exposure to regulated, high‑value applications and on your relative position in the supplier concentration curve.
Metal Bellows Market
Market Trajectory: A Demand‑Side Synthesis
-
Growth profile: The market’s steady mid‑single‑digit CAGR reflects a mix of resilient replacement demand and incremental new demand from electrification, additive manufacturing supply chains, and higher‑temperature applications. The forecast envelope suggests a consistent climb from the 2025 base year into the early 2030s, driven by applications that value reliability and materials performance more than raw price.
-
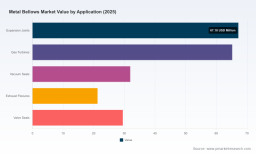
Application mix matters: While commodity‑grade bellows continue to compete on price, the fastest value accrual occurs where design margins are defensible — specialty alloys, tight tolerances, and certified expansion joints for pressure systems. Buyers in regulated industries are willing to pay for demonstrated qualification and traceability.
-
Concentration signal: Market concentration data show a modestly consolidating industry: the top three and top five suppliers account for a meaningful share of revenue, underlining both the scale advantages of established players and the strategic room for regional or technical specialists to capture niche premium positions.
Competitive Dynamics — Who Wins and Why
The competitive landscape is heterogeneous, composed of long‑established western engineering houses, specialist U.S. edge‑welded producers, and cost‑focused manufacturers in Asia. Each cluster has distinct strategic playbooks:
-
Heritage engineering houses (e.g., UK and U.S. specialists): They win on application expertise, certification track records, and relationships in aerospace and power generation. Their chief advantage is the ability to monetize integrated assemblies and certified testing packages for safety‑critical uses.
-
High‑precision U.S. suppliers: These firms often focus on edge‑welded and electroformed bellows tailored to semiconductor and vacuum applications. Their proximity to key OEMs and control over manufacturing tolerances support premium pricing in cleanroom and vacuum environments.
-
Volume and cost players in Asia: Competitive on price and lead times for standard expansion joints and corrugated compensators, these producers expand through industrial piping and marine opportunities. Their trajectory depends on moving up the value chain via certifications and export credentials.
From a 2026 decision perspective, incumbents should prioritize: (a) accelerating qualification pathways that capture regulated contract wins, (b) selectively automating processes that reduce unit cost without degrading certification capability, and (c) tightening supply agreements for critical alloys to insulate margins.
Regulation, Standards and Certification: The New Baseline
Regulatory changes are not theoretical — they alter procurement and qualification calendars. The recent European harmonized standard for metal bellows expansion joints, updated into the mid‑2020s, tightens safety and testing expectations for pressure applications. Simultaneously, long‑standing directives covering pressure equipment continue to inform design verification and product liability exposure.
Implication for 2026: suppliers that already embed certified engineering processes will outcompete newcomers in regulated tenders. Buyers should demand evidence of harmonized standard compliance early in the RFQ phase to avoid costly late‑stage rework. Investors evaluating M&A opportunities should stress‑test target portfolios against the incremental CapEx and OPEX needed for compliance.
Raw Materials and Cost Volatility
Material choice drives performance and margin. Stainless steels remain the workhorse for many applications, but nickel and titanium alloys dominate where heat and chemical exposure demand superior properties. Those alloys introduce two operational realities: longer lead times and higher unit cost; and in some cases, slower approval cycles when used in regulated assemblies.
For 2026 planning, procurement teams must shift from reactive spot buying to multi‑tiered sourcing strategies: lock in strategic contracts for critical alloys, develop validated secondary suppliers, and explore alloy substitution where technically feasible. Engineering teams should quantify lifecycle benefits (reduced maintenance, longer MTBF) to justify alloy premium in customer quotes.
Practical Contents of the Full Report (What You Get)
Our full PW Consulting Metal Bellows report is designed for immediate operational use by strategic planners, commercial teams, and M&A professionals. It includes:
-
Robust market sizing and forward projections using a base year of 2025 and a forecast period through 2032, with transparent methodology and sensitivity scenarios;
-
Buyer decision maps for aerospace, semiconductor, oil & gas and power generation purchasers — including qualification timelines, sample inspection protocols, and contract negotiation levers;
-
Supply chain heat maps that identify single‑source risks, key alloy exposures and logistics bottlenecks;
-
Actionable pricing playbooks aligned to product type and application criticality, designed to help commercial teams defend margin while competing on value;
-
Scenario planning modules that quantify the P&L impact of certification costs, alloy price shocks, and demand shifts across high‑value end markets;
-
A competitive intelligence annex profiling leading suppliers with capability matrices, strategic strengths, and likely near‑term moves;
-
Integration checklists for M&A and partnership diligence, including recommended warranty frameworks and post‑acquisition integration milestones.
Company‑Level Strategic Readouts
Based on recent public developments and capability signals, the mid‑2020s competitive battlefield will reward firms that combine certification agility with focused product differentiation:
-
Specialist edge‑welded providers that serve aerospace and semiconductor clients should deepen engineering partnerships with major OEMs, institutionalize co‑development frameworks, and invest in cleanroom qualification racks.
-
Manufacturers of expansion joints and piping compensators should emphasize lifecycle cost models for buyers — showcasing inspection intervals and failure‑mode economics rather than competing solely on list price.
-
Regional manufacturers should prioritize accredited testing and export compliance to access high‑value western tenders, while also exploring modular manufacturing arrangements with global partners.
Recent Developments — Tactical Signals to Watch
Two developments provide immediate tactical cues: a new product line launch focused on high‑temperature applications by an established supplier, and the publication of an updated European harmonized standard for metal bellows used in pressure applications. Together they underscore a larger theme — technical innovation and regulatory alignment are co‑evolving, and firms that can demonstrate both will command privileged access to regulated projects.
How to Use This Research in a 2026 Playbook
-
For CEOs and CFOs: stress‑test CapEx plans against certification and alloy price scenarios included in our sensitivity modules. Use the market trajectory to justify selective capacity investments and to set realistic revenue milestones across regulated vs. commodity segments.
-
For Heads of Product and Engineering: map product roadmaps to buyer qualification cycles — prioritize resources for products with the best combination of technical defensibility and addressable market growth.
-
For Commercial Teams: rework RFP templates to require early proof of compliance with applicable harmonized standards; adopt value‑based quoting for safety‑critical assemblies.
-
For M&A and Partnerships: use the competitive annex and integration checklists to identify acquisition targets that close capability gaps (certification, alloy processing, application expertise) rather than simply adding volume.
Next Steps — Accessing the Full Intelligence
This preview is expressly structured to demonstrate analytic depth while preserving the granular segmentation and proprietary model outputs for the full report. If your strategic planning for 2026 depends on differentiated positioning — whether through technology investment, go‑to‑market changes, or M&A — the complete PW Consulting Metal Bellows Market study contains the structured scenarios, supplier scorecards, and procurement playbooks you will need.
Contact PW Consulting to arrange an executive briefing and to obtain the full dataset and modelling tools that underpin the conclusions summarized here. Use the briefing to align 2026 budgets, prioritize capability investments, and operationalize the scenarios most relevant to your end‑market exposure.
For detailed analysis of this topic, please visit the official page: Metal Bellows Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com