

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Sodium Borohydride Market to hit USD 232.9 Million by 2032 at 5.7% CAGR

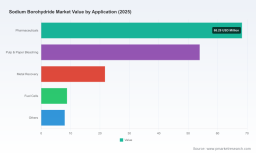
Sodium Borohydride Market: Strategic Briefing for 2026 Decision‑Makers
Executive snapshot
As companies plan for 2026 and beyond, sodium borohydride is moving from a niche reagent toward a strategically important specialty chemical with multiple industrial and clean‑tech touchpoints. Our PW Consulting study—anchored on a 2025 base year and a 2026–2032 forecast horizon—finds the global market expanding at a compound annual growth rate (CAGR) of 5.7%. Measured in USD Million, total market revenue grew from roughly 128.6 in 2020 to 160.7 in 2025 and is projected to reach approximately 232.9 by 2032. These headline numbers conceal an active market architecture: concentrated supply, high technical barriers to entry, and differentiated end‑use dynamics that together create distinct opportunity sets and supply risks for industrial buyers, chemical producers, and strategic investors.
Sodium Borohydride Market
Why this briefing matters in 2026
-
Timing: 2026 is a hinge year. Recent capacity moves by tier‑one producers and elevated attention to hydrogen, pharmaceuticals, and pulp/paper bleaching are reshaping demand composition. Firms that position procurement and capacity strategy this year will capture advantaged access to fast‑growing niches.
Sodium Borohydride Market -
Supply risk: Concentration metrics show a market where the three largest players account for a substantial majority and the top five consolidate an even greater share. This concentration amplifies the impact of single‑site outages, planned expansions, and regional raw‑material constraints on price and availability.
Sodium Borohydride Market -
Investment horizon: Given capital‑intensive synthesis routes and specialized handling needs, greenfield entry is expensive and slow. Strategic decisions in 2026 about capacity expansions, long‑term offtakes, and vertical integration will reverberate through 2032.
Market dynamics and what they mean
-
Upstream raw‑material geography: Sodium borohydride synthesis is materially dependent on boron feedstock (commonly sourced as borax). Global boron reserves are highly concentrated; one country holds the lion’s share of documented reserves. This geological concentration creates an asymmetric supply vulnerability—especially where logistics or export policy shifts intersect with demand spikes.
-
Complex, capital‑intensive synthesis: The standard industrial routes require multiple feedstocks (including sodium hydride and organoboron intermediates) plus advanced process control. This raises barriers to entry, favors incumbents with process know‑how, and limits the pace at which new capacity can be commissioned—an important consideration for firms evaluating near‑term procurement contracts versus longer‑term equity stakes.
-
Demand drivers are diverse and asynchronous: End uses range from pharmaceutical API hydrogenation and specialty reducing applications to paper deinking/bleaching and emerging clean‑energy roles (e.g., as a hydrogen carrier or in fuel‑cell related chemistries). These end markets exhibit different cyclicality, regulatory exposures, and margin profiles—creating both risk diversification and the need for tailored go‑to‑market strategies.
-
Price and margin dynamics: Given capacity concentration and feedstock dependencies, price moves tend to be lumpy and respond to both feedstock shocks and single‑player capacity announcements. Buyers should model scenarios that include regional feedstock disruptions, step‑change demand from a single end market, and staggered ramp‑ups of new production lines.
Competitive landscape — who matters and why
The market is dominated by a set of specialized chemical manufacturers with varied strategic profiles: long‑standing pulp/paper and water‑chemicals incumbents, custom‑synthesis pharmaceutical suppliers, and North American process‑chemical players specializing in safe handling and large‑volume production. Recent noteworthy moves include a mid‑2025 capacity expansion by a major European producer, which illustrates how targeted investment in powder production lines can shift regional supply balances when brought online.
-
Kemira Oyj (Helsinki, Finland) — A differentiated player with both an alkaline aqueous product for pulp and deinking applications and a higher‑purity powdered offering for pharmaceutical/industrial reductions. Their recent decision to add a dedicated powder line at a Finnish site (investment decision in mid‑2025, ramping to full operation around late‑2026) is a strategic example: it addresses quality‑segmented demand and reduces reliance on cross‑border supply for specialty grades.
-
Ascensus Specialties LLC (US) — A large‑scale producer focusing on broad hydride portfolios and industrial reducing agents. Their value proposition centers on scale, regulatory know‑how, and safe handling capabilities—attributes attractive to industrial accounts demanding large, consistent volumes and predictable logistics.
-
Montgomery Chemicals (Conshohocken, PA, US) — A solutions‑oriented supplier with branded sodium borohydride solutions for textile, paper, and wastewater markets. Their strength lies in application engineering and formulated product offerings that reduce customer integration friction.
-
Shandong Guobang Pharmaceutical Co., Ltd. (China) — A supplier of high‑purity hydrides aimed at pharmaceuticals and specialty industries. Their presence underscores the global sourcing dynamics: tight quality specifications in pharma can be met by specialized Asian suppliers, but procurement must evaluate regulatory and supply‑chain risk trade‑offs.
Implications for procurement, operations, and corporate strategy
-
Supplier risk management: With high market concentration and geographically clustered raw materials, organizations should adopt multi‑vector procurement strategies. That includes dual‑sourcing where feasible, retaining spot flexibility for surges, and negotiating capacity reservation clauses for multi‑year needs.
-
Make vs. buy calculus: For companies whose margins are highly sensitive to input availability (e.g., specialty pharma and clean‑tech OEMs), investing in partial vertical integration—such as toll manufacturing agreements, co‑location of reduction steps, or minority stakes in production lines—can be value‑accretive versus exposure to market tightness.
-
Product strategy: The market rewards product differentiation—high‑purity powders for pharma, aqueous formulations for pulp/paper, and packaged solutions for industrial users. Firms should map their margin pools against required handling, regulatory certification, and logistics costs before selecting which product forms to prioritize.
-
Regulatory and sustainability lens: End markets like pharmaceuticals and water treatment place rising emphasis on traceability, impurity control, and environmental footprint. Capital investments that lower lifecycle emissions or improve solvent recovery will increasingly influence customer selection criteria and can command price premium.
What the full PW Consulting report delivers
Our report is designed as a decision‑oriented toolkit for executives preparing 2026 strategies. Key deliverables include:
-
Top‑line market sizing and a year‑by‑year revenue model from 2020 through 2032 (base year 2025; forecast period 2026–2032) with scenario variants driven by end‑market demand shocks and supply interruptions.
-
Proprietary concentration analysis (CR3/CR5) with supplier profiles, capacity maps, and a timeline of announced versus operational lines—essential for procurement contingency planning.
-
Value‑chain and cost‑build models that break down feedstock and synthesis step economics, enabling accurate margin simulations for greenfield, brownfield, and tolling options.
-
Commercial playbooks tailored to buyers, producers, and investors—covering contract structures, hedging approaches, and M&A screening criteria.
-
Regulatory, safety, and sustainability risk matrices, and a prioritized list of technical due‑diligence items for any intended partnership or acquisition.
-
Primary research: interviews with plant operations, procurement heads, and technical R&D leaders across producing regions to validate capacity ramp schedules and commercial intents.
Strategic moves recommended for 2026
-
For buyers with scale exposure: secure rolling offtake agreements with volume flex corridors, build inventory buffers tied to validated safety cases, and pursue supplier collaboration for co‑optimized logistics.
-
For chemical producers: prioritize incremental capacity in high‑purity powder production or differentiated solution grades where margins and switching costs are higher; evaluate partnerships with incumbent technology owners to accelerate time‑to‑market.
-
For private‑equity and strategic acquirers: screen for assets that provide immediate access to specialty grades or regional supply nodes—especially assets with modular ramp potential and validated process knowledge.
-
For R&D and product teams: invest in process intensification and impurity control technologies that reduce energy and solvent footprints; these investments increasingly translate to commercial preference in regulated end markets.
The PW Consulting advantage
Our analysis merges bottom‑up plant economics, primary interviews with market participants, and scenario stress‑testing against realistic feedstock and capacity shocks. The report is intentionally structured as an operational playbook rather than an academic exercise: each analytic module is paired with tactical next steps and template contractual language that procurement and corporate development teams can implement immediately.
Next steps — where to get the full intelligence
This briefing is a strategic “trailer”—it surfaces the structural drivers and pressing choices that should inform 2026 decisions while withholding granular segment disclosures and company revenue tables to protect proprietary modelling integrity. The full report and underlying Excel model include detailed segment‑level forecasts, regional and application tables, supplier revenue breakdowns, and downloadable scenario engines. For organizations that require actionable, transaction‑grade diligence or a tailored workshop to convert these findings into a 90‑day action plan, PW Consulting offers bespoke briefings and data licensing.
To access the complete dataset, segmentation tables, and company‑level financial implications, please visit the source page (report portal) or contact PW Consulting’s advisory desk for an executive briefing scheduled in 2026.
For detailed analysis of this topic, please visit the official page: Sodium Borohydride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com