

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Mechanical & Electronic Fuzes Market to Reach USD 2,010M in 2025 (CAGR 5.8%)

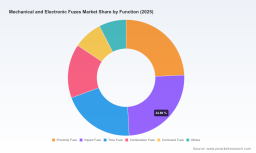
Mechanical and Electronic Fuzes: Strategic Imperatives for 2026 — A PW Consulting Preview
The mechanical and electronic fuzes market is transitioning from a component-centric, cost-managed sector into a strategic fulcrum for defense procurement, industrial policy and alliance-level supply-chain resilience. Our latest market study — base year 2025 — frames that transition with quantitative clarity and operationally focused insights. In 2025 the market is estimated at USD 2010 Million (report unit: Million USD). Under the scenarios modelled for 2026–2032, a compound annual growth rate (CAGR) of 5.8% drives the market through near-term volume and capability inflections, creating a multiyear window for decisive commercial and industrial action.
Mechanical and Electronic Fuzes Market
Why this study matters to executives in 2026
- Timing: 2026 is the inflection year when procurement backlogs, component bottlenecks and emergent regional production capacity converge. Decisions taken this year on sourcing, capacity expansion and industrial partnerships will lock in cost and availability profiles for the next 5–8 years.
- Risk-management: Recent policy moves and supply constraints have created asymmetric risks across the fuze value chain — from rare earths and magnet supply to microelectronic lead times — making proactive mitigation essential to sustain readiness and program schedules.
- Opportunity: Technology maturation in proximity sensing, safety-and-arming (S&A) devices and electronic miniaturisation opens new product and retrofit agendas. Firms that combine supply assurance with targeted R&D stand to capture premium positions as customers demand smarter, safer munitions.
Market dynamics at a glance (strategic frame, not raw segmentation)
- Steady growth, uneven distribution: While the headline market expands at mid-single-digit CAGR, growth pockets driven by modernization programs, munition recapitalization and new ammunition types create differentiated demand by product families and functions. The overall trajectory offers scale for incumbents and an opening for well-capitalised entrants.
- Fragmented competitive structure: Concentration metrics show a market that is not highly concentrated — market leadership exists, but no single player dominates. This fragmentation amplifies opportunities for consolidation, strategic alliances and capability-focused M&A.
- Procurement and qualification friction: Long qualification and integration cycles for new fuzes continue to delay the practical delivery of capability, even when design and production ramp-up occur. Program managers must reconcile acquisition cycles with industrial lead-times and certification windows.
Supply chain and regulatory headwinds shaping 2026 choices
- Critical materials and export controls: Export restrictions on key rare earths and magnetic materials implemented by major producers, together with a proliferation of import/export constraints on critical minerals, have materially increased sourcing risk. Buyers and suppliers must account for traceability and alternative materials in contract and design decisions.
- Semiconductor scarcity: Extended lead times for semiconductor components (industry data indicating multi-month waits) are influencing production cadence, particularly for electronic fuze microcontrollers and sensor arrays. Program-level buffers and supplier co-investment are now pragmatic necessities.
- Trade policy volatility: Rising trade frictions have pushed some customers to front-load orders and re-evaluate supplier footprints. This behavioral change affects pricing dynamics, inventory strategies and the feasibility of single-source models.
- Qualification complexity: NATO and allied qualification regimes—complex and sometimes protracted—mean that technical readiness does not guarantee field deployment. Early engagement with certification authorities and modular testing strategies reduce calendar risk.
Competitive landscape — what incumbents and challengers are doing
The market roster includes specialised micromechanics houses, systems integrators and major defense primes. Established European and North American manufacturers remain core suppliers for high-reliability applications, while regional producers and new-capacity entrants are expanding to capture localized demand.
Mechanical and Electronic Fuzes Market
- Strategic partnerships and local production: Recent examples include a Central/Eastern Europe production joint venture established to produce electronic fuzes for large-calibre ammunition, paired with long-term alliance contracts. Such moves signal a pragmatic shift: close-to-customer production to shorten logistics, comply with local-content expectations and secure program awards.
- Industrialisation and indigenisation: National defence industrialisation programs are accelerating local assembly and mid-life support capabilities. Where successful, these programs reduce foreign-dependency risk but introduce technology-transfer negotiations and IP management challenges.
- Prime-led advanced fuze development: Large systems integrators continue to invest in sensor fusion, safety-and-arming improvements and digital integration (e.g., smart arming/logistics data) to differentiate offerings for precision munitions. These technology bets increase value-capture beyond pure manufacturing.
Selected strategic moves in the marketplace (indicative)
- Joint ventures to scale capacity and secure contracts in alliance markets — an example of firms combining regional presence with established technology.
- Factory expansions and new assembly lines for electronic fuzes, sometimes formalised through multi-year manufacturing contracts with technology partners — a clear signal that long-term production lanes are being created to support large programs.
- Partnerships between speciality micromechanical firms and systems integrators to blend precision mechanical design with electronic capability, thereby reducing integration friction for customers.
What PW Consulting’s full report delivers (actionable, execution-oriented)
Our comprehensive study translates the market’s macro trajectory into practical tools decision-makers can use in 2026:
Mechanical and Electronic Fuzes Market
- Proprietary demand-forecast model with scenario toggles for geopolitical disruption, policy shifts and component lead-time stress; this model is designed for procurement planning and capex timing.
- Supplier and capability maps detailing where specific technologies and manufacturing competencies reside (including redundancy and single-point-of-failure analysis), enabling targeted sourcing and supplier development programs.
- Technology roadmaps for mechanical and electronic fuzes, aligned with integration and certification milestones to compress fielding timelines where possible.
- Commercial playbooks — procurement templates, contract language to hedge raw-material exposure, recommended inventory and contractual approaches to mitigate semiconductor and magnet lead-time risk.
- Deal flow and M&A heatmaps highlighting potential consolidation targets and partnership archetypes, paired with valuation and integration considerations tailored for strategic buyers.
- Operational checklists for program managers: qualification risk matrices, recommended test/regression plans and a phase-gated timeline to synchronise supply ramp-up with qualification milestones.
Strategic choices for 2026 — recommended actions
- Prioritise supply-path diversity now: Locking in multiple qualified suppliers across geography and process tiers reduces the probability of program-level stoppages driven by single-source failures or export constraints.
- Contract for predictability: Move from spot buys to multi-year capacity agreements with clear escalation and pass-through provisions for critical materials; couple contracts with technical collaboration to secure priority allocation.
- Invest selectively in localisation or co‑investment: Where program awards hinge on sovereign supply, co-investment in regional production — possibly via JVs — is often the lowest-risk route to winning business while protecting IP.
- Accelerate modular design and digital verification strategies: Modular S&A designs and broader use of digital twins and hardware-in-the-loop testing can materially shorten qualification cycles and reduce rework costs.
- Embed raw-material and component intelligence into sourcing decisions: Integrate raw-material traceability and alternative-material qualification into engineering and procurement workflows to respond quickly to export restrictions and tariff shocks.
What to expect if you delay
Delay in 2026 risks three outcomes: higher spot-market exposure to scarce components, missed delivery windows due to protracted qualification, and disadvantaged contract terms as suppliers prioritise partners with secured, forward-committed volume. Given the market’s fragmentation and the relatively modest concentration among top players, those who move early to build complementarities between production assurance and technology leadership can capture outsized position gains.
How PW Consulting can help
We position this study as a “decision acceleration” tool for executives and program managers. The public preview you’re reading demonstrates methodological depth and market-wide perspective; the full report contains the executable detail — supplier lists, scenario-tuned forecasts, operational playbooks and deal-ready analyses — required to convert insight into contract or capex decisions in 2026.
For teams planning procurement commitments, industrial investments or M&A activity this year, the full study reduces uncertainty by translating macro trends (growth trajectory and supply constraints) into discrete operational choices and timelines.
Next step
PW Consulting’s full Mechanical and Electronic Fuzes Market report provides the detailed segment analytics, supplier benchmarking and executable playbooks referenced here. Access the complete report to obtain the granular, source-level data and practical tools needed to implement the strategies outlined in this preview.
For detailed analysis of this topic, please visit the official page: Mechanical and Electronic Fuzes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com