

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Photographic Paper Market to reach USD 187.65 Million by 2032

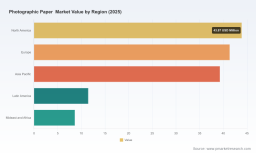
Photographic Paper Market: Strategic Preview for 2026 Decision‑Makers
As companies plan priorities for 2026, the photographic paper market presents a stable-growth, consolidation-aware opportunity set for manufacturers, distributors, and downstream print service providers. PW Consulting’s forthcoming Photographic Paper Market research (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes market dynamics, supply‑chain stress points, regulatory inflection points and competitor strategy into an actionable framework for board-level and business‑unit decisions. This preview explains the research’s strategic value without revealing the granular splits reserved for the full report.
Photographic Paper Market
Data snapshot: a market that is growing — steadily, predictably
- Historical momentum: the market expanded from USD 118.8 Million in 2020 to USD 144.55 Million in 2025, reflecting recovery and professional/personal imaging mix shifts over the pandemic recovery period.
- Near-term projection: our 2026 point forecast is USD 153.55 Million, with a forecast horizon running through 2032.
- Longer-term trajectory: the model embeds a compound annual growth rate (CAGR) of 3.85% across the forecast window (2026–2032), producing an expected market size of USD 187.65 Million by 2032.
- Market structure: concentration metrics indicate a top-three share consistent with a consolidated market (CR3 ≈ 64%), and the top five raise concentration further (CR5 ≈ 72%), signaling that scale and channel reach remain decisive competitive advantages.
Why this report matters for 2026 decisions
- Timing and precision: with 2025 as the base year and monthly/quarterly inputs through early 2026, the forecast captures recent shocks and near‑term policy changes that will affect procurement cycles and CAPEX decisions.
- Actionable supply‑chain intelligence: our cost-driver analysis isolates the key inputs that move margins — pulp, coatings, chemical emulsions, and freight — and models pass‑through scenarios under differing commodity-price regimes.
- Regulatory foresight: the study overlays evolving Extended Producer Responsibility (EPR) requirements and packaging laws on cost and product-design choices, so firms can prioritize compliance-ready investments and circularity initiatives ahead of enforcement timelines.
- Competitive playbooks: we translate competitor capabilities into tactical choices for market entry, premiumization, and channel consolidation that maximize return on capital in a modest‑growth environment.
What’s inside (practical, usable elements)
- Top-down and bottom-up forecasting: transparent modeling with scenario and sensitivity layers (base, upside, downside) so CFOs can stress-test budgets under multiple demand and input-cost trajectories.
- Cost-to-serve and margin benchmarks: granular cost models (raw materials, chemistry, coatings, packaging, logistics) and margin breakouts for premium vs. commodity lines to guide pricing and portfolio pruning.
- Supply‑chain heatmap: supplier concentration, single‑sourcing risks, and near‑term bottlenecks (including pulp and specialty-chemical availability), plus mitigations such as dual‑sourcing and strategic inventory policies.
- Regulatory & circularity playbook: compliance pathways for EPR frameworks, product eco‑design checklists, and business models for closed‑loop and take‑back programs aligned to upcoming legislative shifts.
- Commercial go‑to‑market plans: channel segmentation, dealer economics, and digital marketing prescriptions for premium photographic and fine‑art papers versus volume-oriented consumer channels.
- Deal and partnership checklist: M&A targets typology, integration scorecards, and JV structures to accelerate access to geographic footprints or specialty product lines without excessive capital intensity.
- Risk register and monitoring KPIs: eight leading indicators (commodity indices, EPR milestones, trade measures, distributor defaults) designed for board dashboards and rolling reforecast triggers.
Industry dynamics shaping 2026 strategy
- Input-cost pressure: wood pulp, a core feedstock, remains a material margin driver. The Producer Price Index for wood pulp reached 200.297 in March 2026, a level that raises the breakeven for commodity product lines and accelerates interest in alternate fiber blends and recycled content.
- Regulatory acceleration: multiple U.S. jurisdictions are advancing or enacting EPR schemes for packaging and paper products. These frameworks increase compliance overhead for producers and place a premium on materials that demonstrate lower end‑of‑life costs.
- Premiumization vs. volume: demand for archival-grade and fine-art media has held up better than entry-level consumer segments. Strategic product differentiation — coatings, archival certifications, ink compatibility — can sustain higher margins even as overall growth remains moderate.
- Consolidation opportunities: observed concentration metrics imply that scale matters for distribution and raw‑material purchasing. Mid‑sized players face margin compression unless they identify niche differentiation or partner with larger distributors.
Competitive landscape: who to watch and why
The market exhibits a mix of global incumbents and specialized independents. The full report contains company scorecards and capability matrices; below are concise strategic postures to inform immediate competitive response.
Photographic Paper Market
- Fujifilm Holdings Corporation (Tokyo, Japan — https://holdings.fujifilm.com/en): Strong in silver-halide and archival-grade papers. Their integrated film-to-paper capability and brand reputation make them a natural leader in professional and archival segments.
- Eastman Kodak Company (Rochester, NY, USA — https://www.kodak.com/en/): Focused on professional inkjet and archival media with deep distribution in North America and Western Europe. Kodak’s legacy brand supports premium pricing in professional channels.
- Canon Inc. (Ota, Tokyo, Japan — https://global.canon/en/): Dominant in inkjet media for digital imaging; Canon’s printer ecosystem offers cross-selling leverage for paper and consumables.
- Epson Corporation (Suwa, Nagano, Japan — https://corporate.epson/en/): Specializes in papers optimized for wide‑format and professional inkjet workflows; Epson’s technical alignment with printheads and inks is a competitive moat.
- FOMA BOHEMIA spol. s r.o. (Hradec Králové, Czech Republic — https://www.foma.cz/en): Niche leader in black‑and‑white silver‑ halide products for analog and archival customers; strong credibility in specialist communities.
- ADOX Fotowerke GmbH (Bad Saarow, Germany — https://www.adox.de/en/): Focus on analog photographers with in‑house chemistry and film production; plays to vintage/analog revival trends.
- Hahnemühle FineArt GmbH (Hamburg, Germany — https://www.hahnemuehle.com/en/): Premium fine‑art inkjet media with age‑resistance certifications; a top pick for galleries and museums requiring proven longevity.
- Ilford Imaging Europe GmbH (Bergisch Gladbach, Germany — https://ilford.com/): Premium inkjet and professional printing media with strong brand equity among photographers and labs.
- Mitsubishi Paper Mills Limited (Tokyo, Japan — https://www.mpm.co.jp/eng/): Established in silver‑halide papers and inkjet media; benefits from manufacturing scale and raw‑material procurement capabilities.
- Shantou Xinxie Photo Materials Co., Ltd. (Shantou, China — corporate profile): Supplier of digital photo papers and specialty materials serving regional and export markets; price competitiveness and flexible production are strengths.
- HYMN Image Materials Co., Ltd. (China — https://www.hymn-image.com/): Manufacturer of inkjet and silver‑halide papers for both professional and consumer segments; able to serve high-volume regional demand.
Strategic implications and recommended actions for 2026
- Prioritize procurement resilience: given elevated pulp PPI and transport volatility, adopt a dual‑sourcing strategy, renegotiate indexation clauses, and stress-test supplier SLAs. Maintain a strategic safety stock for critical coatings and emulsions to avoid production downtime.
- Pursue premium adjacency: if your margins are under pressure, accelerate development of archival/fine‑art lines and certified longevity claims that justify price premiums and reduce sensitivity to commodity swings.
- Embed EPR readiness into product development: anticipate packaging and end‑of‑life compliance by 2026–2028. Invest in recyclable or reusable packaging, and pilot take‑back schemes with key retailer partners to reduce future compliance costs.
- Optimize portfolio via SKU rationalization: use our cost‑to‑serve dashboards to retire low-margin, low‑volume SKUs and redeploy working capital into high-margin specialty papers or service offerings (e.g., finishing, printing-as-a-service).
- Consider bolt‑on acquisitions or strategic alliances: for mid‑sized producers, M&A can secure specialty process know‑how or geographic distribution. For larger players, partnerships with fine‑art brands can accelerate premium entry without full integration risk.
- Invest selectively in digital channels and lab automation: target pro‑photographer and institutional buyers with subscription models and value‑added finishing services to create recurring revenue and improve lifetime customer value.
- Measure and report sustainability outcomes: transparent life‑cycle metrics and certified recycled content will be commercial differentiators under expanding EPR regimes and among institutional buyers like museums and universities.
How PW Consulting helps
Our full Photographic Paper Market report delivers the detailed region/application splits, supplier maps, pricing ladders, and competitor scorecards that corporate development, procurement, and strategy teams need to make defensible 2026 investment decisions. This preview intentionally withholds granular segment shares to protect the analytic value that subscribers expect; the full study provides downloadable models and an implementation roadmap tailored to executive needs.
Photographic Paper Market
If your 2026 plan requires defensible scenarios for CAPEX, M&A, or product repositioning — or a compliance-ready pathway for EPR — the complete PW Consulting study converts market signals into executable steps with quantified ROI and risk buffers. Contact PW Consulting to obtain the full report, underlying datasets, and a tailored executive briefing that aligns the market forecast to your balance‑sheet priorities.
For detailed analysis of this topic, please visit the official page: Photographic Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com