

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: PV Glass Market to Hit USD 51.65B by 2032 at 18.46% CAGR

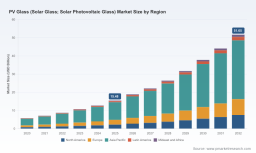
PV Glass (Solar Photovoltaic Glass) Market — 2026 Strategic Preview
As governments accelerate clean-energy targets and module manufacturers chase incremental efficiency gains, photovoltaic (PV) glass has moved from a commoditized input to a strategic raw material. This preview summarizes the strategic value of PW Consulting’s full PV Glass Market study for corporate decision-making in 2026. It highlights the market’s macro trajectory, competitive dynamics, policy inflection points and the practical, playbook-style intelligence that executives will need to convert market growth into durable advantage — while deliberately withholding the granular segmentation tables and plant-level financials that are contained in the full report.
PV Glass (Solar Glass; Solar Photovoltaic Glass) Market
Macro trajectory you must plan around
The PV glass market is on a steep growth path. Our base-year framework (historical 2020–2025; base year 2025) shows the industry accelerating from a multi‑billion dollar market in 2020 to a materially larger market by 2025, and our forecast (2026–2032) projects continued robust expansion. PW Consulting’s forecast shows sustained high‑teens growth over the medium term (the modeled forecast CAGR is 18.46% for the forecast period), producing transformative scale by the end of the decade. That growth is driven by a mix of utility‑scale installations, new module types that demand higher-performance glass, and a renewed policy focus on domestic clean‑tech manufacturing in several large markets.
PV Glass (Solar Glass; Solar Photovoltaic Glass) Market
Why this research matters for 2026 corporate decisions
- Capital allocation: With the market growing rapidly, choices about greenfield versus brownfield capacity, modular line investments (tempering, AR-coating, TCO capability) and timing have multi-year payback profiles. Our study maps where and when incremental capacity is likely to be absorbed under multiple demand scenarios.
- Procurement and price risk: Volatility in key feedstocks and periodic trade interventions can swing landed costs. The report gives a transparent price‑build model and hedging playbook so procurement leads can lock economically sensible multi‑year agreements without overpaying for optionality.
- Supply security for module manufacturers: Module OEMs face a new reality — glass availability and specification choice materially affect cell efficiency and BOS costs. The study supplies supplier scorecards and recommended contracting terms architects and buyers can operationalize in 2026.
- M&A and partnership targets: We identify the profile of acquisition targets and JV structures that generate rapid scale and market access, and include an M&A screening tool that ranks opportunities by strategic fit and integration complexity.
- Regulatory and trade strategy: With tariffs, anti‑dumping remedies and industrial incentives changing rapidly, the research provides a decision checklist for trade counsel and government affairs teams to prioritize lobbying, localization and tariff-mitigation strategies.
What’s in the full report (practical, operational content)
- Top‑line and bottom‑line market forecasts (2026–2032) with scenario variants and sensitivity analysis linked to module demand, glass pricing and feedstock cost curves.
- A supply‑demand model at line and plant level (availability, ramp schedules, utilization thresholds and likely export flows) — presented with visual dashboards and downloadable Excel modules.
- Price‑build and input‑cost model (including soda ash and silica trends), and supplier‑negotiation templates for fixed, index‑linked and hybrid contracting.
- Supplier scorecards and capability matrices (capacity, technology stack: float/tempered/AR/TCO, quality, vertical integration) with an acquisition/partner suitability index.
- Regulatory tracker and policy impact assessment covering tariffs, trade remedies and industrial incentive programs across key markets.
- Capex timelines, typical greenfield and brownfield economics, and a playbook for rapid line commissioning with risk checklists for permitting, utilities and feedstock logistics.
- Three forward scenarios (base, upside, downside), an executive risk matrix, and an actionable 90‑day strategic checklist for executive teams.
Market dynamics and near‑term catalysts
Several forces are converging in 2026 to re‑shape supplier economics and customer strategies:
PV Glass (Solar Glass; Solar Photovoltaic Glass) Market
- Policy-driven localisation: Industrial policies in major economic blocs are nudging procurement and capex towards domestic or preferential suppliers. This is creating near-term demand pockets for locally produced PV glass and encouraging module OEMs to rethink sourcing footprints.
- Trade interventions and tariff timing: Several trade remedies and tariff regimes remain active or are scheduled for review in 2026. These create windows of procurement risk and opportunity for firms that calibrate contracts and inventory proactively.
- Feedstock cost volatility: Soda ash and other raw-material price swings have periodically reset margins. During 2025 soda ash experienced downward pressure from oversupply; procurement teams should bake in scenario buffers, but also seek to capture cost advantages where they appear.
- Technology segmentation: Different glass technologies (ultra‑clear float, AR‑coated, TCO coatings, tempered/textured surfaces) are not interchangeable from a module performance standpoint. Upstream producers that can cost‑effectively deliver specific glass specs will command premium access to high‑value module programs.
- Consolidation and market concentration: The industry exhibits a moderate level of concentration at the top. The three largest players control a significant share of global capacity, and the top five command a clear majority — a structure that influences price discovery, contractual norms and the speed of technology diffusion.
Competitive landscape — strategic implications from the leader set
Understanding incumbent strategies is essential to anticipate capacity moves, pricing behavior and technology adoption. Key dynamics we highlight:
- Xinyi Solar Holdings : A dominant global player with a material share of the market and strong scale in low‑iron tempered glass. Its investments in Southeast Asia capacity expansion are intended to combine cost competitiveness with proximity to major module assembly hubs. For competitors and buyers, Xinyi’s moves mean capacity discipline and aggressive fulfilment timelines—module OEMs should evaluate long‑term supply contracts and contingency plans.
- Flat Glass Group : A large producer prioritizing ultra‑clear float and AR‑coated glass. Its technology focus positions it well to serve high‑efficiency c‑Si module programs. For investors, Flat’s strategy underlines the premium for AR capability in higher‑value segments.
- NSG Group (Nippon Sheet Glass) : With expertise in TCO‑coated products suited to thin‑film technologies, recent commissioning of a TCO line in the United States is a tactical response to thin‑film OEM demand and localization trends. Module manufacturers contemplating thin‑film adoption or expansion should view NSG as a potential strategic partner.
- AGC Inc. : AGC competes on ultra‑clear float and AR coatings designed for high‑efficiency modules. Its product set is attractive to OEMs pursuing incremental efficiency and lower LCOE through optical gains.
- Borosil Renewables : A leading domestic player in India that recently received board approval to expand capacity. The company’s domestic position and agility give it an advantage in a market where trade remedies and import measures materially affect sourcing economics.
- Guardian Industries : With product lines marketed for utility and concentrator applications, Guardian is an important supplier to North American utility‑scale projects and specialized module formats.
Collectively, these firms demonstrate three strategic playbooks that matter for 2026: (1) scale + cost leadership, (2) technology differentiation (AR/TCO/textures), and (3) geographic/localization plays aligned with trade policy. Your response should be calibrated to which playbook your company can credibly aspire to.
Scenario planning & risk matrix (executive highlights)
- Base case: Continued strong demand growth consistent with high‑teens CAGR in the forecast window; orderly capacity additions and moderate feedstock price movements. Contracts and procurement strategies that lock multi‑year volumes at indexed prices perform well.
- Upside: Faster module adoption and higher‑than-expected deployment cause a temporary tightness in supply for premium glass specs. This scenario favors firms with agile capacity expansions, fast commissioning, or exclusive off‑take agreements with module OEMs.
- Downside: Prolonged trade restrictions, delayed tariffs expirations or sharp raw‑material inflation compress margins and re‑orient flows towards protected/domestic suppliers. Here, companies with diversified supplier bases and in‑region production win.
90‑day playbook for 2026 executive teams
- Quantify exposure: Map your volume exposure to top suppliers and to products that have differentiated specs (AR, TCO, textured). Run the supplied sensitivity templates for price and lead‑time shocks.
- Secure optionality: Negotiate layered contracts (short‑term float + long‑term tranche) and include force‑majeure and tariff‑pass‑through clauses where appropriate.
- Capex prioritization: Re‑test any planned greenfield investments against our utilization thresholds and ramp‑risk checklist; consider brownfield acquisitions to accelerate time‑to‑market.
- Regulatory engagement: Align government affairs and procurement around the policy windows available in 2026 — especially where local content rules or incentives materially change landed cost economics.
- Competitor watch: Track announced and rumored capacity moves from leading players and module OEM programs that require premium glass; prioritize intelligence that impacts your 18‑month supply visibility.
Conclusion — the decision moment for 2026
For executives planning capital, procurement and market expansion in 2026, PV glass is no longer a background commodity risk — it is a strategic lever. PW Consulting’s full market study combines forecast rigor (2026–2032 outlook and an 18.46% forecast CAGR), supplier intelligence, regulatory tracking and executable playbooks to convert market trends into discrete decisions. The public preview above demonstrates the type of thinking we apply; the full report contains the detailed segmentation, plant‑level timelines, supplier scorecards, price models and Excel tools you will need to operationalize a winning 2026 strategy.
To access the complete dataset, model files and our confidential supplier scorecards that underpin the recommendations in this preview, visit the PW Consulting report page or contact our industry team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: PV Glass (Solar Glass; Solar Photovoltaic Glass) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com