

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Quartz Stone Market Poised for 11.6% CAGR in 2026–2032

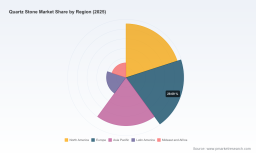
Quartz Stone Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Chief Industry Analyst, I present an executive preview of our latest Quartz Stone Market study. This note is deliberately structured as a strategic “trailer”: it demonstrates the analytical depth and practical orientation of our research while withholding the granular segment tables and proprietary breakdowns that are included in the full report. Use this briefing to assess the study’s relevance for 2026 planning — and to decide which parts of the full intelligence you will need to unlock competitive advantage.
Quartz Stone Market
Market snapshot: scale, trajectory, and what it means
Using 2025 as the base year, our market-level view frames quartz stone as a growth industry undergoing structural expansion. The global market more than doubled over the 2020–2025 historical window and continues to scale in our forecast horizon. At an 11.6% compound annual growth rate (CAGR) through 2032, the sector is projected to reach a materially larger global valuation by the end of the forecast period. These headline numbers tell a simple story: demand drivers remain strong and investor attention will intensify.
Quartz Stone Market
For corporate strategists, three macro takeaways follow immediately:
Quartz Stone Market
- Scale creates strategic options: rising market size enables new investment theses for vertically integrated manufacturers, contract fabricators, and branded premium players.
- Growth is not uniform: while headline CAGR is compelling, the growth pattern and margin dynamics differ significantly by route-to-market, product format, and regulatory exposure — the granular view in our report is essential to translate headline growth into profitable choices.
- Time matters: 2026 is a pivotal year for strategic positioning because short-to-medium-term regulatory and trade events will materially alter sourcing economics and go-to-market calculus.
Key demand-side dynamics
Three demand vectors are driving volume and mix shifts:
- Residential renovation and premium new-build demand continue to push consumption of quartz surfaces that emphasize durability and design consistency.
- Commercial and architectural adoption is accelerating where engineered surfaces provide large-format, low-maintenance alternatives to natural stone.
- Spec and certification-sensitive segments (healthcare, hospitality, education) are increasingly selecting products certified to strict low-crystalline-silica and indoor-emissions standards — a feature that changes specification pathways and adds a non-price dimension to competition.
For executives, the lesson is straightforward: product positioning that bundles design, performance, and compliance credentials will capture both premium pricing and lower procurement friction in regulated end-markets.
Supply-side realities and raw-material considerations
Supply-chain dynamics for quartz surfaces are shaped by raw-material sourcing, processing footprint, and capacity utilization across a global value chain. The sector’s upstream is anchored by high-purity quartz production in established pegmatite districts and by the industrial processing steps that create engineered formulations and slabs.
Our research maps current sourcing nodes, processing bottlenecks, and near-term capacity expansions. These maps identify where single-source risk is concentrated and where investment in alternate feedstock or local processing unlocks resilience. Practical applications include prioritized supplier-development programs for fabricators and capital allocation templates for manufacturers considering greenfield or brownfield expansions.
Trade, regulation, and compliance — the 2026 inflection
Recent trade and policy activity has elevated regulatory risk into a core strategic variable. Notable developments include public hearings and policy considerations by U.S. authorities on imports of quartz surface products and an ongoing trade-policy overlay that includes existing tariffs applied to certain origins. Separately, certification regimes (e.g., Greenguard Gold, NSF) and tightening definitions of permissible crystalline silica exposure in residential and public projects are changing procurement specifications.
Implications for 2026 decisions:
- Procurement teams must re-price supplier relationships to incorporate potential safeguard measures and import duty volatility.
- Manufacturers should fast-track product lines that can be certified to stricter health standards if they intend to serve sensitive end-markets.
- Investors and M&A teams need trade-policy scenario overlays embedded in valuation models; an otherwise accretive acquisition can flip if a safeguard remedy reshapes cross-border economics.
Competitive landscape — what the leaders are doing
The quartz surface market remains fragmented relative to many industrial commodities: top-three and top-five concentration metrics indicate substantial room for local champions and nimble innovators. Leading firms exhibit a mix of strategies that illustrate how to compete at scale:
- Cambria (United States) — a family-owned, U.S.-based player that competes on an American-made value proposition, premium design, and brand storytelling. Their emphasis on domestic manufacturing reduces exposure to import tariffs and appeals to projects prioritizing local content.
- Spectrum Quartz (United States) — an engineered-quartz specialist that leverages intellectual property (patents) and proprietary processes to replicate natural veining and premium finishes. Product differentiation through technology is central to protecting margins in commoditizing markets.
- Cosentino (Spain) — a diversified surfaces group with a portfolio that includes mineral-based Silestone and ultra-compact Dekton surfaces. Their multinational footprint and broad application set reflect a strategy of product and channel diversification to capture both architectural and residential demand.
- Dal-Tile (United States) — a tile and surfaces leader that markets quartz under branded lines focused on natural aesthetics and low maintenance. Their integrated distribution network and channel relationships (trade, retail) are defensive advantages in a competitive landscape.
Each of these firms offers a playbook component that incumbents and entrants can adapt: vertical integration to control cost and speed-to-market; proprietary design and IP to defend pricing; certifications and localized production to neutralize trade friction.
Recent events to watch (immediate strategic implications)
- Public hearings and deliberations by U.S. trade authorities on quartz surface imports — these proceedings can lead to safeguard or remedial measures that change the cross-border cost basis for many supply chains.
- Industry product launches and technology rollouts — new engineered collections emphasize realism and design fidelity, challenging natural-stone premium positioning and changing specification conversations.
- Regulatory and standards updates — evolving certification requirements for low-crystalline-silica products will affect acceptability in sensitive end-markets and public procurement.
What the PW Consulting Quartz Stone Market report delivers
Our full study is designed for immediate operationalization by commercial and corporate strategy teams. Highlights include:
- Demand-model workbook (2020–2032) with scenario toggles for trade-policy shocks and adoption curves — ready to integrate into capital planning and sales forecasting systems.
- Supply-chain heat map and supplier-risk matrix that prioritize mitigation actions by probability and impact.
- Pricing and margin model calibrated to raw-material inputs, transport and tariff scenarios, and channel mix assumptions.
- Regulatory-impact playbook outlining certification pathways, compliance timelines, and procurement-spec migration strategies for regulated end-markets.
- Competitor benchmarking and go-to-market blueprints, including a shortlist of strategic partners and acquisition targets (ranked by strategic fit and integration complexity).
- M&A and partnership decision framework tailored for 2026 conditions, with integration checklists and post-close value-capture templates.
To preserve the research value for subscribers, the report intentionally withholds proprietary segment tables and specific region/application revenue splits in this preview. These granular outputs are included in the full deliverable and are presented with both static tables and interactive models to support board-level decision-making.
Strategic recommendations for 2026 — prioritized actions
For leadership teams contemplating choices this year, we recommend a three-tiered agenda:
- Near-term (0–6 months) : Run a rapid tariff and certification stress-test against your top suppliers and largest contracts. Recalibrate procurement terms and hold contingency inventory for critically exposed SKUs.
- Medium-term (6–18 months) : Accelerate product certification pathways for low-crystalline-silica and indoor-emissions standards if you serve healthcare, education, or public projects. Where practical, pilot near-shore or domestic fabrication capacity to de-risk import exposure.
- Strategic (18–36 months) : Evaluate targeted M&A or JV opportunities to secure access to proprietary engineered technologies or to consolidate regional fabrication footprints. Prioritize targets that close gaps in certification, distribution, or IP.
Each of these steps maps directly to templates and models inside our report — from tariff-adjusted margin calculators to acquisition valuation scenarios under multiple trade-policy outcomes.
Why this research is mission-critical for 2026 planning
2026 presents a confluence of accelerating demand, regulatory refinement, and trade policy uncertainty. Organizations that act from insight — not intuition — will preserve pricing power, avoid costly supply disruptions, and convert regulatory compliance into a competitive asset. Our Quartz Stone Market study is structured to inform those actions with data, scenarios, and executable playbooks.
If your 2026 plan includes capital allocation, channel expansion, or M&A in surfaces and stone, this study is a necessary input to de-risk execution and sharpen ROI expectations.
Next step
This preview demonstrates the breadth and practical orientation of PW Consulting’s market research. The full report (base year 2025; historical 2020–2025; forecast 2026–2032) contains the proprietary segmentation tables, interactive models, and supplier shortlists referenced above. For access to the complete intelligence and to schedule a briefing with our advisory team, please visit the PW Consulting Quartz Stone Market page or contact your engagement director.
Strategic decisions in 2026 will determine who captures the next wave of value in the quartz surface industry. Use the right data and scenario tools to ensure your organization is one of them.
For detailed analysis of this topic, please visit the official page: Quartz Stone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com