

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Chemical & Materials
PW Consulting: Carbon-Carbon Composites to hit USD 334.67M by 2032 (6.55% CAGR)
By pmarketresearch, 2026-07-30
Carbon-Carbon Composites 2026 Strategic Preview: Why This Market Report Matters to Executive Decision-Making
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused preview of our new Carbon-Carbon Composite Material Market study — a practical, decision-oriented resource tailored for boardrooms, corporate development teams, and industrial strategists preparing for 2026. This preview synthesizes the macro trajectory, structural dynamics, and competitive moves that should shape any capital, sourcing or commercial decision in the coming 18–36 months. Detailed, segment-level intelligence is intentionally reserved for the full report; the purpose here is to show analytical depth while preserving the tactical granularity that drives commercial advantage.
Carbon-Carbon Composite Material Market
Market trajectory — a compact, actionable view
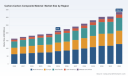
The carbon-carbon composite market has moved from niche specialty material into a scaling commercial sector with clear demand drivers and rising strategic importance. Our baseline sizing shows the market increasing from approximately USD 163.2 million in 2020 to USD 215.0 million by the 2025 base year — reflecting both steady end-market adoption and price dynamics. Looking forward, the market is forecast to grow at a compound annual growth rate (CAGR) of 6.55% through our 2026–2032 forecast window, reaching roughly USD 334.7 million by 2032.
Carbon-Carbon Composite Material Market
Two practical takeaways for 2026 planning: first, the growth profile is sufficiently robust to justify targeted capacity investments and R&D commitments for those seeking to capture premium end-markets (aerospace thermal protection, high-temperature industrial components, and advanced braking systems). Second, growth is uneven by capability and application; value will accrue to firms that combine material science leadership with qualified supply relationships into aerospace and defense OEMs.
Carbon-Carbon Composite Material Market
Structural dynamics that will determine winners and losers
- Supplier concentration and precursor risk: The upstream supply of carbon fiber precursors is highly concentrated. This creates a pinch-point for carbon-carbon producers and elevates the value of secured, diversified precursor arrangements — especially during periods of demand acceleration or policy-driven trade shifts.
- Production economics: Global production tonnage and pricing trends matter as much as revenue growth. In 2024, global production reached the tens of thousands of tonnes, with an average selling price in the low thousands of USD per tonne; nuances of capacity utilization and product mix will drive margin differentials more than headline revenue in 2026.
- Policy and tariff sensitivity: Recent tariff framework changes and evolving trade policy have already increased export costs and highlighted the need for redundant manufacturing footprints close to key end-markets. Firms with global footprint flexibility and near-market production will gain a competitive edge in contract awards.
- Environmental and feedstock regulation: Environmental restrictions impacting PAN-based precursor production are not peripheral — they affect upstream costs, capital intensity, and permit timing. Leaders will be those who incorporate precursor security and regulatory scenario planning into capital allocation decisions.
- Market concentration at producer level: The industry displays a high degree of seller concentration — the top suppliers capture the majority of the market — which favors incumbents on long-term contracts but opens windows for regional challengers who can guarantee supply continuity or superior cost.
Why this report is operationally valuable for 2026 decisions
Board-level questions in 2026 will be less about “is this market growing?” and more about “how do we allocate scarce capital and managerial attention to maximize rate-of-return while de-risking supply?” Our report is structured to answer those questions with tools and templates you can operationalize immediately:
- Actionable market sizing and three-tier scenario modeling (conservative, base, upside) calibrated to tariff, precursor availability, and aerospace demand shocks.
- Manufacturing cost curves and margin sensitivity analyses (unit economics by process route), enabling rapid ROI checks on capacity projects and retrofits.
- Supply-chain resilience playbook: supplier scorecards, dual-sourcing templates, and contracting strategies to lock precursor supply without overpaying for optionality.
- Commercial playbooks for OEM partnerships — with negotiation levers and risk allocation language for long-term off-take agreements.
- M&A screening and integration checklist targeted at bolt-on targets, vertical-integration candidates (precurors, densification specialists), and regional capacity entrants.
- Regulatory and ESG impact matrix addressing PAN precursor regulation, tariff scenarios and permitting timelines for new facilities.
- Proprietary company dossiers, supplier maps and a competitive heat map to prioritize commercial outreach and partnership testing.
Competitive landscape — what incumbents are doing and why it matters
The current competitive set includes global materials champions, specialty carbon firms, and a growing cohort of regional producers. Several recent industry moves crystallize the strategic playbook:
- Capacity expansion aligns with aerospace and advanced mobility demand: Major producers and OEM partners have announced or initiated capacity increases aimed at the high-margin aerospace and premium automotive segments. These moves indicate companies are betting on sustained demand for thermal protection and braking systems that favor carbon-carbon composites.
- Strategic vertical plays and product launches: Firms are both extending upstream (precursor and precursor technology) and enhancing product portfolios (next-gen prepregs, densified C/C). Sustainability- and performance-branded launches signal that differentiation will increasingly rest on proprietary processing and lifecycle advantages.
- Portfolio reshaping through asset transactions: Divestments and acquisitions in the space suggest players are optimizing for focus on core technologies — enabling faster commercialization cycles for niche thermal protection systems while creating acquisition targets for scaling manufacturers.
For executive teams, the competitive implications are clear: scale matters for meeting OEM qualification timelines, but specialty IP and supply security are equally critical. A binary strategy — either scale at all costs or remain a niche player — is risky. The optimal position for 2026 is hybrid: selective capacity growth combined with strategic partnerships or minority stakes in precursor and processing technology providers.
Emerging strategic options to consider for 2026
- Near-market capacity investments: Prioritize small- to mid-scale production nodes in geographies exposed to tariff volatility to shorten lead times and reduce logistics risk.
- Precursor hedging and JV models: Move beyond spot contracts. Consider joint ventures or long-term offtakes with leading precursor producers to secure volumes and stabilize input costs.
- Product differentiation via densification and surface engineering: Invest in processing capabilities that improve durability under extreme thermal cycling — a value driver for aerospace thermal protection and braking systems.
- Selective M&A and strategic minority stakes: Use capital to access IP and supplier continuity (e.g., densification specialists, precursor recyclers) rather than pursuing broad horizontal consolidation.
- Regulatory and ESG roadmap: Build an upstream emissions and feedstock compliance plan; this reduces permitting risk and can be a commercial differentiator for OEM partners focused on ESG.
Case in point: signals from recent industry developments
- Large-scale capacity expansions at leading chemical and composites firms underscore a near-term supply response to aerospace and space program demand.
- OEM-led facility investments and contract shifts reflect a desire to secure qualified domestic supply chains for critical thermal protection and braking systems.
- Product launches with sustainability branding indicate that customers are beginning to value lifecycle attributes — a trend that will shape procurement specifications over the next three years.
What the full PW Consulting report delivers (reserved tactical detail)
The full report translates the strategic implications above into executable initiatives. It contains segment-level market shares, regional demand curves, application-specific adoption timelines, supplier pricing matrices, and a prioritized deal pipeline for M&A and JV targets. We also include a ready-to-use board briefing deck and an executive decision matrix that maps capital allocation choices to expected IRR ranges under alternative policy and demand scenarios.
For executives evaluating capex, M&A, or supply-chain diversification in 2026, this is not an academic exercise — it is the operational intelligence that reduces execution risk and concentrates investment where the highest, fastest returns are available. To preserve competitive advantage, we reserve the full, segment-level data and model access for report subscribers.
Next steps for corporate leaders
- Begin or update a two-way stress test of your supply chain under tariff and precursor-constrained scenarios. Use the results to define minimum viable local capacity needs.
- Identify one or two precursor counterparties for deeper commercial engagement (JV or long-term offtake) and perform fast-track diligence using the supplier scorecards in our toolkit.
- Prioritize investment in processing capabilities that convert carbon-carbon advantages (thermal, high-temp structural) into certified products for aerospace and premium automotive OEMs.
- Request the full PW Consulting report to access the segment-level modeling, company dossiers, and the transactional playbook required to operationalize these steps.
In 2026, decisions about where to invest, whom to partner with, and how to manage precursor risk will determine which companies capture disproportionate value as the carbon-carbon market scales. PW Consulting’s report transforms those strategic choices from high-level debate into executable programs — but the granular data that unlocks specific commercial moves is reserved for the full study. Contact PW Consulting to obtain access and convert this strategic preview into a robust 2026 action plan.
For detailed analysis of this topic, please visit the official page: Carbon-Carbon Composite Material Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Precision Glass Molding Market to Reach USD 30,423M by 2032 at 7.2% CAGR
By pmarketresearch, 2026-07-30
Precision Glass Molding Market: Strategic Primer for 2026 Decision-Makers
By PW Consulting — Senior Strategic Advisor & Chief Industry Analyst
Precision Glass Molding Market
Executive overview
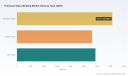
Precision glass molding (PGM) is shifting from a niche manufacturing technique to a strategic manufacturing platform for optics across consumer electronics, automotive, industrial sensing, and infrared imaging. Our latest market model — calibrated to a 2025 base year and covering 2026–2032 — quantifies a clear expansion trajectory: the PGM market is estimated at roughly USD 18.7 billion in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 7.2% through the forecast window, reaching the low‑to‑mid tens of billions by 2032. This steady expansion reflects converging demand drivers: optical performance requirements that exceed injection-molded plastics, accelerating volume production for compact multi-lens modules, and new materials and tooling innovations that materially compress unit cost curves.
Precision Glass Molding Market
Why this matters for 2026 strategy
-
Investment timing: The 7.2% CAGR creates a runway for measured capacity expansion. Companies that commit selectively in 2026 — either through CAPEX for molding machines or targeted partnerships with experienced PGM suppliers — can secure yield and time-to-market advantages as OEMs demand higher optical fidelity.
Precision Glass Molding Market -
Material and supply‑chain risk: Rising raw-material cost pressure remains the single largest adoption barrier, particularly where glass costs and specialized preforms dominate unit economics. Concurrently, geopolitical controls (notably export restrictions on materials such as germanium) are catalyzing alternative material pathways, including broader industrial adoption of chalcogenide glasses for infrared optics. These dual forces require procurement and product teams to simulate alternative supply scenarios now.
-
Competitive positioning: The market exhibits meaningful concentration — the top-tier PGM suppliers control a substantial share of volume production — creating both barriers and opportunities. New entrants must either differentiate on proprietary tooling and process intelligence or pursue vertical integration to compress per-unit cost.
What PW Consulting’s report delivers (practical, transaction‑ready content)
This study was designed as an operational playbook for executives, product leads, and corporate development teams. It blends quantitative market sizing and forward-looking scenarios with actionable diagnostics. Key inclusions:
-
Proprietary market model (2020–2032) with base-year validation: granular topline and scenario runs that allow sensitivity testing of raw-material inflation, mold-capacity lead times, and alternate material adoption curves.
-
Supply‑chain maps and make-vs‑buy decision trees: componentized cost stacks for typical PGM assemblies, bottleneck analysis (tooling, preform supply, AR coatings), and recommended hedging tactics for 12–36 month planning horizons.
-
Commercial playbook: go-to-market options for OEMs, tier‑1 suppliers, and foundries — including sample partnership structures, pricing anchors, and ramp calendars for contract negotiations.
-
Technology & CAPEX primer: comparison of molding equipment classes, expected throughput and yield metrics, and a capital ROI template calibrated to varying production scales.
-
M&A and JV screening: a short‑list of target archetypes, valuation heuristics, and integration checklists tailored for strategic acquirers looking to buy optical capacity or proprietary tooling expertise.
-
Regulatory and material risk matrix: scenario-played impacts of export controls, environmental compliance in key geographies, and transition plans for alternative optical glasses.
Competitive landscape: capabilities that matter
Understanding supplier strengths — not just capacity — is essential. Our competitive diagnostic focuses on three axes: production scale & repeatability, material expertise, and vertical integration of tooling and coatings. Highlights from primary company analysis:
-
Rochester Precision Optics (RPO): Recognized for high-volume asphere production and end-to-end vertical integration (tooling, preforms, centering, AR coatings). Recent strategic financing in early 2025 materially strengthens their capacity and R&D capability — a clear signal that competition for volume contracts will intensify.
-
INGENERIC GmbH: A European center of expertise for micro-optics and complex micro‑lens arrays. Their demonstrated ability to move from prototype to scalable runs is a differentiator for multispectral and multifunctional optics applications.
-
LightPath Technologies: Specialized in chalcogenide glass molding for IR optics and thermal imaging, they exemplify the material‑driven niche players who can capture market share as germanium supply uncertainty persists. Their material qualification focus is strategically synchronous with macro supply risk.
-
Toshiba Machine / Shibaura Machine: These OEMs for glass-molding equipment determine the rhythm of capacity expansion. Machine makers set achievable throughput, tool life, and automation levels — all of which cascade into customer unit economics.
-
Syntec Optics: A smaller, design-to-assembly player that illustrates the integrated service model (design + molding + assembly) some OEMs favor to reduce coordination risk and accelerate module validation.
Technology inflection points and what they mean for your roadmap
Two near-term technology developments will shape supplier economics and product roadmaps in 2026:
-
Advances in mold materials and tooling: Recent academic and industrial work on wafer-scale vitreous carbon molds indicates potential for lower-cost scalable replication of aspheres at wafer throughput — a structural improvement that could meaningfully lower per-unit tooling amortization for certain lens families.
-
Material substitution dynamics: Export-control-driven constraints on traditional IR substrate supply are accelerating qualification of alternative glasses such as chalcogenides. Firms that have early material-qualification pipelines and testbeds reduce product calendar risk and can capture displaced demand.
Practical recommendations for 2026 planning cycles
-
Adopt a two-track sourcing strategy: a core long-term supplier relationship for volume certainty and a secondary agile supply line for material or tooling experimentation. Use 2026 to negotiate multi-year capacity windows tied to volume milestones rather than spot buys.
-
Prioritize tooling IP and process know‑how: If your product roadmap depends on low‑tolerance aspheres or complex freeform elements, consider investment in in‑house mold maintenance capabilities or exclusive tooling arrangements to protect lead times.
-
Scenario‑test material supply shocks: Run a structured stress test of your BOM against a range of raw-material price moves and export-control events. Build a phased material‑substitution matrix with qualification gates aligned to product refresh cycles.
-
Evaluate strategic partnerships with machine OEMs: For companies considering onshore capacity, partnering with machine builders can accelerate automation and shorten industrialization timelines versus a pure greenfield factory build.
-
Embed regulatory monitoring in product development: Regulatory shifts can alter the economics of IR optics overnight. Make policy intelligence a standing input for quarterly product reviews.
Where granular intelligence is intentionally held back — and why
Consistent with our “trailer” principle, this primer surfaces the strategic contours and executable guidance procurement, product, and M&A teams need to start planning now. We have intentionally omitted granular region-by-region or application-specific share tables and detailed segment revenue lines from this public summary. Those data points are included in the full PW Consulting Precision Glass Molding Market report, which contains the actionable segmentation and supplier benchmarking matrix required for tendering, M&A underwriting, and operations planning.
Next steps for executives
-
Request a tailored briefing: Schedule a 45–60 minute workshop with our PGM practice to align market scenarios to your product roadmaps and procurement calendars.
-
Pursue a rapid diagnostic: Commission a 6–8 week diagnostic that maps your product portfolio to PGM readiness, including a cost-to-serve estimate, tooling requirements, and a prioritized supplier shortlist.
-
Consider pre-emptive strategic moves: For OEMs facing short windows to market, early binding commitments with leading PGM partners or targeted minority investments can secure capacity and accelerate time-to-volume.
Precision glass molding is now a strategic lever, not just a manufacturing choice. With market size expanding from the current base and predictable mid-single-digit CAGR dynamics, 2026 is the year to convert market visibility into durable competitive advantage. PW Consulting’s full report equips leaders with the granular segmentation, supplier scorecards, and scenario models necessary to execute with confidence.
Contact PW Consulting to access the full Precision Glass Molding Market report and bespoke advisory engagements tailored for your 2026 strategic planning cycle.
For detailed analysis of this topic, please visit the official page: Precision Glass Molding Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: HF Acid Market to Reach USD 4,405 Million by 2032 at 5.15% CAGR
By pmarketresearch, 2026-07-23
Hydrofluoric Acid Market 2026: Strategic Primer for Executive Decision-Making
As companies plan capital allocation and supply-chain strategy for 2026, hydrofluoric acid (HF) is resurfacing as a material strategic risk and commercial opportunity. PW Consulting’s latest market study — grounded in a 2020–2025 historical series and a 2026–2032 forecast — synthesizes the demand drivers, supply-side shocks, regulatory inflection points and competitive positions that will determine winners and losers in the HF value chain. This primer distills the report’s highest-value insights to inform board-level discussions, while intentionally withholding detailed segment tables and plant-level exposures that are included in the full research deliverable.
Hydro Fluoric Acid Market
Market trajectory at a glance
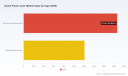
Our base-year snapshot (2025) shows a global HF market approximately USD 3,093 million (USD Million, base year 2025), following steady expansion from about USD 2,500 million in 2020. Momentum into 2026 projects a market exceeding USD 3,240 million, with an expected compound annual growth rate (CAGR) of roughly 5.15% through 2032, when the market is modeled to surpass USD 4,400 million. The near-term acceleration reflects recovery and reinvestment across fluorochemicals, specialty refrigerants and industrial applications; the longer-term curve is driven by electronics demand, material substitution, and evolving environmental constraints.
Hydro Fluoric Acid Market
Why HF matters for 2026 corporate strategy
- Feedstock criticality: HF is not a generic commodity — it is a feedstock for fluorochemicals, specialty refrigerants, aluminum processing and electronics manufacturing. Short-term availability or quality disruptions ripple rapidly through downstream product lines.
- Concentrated supply base: Industry concentration means a small group of producers exerts meaningful influence over accessible supply and pricing. A focused commercial strategy — with contingency for supplier risk — is therefore non-negotiable.
- Regulatory and social license risk: Emerging regulatory actions and public-health scrutiny are elevating operational and reputational risk for producers and users alike.
Supply and raw-material dynamics shaping 2026
Two linked upstream dynamics are especially material. First, fluorspar — the primary source of fluorine inputs — experienced a modest global production contraction in 2025. Second, import/export flows have shifted meaningfully in recent quarters: certain markets have seen sharp increases in imports amid local mining disruptions and safety-driven rectification. These dynamics collectively compress the short-term buffer that typically cushions HF production, making import dependencies and logistics resilience critical inputs to procurement strategy.
Hydro Fluoric Acid Market
For North American buyers, recent trade flows underscore exposure concentration: a dominant share of HF imports originated from a single neighboring supplier market in late 2025. That pattern creates a vulnerability to trade-policy shifts, route-specific logistics incidents and seasonal demand spikes.
Regulation and public policy — immediate watchpoints
- State-level product rules and toxic-substances lists have moved to the center of HF risk. A prominent U.S. state agency initiated rulemaking in mid-2026 to designate cleaning products containing HF as a priority product — a development with potential downstream implications for formulators and distributors.
- Parallel to product-level action, several producers are undertaking capacity rationalization or site exits as part of corporate restructuring. These closures tighten available global HF capacity and require buyers to reassess contracted volumes and alternate sources.
- Environmental health scrutiny and emergency-response obligations are growing. For producers, enhanced community engagement, capital earmarked for containment and emergency preparedness will increasingly be treated as cost of doing business.
Competitive landscape — what the major players reveal
The HF market is served by a mix of global integrators, regional specialists and niche suppliers. Leading players combine feedstock integration with downstream fluorochemical platforms; others focus on aqueous blends and specialty grades for industrial customers. Key strategic profiles to consider:
- Large integrated producers: Global chemical majors operate high-capacity plants that supply both anhydrous and aqueous HF grades and feed integrated fluorochemical chains. Their strategic advantage is operational scale and the ability to prioritize internal feedstock flows.
- Regional high-purity specialists: Certain Asian and European producers distinguish themselves through high-purity product lines tailored to electronics and specialty etching applications, supported by localized technical service and just-in-time logistics.
- Aqueous and customized-blend suppliers: Regional distributors and manufacturers provide tailored aqueous concentrations and localized supply, emphasizing safety compliance and shorter lead times for industrial markets.
Understanding each supplier’s commercial priorities — export orientation, captive downstream demand, and willingness to supply third parties under spot or contract terms — is critical to shaping procurement strategies and negotiating resilient contracts.
Recent industry events that should change your 2026 plans
- A regulatory initiative in mid-2026 to list certain HF-containing consumer cleaning products as priority items highlights how state-level actions can cascade into commercial restrictions and heightened compliance costs for formulators and retailers.
- Corporate restructuring and site exits announced in the past 12–18 months will remove optionality in specific corridors, necessitating earlier and more diversified sourcing decisions for buyers.
- Industry thought leadership by regional suppliers on trust and domestic-supply advantages underscores an emergent commercial narrative: buyers are increasingly willing to trade unit-cost savings for supply assurance and regulatory alignment.
Strategic implications and recommended actions for 2026
Time horizon matters. Actions that reduce risk in the next 12 months differ from those that create advantage across the 2026–2032 forecast period.
- Near-term (0–12 months): Secure rolling contracts with dual-sourced supply clauses, institute inventory-buffer optimization tied to scenario-based stress tests, and renegotiate freight terms to protect against route-specific shocks. Prioritize suppliers with demonstrable contingency plans and transparent quality systems.
- Medium-term (12–36 months): Evaluate co-investment in local blending or small-scale production to reduce import exposure; incorporate supplier scorecards that weight regulatory resilience and community acceptance; and audit downstream conversion processes to optimize HF consumption efficiency.
- Strategic portfolio decisions (36+ months): Consider partnerships or M&A to secure upstream fluorspar access or HF production capacity, and develop differentiated product offerings based on high-purity or low-environmental-impact credentials aligned with decarbonization and substitution trends.
Operational playbook highlights included in the full report
To support executable decisions, our full study contains granular tools and templates oriented to procurement, operations and corporate strategy teams. These include:
- Supply-risk heatmaps and supplier scorecards (including operational, regulatory and reputational dimensions).
- Scenario-based supply-demand models and price path simulations for 2026–2032.
- Contract playbooks with recommended clauses for force majeure, diversion rights, and environmental compliance pass-through.
- Plant-level risk assessments and emergency-response benchmarking templates.
- M&A screening criteria for upstream feedstock and downstream integration opportunities.
Each tool is calibrated to the market’s expected growth trajectory and to contemporary regulatory pressures. The full report also includes an annex of company profiles and links to primary sources used in our analysis.
How to think about commercial negotiation in 2026
Market tightening and regulatory uncertainty mean price will not be the only leverage in negotiations. Buyers should shift to a total-cost-of-supply framework that captures inventory carrying costs, regulatory compliance expenses, logistics risk premiums and the cost of potential supply restoration. Contract structures that combine volume-flexibility, pre-agreed escalation mechanics and operational transparency (e.g., supplier audits, third-party monitoring) will outperform spot-only strategies in both cost and continuity.
What PW Consulting’s research delivers (and what we intentionally withhold here)
We designed this study to be immediately actionable for executives. The report provides:
- Validated historical market sizing (2020–2025) and a detailed forecast model (2026–2032) with scenario outputs.
- Plant-level exposure matrices, regional flow maps, and application demand curves for downstream sectors.
- Competitive intelligence dossiers on leading suppliers, including strategic intent indicators and likely response scenarios to supply shocks.
- Regulatory and raw-material monitoring dashboards that flag rulemaking, trade-flow shifts and mine production notices.
- A prioritized list of tactical and strategic initiatives tailored to buyer, producer and investor profiles.
To preserve the commercial value of the study and to respect proprietary supplier data, this primer omits full regional and application splits, plant-level capacities and specific contractual language — all of which are available in the subscription report and accompanying datasets.
Immediate next steps for executive teams
- Run a 30–60 day rapid diagnostic using the report’s supplier scorecard to identify single-source exposures and critical-path dependencies.
- Convene a multi-disciplinary steering committee (procurement, operations, HSE, legal) to stress-test existing contracts against the regulatory scenarios highlighted in this study.
- Prioritize small-scale resilience investments — alternate blending capability, buffer inventory, and logistics redundancies — that can be executed within a single budget cycle.
The hydrofluoric acid market is entering a period where strategic foresight, not short-term spot savings, will determine operational continuity and margin stability. PW Consulting’s full study equips decision-makers with the data, scenarios and playbooks to make those calls confidently in 2026.
Accessing the full intelligence
If your 2026 planning cycle requires the detailed tables, regional and application breakdowns, plant-level risk heatmaps and supplier scorecards referenced above, we invite you to consult the complete Hydrofluoric Acid Market report on our website or contact PW Consulting for a briefing. The full dataset contains the granular numbers and scenario models necessary to translate the strategic imperatives summarized here into executable plans.
For detailed analysis of this topic, please visit the official page: Hydro Fluoric Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Holographic Anti-counterfeiting Marks to Reach USD 985M by 2032 at 4.0% CAGR
By pmarketresearch, 2026-07-23
Holographic Anti-counterfeiting Marks Market: Strategic Preview for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present an executive preview of our new Holographic Anti-counterfeiting Marks Market study — a working guide built to inform enterprise strategy in 2026. The study synthesizes a decade of market observation, validated vendor intelligence, regulatory scanning, and techno-commercial scenario planning to equip executives with the frameworks they need to act now and iterate later. Below I summarize the report’s strategic value, the forces reshaping supplier economics, competitive positioning trends, and immediate, executable choices for market participants — while deliberately retaining the report’s proprietary micro-segmentation and model outputs to encourage full access to the primary research.
Holographic Anti-counterfeiting Marks Market
Why this study matters in 2026: the strategic context
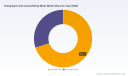
Holographic anti-counterfeiting marks remain a core element of visual authentication strategies across regulated goods and high-value consumer products. After steady expansion through the early 2020s, the global market recorded a base-year size of USD 754 million in 2025 and is modeled to continue expanding at a compound annual growth rate (CAGR) of approximately 4.0% through the 2026–2032 forecast horizon. That trajectory reflects a balance of tailwinds — regulatory mandates, brand-protection programs, and incremental technology adoption — against structural headwinds such as raw material cost pressure and the emergence of digital verification alternatives.
Holographic Anti-counterfeiting Marks Market
For 2026 corporate planners, this combination translates into a market that is sizable and predictable, but not explosive; the window for shaping category economics and securing supply arrangements is now. Late movers can still achieve meaningful differentiation, but they will face higher costs and longer lead times if they await market inflection points that may not materialize until later in the decade.
Holographic Anti-counterfeiting Marks Market
What the full report delivers (practical, executable content)
- Market sizing and validated time series (historical 2020–2025, base year 2025) and a scenario-driven forecast (2026–2032) that models regulatory, raw material and technology-risk tails.
- Regulatory and standards matrix that maps requirements (pharmaceuticals, tobacco, high-value packaging) to solution classes and compliance timelines, enabling compliance-first product roadmaps.
- Technology and production segmentation that explains where value accrues — from hologram master origination through replication, metallization and finishing — and an equipment-capex vs. outsourcing decision framework.
- Supplier landscape and concentration analysis, including competitive benchmarking, capability heat maps, and a CR-analysis that clarifies market power dynamics and partner selection criteria.
- Commercial playbooks: procurement levers, total-cost-of-ownership models, licensing and co-development structures, and a prioritized list of pragmatic quick-win pilots for 6–12 month horizons.
- M&A and partnership scouting: identification of strategic tuck-ins, technology licensors and geographic footholds that accelerate market entry or capability build.
- Operational risk and continuity scenarios: raw-material volatility, equipment lead times (notably for laser-based photoresist recording systems), and contingency actions to protect manufacturing continuity.
- Data annex and methodologies: detailed assumptions, model sensitivities, and guidance for tailoring forecasts to bespoke corporate exposures without exposing our full segmentation tables in this preview.
Market structure and competitive dynamics — what to watch
The global supplier base is fragmented but shows meaningful concentration among a cohort of established optical-security specialists and integrated packaging players. Our concentration analysis indicates that the top firms capture a sizeable share of value — a reminder that trusted credentials, master origination capability, and high-security production lines remain barriers to entry. For buyers, this translates into a trade-off between working with a few deep-specialist partners versus a broader set of regional suppliers for cost or service resilience.
Notable vendor archetypes emerging from our research:
- Heritage optical-security manufacturers with proprietary master-origination and embossing technology — these firms lead on security-grade features and high-certainty delivery for banknote- or document-grade projects.
- Regional converters and packaging conglomerates who combine holographic overlays with flexible-packaging services — attractive for CPG brands seeking end-to-end packaging authentication integrated into manufacturing lines.
- Specialist tamper-evident and transactional security vendors focusing on tapes, seals and labels — they command expertise in tamper and void technologies used in regulated goods.
- New entrants and nimble specialist start-ups bringing digital verification layers or niche micro-structure innovations — capable of accelerating proof-of-concept pilots but often lacking scale at launch.
Our vendor review profiles dozens of players; a selection of noteworthy names demonstrates the breadth of capability and routes to market: multi-decade optical-security producers with global reach, regional specialist manufacturers in high-demand markets, and packaging firms that now include holographic security as part of hybrid solutions. Recent industry shifts — including new membership categories and data tools launched by international optical-security associations in 2026 — are lowering the barrier for innovation collaboration and verification tooling, altering partnership calculus.
Regulation, standards and production realities: decisive forces
Three intertwined dynamics are shaping demand and supplier choices in 2026:
- Regulatory mandates: Recent directives require tamper-proof visual indicators for certain prescription medicines and stronger authentication on regulated products. These compliance timelines are a primary driver of near-term procurement and expansion plans for many manufacturers and brands.
- Standards and verification protocols: Industry-grade standards (including guidance aligned with ISO 12931) and association-led verification tools are raising the floor for what counts as an effective optical-security solution, prompting firms to favor certified production paths and traceable master-origination processes.
- Production-critical hardware and master origination: High-security hologram production hinges on specialized equipment — notably laser-based photoresist recording systems and master origination capabilities — which are capital-intensive and have long lead times. Control over these upstream steps materially affects supply security and margin capture.
These forces favor firms that can combine technically robust originations with compliant manufacturing and rapid integration into packaging lines. For buyers, the practical implication is clear: prioritize partners who can demonstrate traceable masters, standards alignment, and audited production processes.
Recent signals from the field (implications for strategy)
- Association-led initiatives in 2026 expanded membership categories and rolled out practitioner tools for document verification, signaling a push toward standardized verification ecosystems. For corporates, this opens opportunities for interoperability and off-the-shelf verification services to accompany holographic marks.
- Market incumbents continue to mark milestones and expand capabilities — reinforcing that reputation and manufacturing pedigree remain market differentiators. Expect increased consolidation pressure among niche producers as larger players seek vertical integration.
- Evidence from manufacturers highlights that hologram master origination and specialized recording hardware remain the single most critical technical levers. Firms that secure capacity and IP in these areas will influence premium pricing and high-security contracts.
Recommendations for 2026 corporate decision-makers (actionable priorities)
Our study translates market intelligence into a six-point action agenda tailored to three corporate archetypes: brand owners, converters/packagers, and technology providers.
- For brand owners (regulated or high-fraud exposure): map your compliance timeline against regional regulatory mandates, secure long-lead procurement slots for certified suppliers, and pilot multi-factor authentication (visual holograms + digital verification) in high-value SKUs. Treat holographic marks as part of a broader authentication stack rather than a standalone artifact.
- For converters and packaging groups: assess the strategic economics of upstream capability — can you justify capital spend for master origination equipment, or will partnership/licensing deliver better returns? Our TCO model in the report helps quantify break-even timelines under alternate demand scenarios.
- For technology providers and investors: focus on micro-nano structure IP, interoperable verification APIs, and scalable replication processes. Target tuck-in acquisitions that add master-origination expertise or unique tamper-evident chemistries to accelerate product-market fit.
- Cross-cutting: formalize supplier risk assessments that incorporate equipment lead times, raw-material exposure, and certification status. Secure service-level agreements that include quality audits, audit trails for masters, and contingency production pathways.
KPIs, timelines and governance
Start with three practical metrics to govern 2026 programs: (1) time-to-deployment for a pilot SKU (target 90–120 days), (2) certified-master traceability coverage across regulated SKUs (target percent depends on portfolio risk), and (3) supplier continuity score that combines capacity, geographic diversity and certification depth. Embed these into quarterly portfolio reviews and tie procurement commitments to staged performance milestones.
Closing: why read the full report
This preview outlines the strategic stakes: a stable mid-sized market growing at roughly 4% annually, a supplier landscape where mastery of origination and certified processes drives differentiation, and a regulatory/standards backdrop accelerating commercial adoption. The full PW Consulting report contains the operational models, vendor scorecards, regulatory timelines, and executable negotiation playbooks you need to turn this strategic context into near-term wins. We intentionally reserve the segment-level data and granular vendor scoring for the full publication — precisely because those are the elements that power transactional advantage.
For organizations preparing procurement roadmaps, R&D investments, or M&A screens in 2026, this study is designed to be the single reference that converts market signals into disciplined commercial action. PW Consulting is ready to brief your leadership team with a tailored session that maps these insights directly onto your exposure and objectives.
For detailed analysis of this topic, please visit the official page: Holographic Anti-counterfeiting Marks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fabric Reinforcement Rubber Diaphragm Market set to grow at 5.6% CAGR (2026-2032)
By pmarketresearch, 2026-07-23
Fabric Reinforcement Rubber Diaphragm Market — Strategic Imperatives for 2026 Decision-Making
As PW Consulting’s lead industry analyst, I present a focused preview of our comprehensive Fabric Reinforcement Rubber Diaphragm Market study — a briefing designed to arm executive teams with the strategic line-of-sight required for confident 2026 planning. This article synthesizes the report’s macro trajectory, regulatory and technology dynamics, competitive architecture, and the practical diagnostic modules that deliver immediate commercial value. It deliberately showcases analytical depth while withholding granular segment-by-segment figures to drive stakeholders to the full research package for transaction-ready detail.
Fabric Reinforcement Rubber Diaphragm Market
Why this market matters for 2026
The fabric-reinforced rubber diaphragm market is no longer a narrowly technical niche: it sits at the intersection of infrastructure modernization, emissions regulation, and high-reliability applications across automotive, aerospace, industrial, and energy sectors. Our bottom-up sizing shows steady expansion from a 2020 base through to 2025, and the outlook through 2032 reflects sustained growth driven by both replacement cycles and new-build demand in pneumatic actuation, precision regulators, and high-integrity sealing systems.
Fabric Reinforcement Rubber Diaphragm Market
-
Historical trajectory: the global market advanced meaningfully between 2020 and 2025 (base year 2025), reflecting recovery in capital equipment and rising specification complexity in regulated end-markets.
Fabric Reinforcement Rubber Diaphragm Market -
Forecast envelope: with a 2026–2032 compound annual growth rate (CAGR) of 5.6%, the market is projected to expand materially by the end of the forecast window — a profile that supports strategic investment but rewards disciplined prioritization.
-
Practical implication: for procurement, R&D and corporate development teams, the mid-single-digit CAGR signals a market where category consolidation, product premiumization, and specification-driven premium segments will deliver disproportionate margin capture.
What executives need to know — high-level takeaways
-
Demand composition is shifting from purely cost-driven procurement toward performance- and compliance-driven selection. Regulatory drivers (e.g., fugitive emissions control in oil & gas, aerospace fatigue-life mandates, and ISO/ASME conformity requirements) are elevating the value of certified, fabric-reinforced diaphragm solutions.
-
Materials and reinforcement decisions increasingly determine total cost of ownership (TCO). Compound choice (notably EPDM in many applications) and reinforcement architecture are the primary levers that reconcile longevity, chemical compatibility, and cycle-life under dynamic loading.
-
Infrastructure spending in developed markets is a near-term demand tailwind for pneumatic actuator retrofits and new valve installations — an important source of volume lift that also creates opportunities for aftermarket differentiation.
-
Fragmented supply structure: concentration metrics show the top suppliers collectively hold a modest share of market volume, pointing to substantial white space for fast-movers that combine engineering differentiation with scale-up capabilities.
Report contents — what the PW Consulting study delivers
Our full report is structured to convert insight into action. Highlights include:
-
Market sizing and trend analysis (base year 2025, historical 2020–2025, forecast 2026–2032), with demand scenarios, sensitivity testing, and upside/downside cases tied to macro drivers and regulation shifts.
-
Commercial segmentation frameworks and applied use-case economics — enabling price vs. performance trade-offs, end-user TCO models, and specification-driven willingness-to-pay matrices.
-
Supplier benchmarking and capability maps that go beyond logos — assessing engineering depth, testing & certification capacities, manufacturing scale, geographic footprint, and OEM qualification status.
-
Raw material and input-cost analysis, including compound availability dynamics and supply chain risk heatmaps — essential for procurement to lock in margins and for product teams to optimize formulations.
-
Regulatory and standards catalogue: a concise compliance playbook aligned to ISO, ASME, and sector-specific mandates (oil & gas fugitive emission rules; aerospace fatigue-life certification pathways).
-
Go-to-market playbooks and commercial KPIs for market entry, aftermarket expansion, and OEM partnership strategies — complete with product localization checklists and pricing matrices.
-
M&A and partnership screening filters — a prioritized list of capability targets, earnout architectures, and integration risk profiles to accelerate inorganic growth.
-
Implementation roadmaps: 90/180/365 day action plans for product development, certification programs, and channel expansion calibrated to investment appetite and risk tolerance.
Market dynamics and segmentation (directional)
Rather than reproducing every cell from the segmentation tables, the report adds actionable interpretation: materials (natural rubbers, nitrile, EPDM, silicone and specialty elastomers) play differentiated roles across end-uses; device type and reinforcement weave determine fatigue life and chemical resistance; and application context (from automotive actuation to medical fluid systems) dictates testing and traceability requirements. Notably, EPDM compounds have emerged as a dominant production choice in many applications because of their broad chemical compatibility and favorable temperature envelope — an important design consideration for anyone specifying diaphragms today.
We also map how infrastructure spending patterns and sector-specific regulations are changing the mix of new-build versus retrofit demand. This directional segmentation enables clients to prioritize which product development bets and supply-chain investments will generate the highest return through 2026 and beyond.
Competitive landscape — who matters and why
The market features a mix of global engineering brands, specialized elastomer houses, and regional volume producers. Key players profiled in the study include global engineering leaders that supply certified, high-integrity diaphragms for regulated sectors, as well as specialist manufacturers that focus on specific applications such as irrigation, process sealing, or medical fluidics. The report’s supplier dossiers provide:
-
Strategic profiles and go-to-market models for the principal firms.
-
Capability audits (materials expertise, testing labs, OEM approvals).
-
Commercial posture analysis (OEM focus vs. aftermarket, custom tooling capabilities, contract manufacturing readiness).
For commercial planning, the critical insight is that the market’s top firms — while widely recognized for technological leadership — do not yet command overwhelmingly dominant share. This creates windows for strategically differentiated entrants to win OEM-qualified positions or to vertically integrate into adjacent supply chains.
Technology, regulation and procurement implications
Three converging forces will shape supplier economics and procurement strategies through 2026:
-
Regulatory tightening: fugitive-emission controls and aerospace/defense fatigue-life specifications raise the floor for diaphragm performance. Suppliers lacking robust certification programs will face limited access to high-value projects.
-
Materials engineering: compound selection and reinforcement architecture are the primary mechanisms to extend life under cyclic loading and aggressive chemistries. Clients should re-evaluate legacy bill-of-materials for mission-critical applications, prioritizing TCO over unit cost alone.
-
Supply resilience: near-term raw-material availability and regional manufacturing capacity matter for lead times and cost volatility. Procurement teams must integrate long-lead raw-material risk into reorder strategies and qualification timelines.
Recommended actions for 2026 planning
-
Prioritize certification-led product upgrades where regulations create differentiated value. A targeted investment in test-lab capacity and third-party certification can unlock premium contract channels.
-
Use TCO models in procurement negotiations. Buying on lowest unit price alone exposes operators to replacement and downtime costs that exceed material premium.
-
Seek strategic OEM partnerships and co-development arrangements to embed specification requirements early — moving from vendor to innovation partner reduces switching risk.
-
Evaluate bolt-on acquisitions that provide either specialty materials expertise or OEM qualifications that are costly to build organically within certification timelines.
Risk framing and monitoring
The report includes a concise risk matrix tying probability and business impact to the primary threats: regulatory shifts, raw material supply shocks, certification delays, and competitive pricing pressure from unqualified low-cost producers. For each risk we propose monitoring triggers and mitigating tactics — for example, dual-sourcing strategies, hedged raw-material contracts, and staged certification milestones linked to customer acceptance criteria.
Next steps — where to get the full intelligence
This article is a strategic preview intended to surface the most consequential insights for 2026 decision cycles. The full PW Consulting study contains the granular segmentation, detailed supplier scorecards, downloadable financial models, and executable 90/180/365 day playbooks required to act decisively. For teams charged with procurement optimization, product roadmapping, or M&A scouting in this space, the report converts market momentum into a practical program.
Access the complete market intelligence and the datasets that underpin our forecasts through the PW Consulting portal — the exact segmentation tables, pricing ladders, and supplier benchmarking matrices are available there to support your strategic and transaction workstreams.
For detailed analysis of this topic, please visit the official page: Fabric Reinforcement Rubber Diaphragm Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rainscreen Cladding Market to Grow at 8.2% CAGR Through 2032
By pmarketresearch, 2026-07-23
Rainscreen Cladding Market: Strategic Imperatives for 2026 Decision-Making
As PW Consulting’s lead industry analyst, I present a focused executive primer on the rainscreen cladding market designed to inform strategic decisions through 2026 and beyond. This piece synthesizes our latest market modeling (base year 2025, historical window 2020–2025, forecast 2026–2032) and situates actionable recommendations against the most material industry developments—regulatory shifts, raw-material inflation, supplier moves, and changing buyer requirements. Consider this a high-fidelity trailer: it reveals the analytical framework, directional market performance, competitive dynamics, and tactical playbooks you need to align near-term investments, while reserving full segment granularity to the complete report.
Rainscreen Cladding Market
Why 2026 is a Strategic Inflection Point
- Market momentum: The global rainscreen cladding market has expanded rapidly over the past half-decade and continues on a clear growth trajectory. Our base-year modeling shows meaningful expansion from 2020 through 2025, and an 8.2% CAGR underpins projections into the 2026–2032 forecast window. The market’s scale in 2025 and its projected size by the end of the forecast horizon reflect substantial addressable demand for façade systems that meet modern thermal, acoustic, and fire-safety expectations.
- Regulatory tightening and material substitution: Starting in 2025–2026, a cluster of high-impact regulations and local code updates (notably in the UK and key U.S. states) are redefining acceptable cladding materials and certification pathways. These mandates create both compliance risk and product-adoption opportunities for manufacturers and specifiers.
- Supply-side pressure: Volatility in key commodity inputs—principally aluminum and steel—combined with new tariffs and capacity investments are shifting cost curves and creating winners and losers among regional suppliers. Procurement and design decisions made in 2026 will materially affect margin trajectories and time-to-market for new systems.
What the Full Report Delivers (Practical, Transaction-Ready)
PW Consulting’s full Rainscreen Cladding Market report is oriented to drive commercial outcomes. It contains:
Rainscreen Cladding Market
- Proprietary market-sizing and top-down forecast (2026–2032) with scenario variants reflecting regulatory stringency and raw-material price pathways.
- Supplier and product map: verified vendor capabilities, route-to-market profiles, and an investment heatmap for manufacturing and distribution footprints.
- Commercial impact models: cost-to-serve simulations, margin sensitivity to input-price shocks and tariffs, and price-elasticity guidance for tender strategy.
- Regulatory playbook: certification checklists, testing roadmaps, and compliance risk matrices keyed to major markets (including new UK and U.S. requirements).
- Procurement and supply-chain playbooks: hedging approaches, dual-sourcing templates, and near-term capex prioritization frameworks to manage lead times and price spikes.
- M&A and partnership intelligence: target characteristics, valuation comps, and integration risk checklists designed for acquirers or JV partners.
- Implementation templates: specification language to embed in RFPs, product bundling strategies for architects and contractors, and a go-to-market sprint plan for 12–18 months.
Competitive Dynamics: Who’s Moving, and What It Means
The market remains moderately fragmented, with the top three and top five vendors capturing meaningful but not overwhelming shares of the market. Our concentration metrics show a market where leaders exert influence—particularly over standards and system-level solutions—but mid-sized and specialist players still command niche and regional advantage. This structure creates room for both scale-driven consolidation and focused differentiation plays.
Rainscreen Cladding Market
- Kingspan Group plc (Ireland): Continuing product innovation and a recent launch of eco-focused rainscreen systems highlight Kingspan’s strategy of combining sustainability credentials with façade performance. For competitors and specifiers, Kingspan’s moves ratchet up the sustainability bar for global tenders and public-sector specifications.
- Rockwool International A/S (Denmark): Expanded European manufacturing capacity for stone wool reflects anticipatory positioning around non-combustible insulation demand. This capacity expansion tightens supply-side competition for mineral-based solutions and accelerates availability for large-scale retrofit programs.
- Cladding Corp (United States): As a North American systems integrator, Cladding Corp’s full-engineering support model shows the commercial advantage of bundling drained and back-ventilated systems with specification and installation engineering—especially in markets where local codes demand rigorous documentation.
- Alucobond (Germany): The strategic partnership with architectural practices to co-develop high-rise cladding indicates a route-to-spec advantage for aluminum-composite offerings, despite recent commodity volatility. Architectural partnerships can accelerate adoption in premium high-rise projects.
- Sotech Optima Company (UK): Product introductions such as non-combustible brick-look systems illustrate how smaller innovators can capture specification momentum by solving narrow but urgent problems—e.g., reconciling aesthetic demand with new fire-safety expectations.
Regulatory and Cost Drivers to Watch (and Hedge Against)
- Material bans and stricter testing: National and regional rules (including a complete ban in certain jurisdictions on specific combustible core materials) are narrowing acceptable material sets for new construction and some retrofits. These changes create near-term demand for compliant alternatives and longer-term advantages for vendors with validated non-combustible systems and fast certification pathways.
- Tariffs and commodity inflation: Recent aluminum and steel price surges, together with new import tariffs in select jurisdictions, materially raise landed costs for metal-based panels and framing. Procurement plays should focus on local sourcing, forward contracts, and modularization strategies that reduce metal intensity where possible.
- Local code divergence: Increasingly strict rules in leading U.S. states and municipalities favor non-combustible systems above a certain building height, changing specification behavior for large developers and system integrators. This will accelerate uptake of stone-wool, ceramic, and certain engineered composite systems in those markets.
Strategic Plays for 2026: Priorities and Actions
Below are prioritized moves that executives should consider to manage risk and capture upside in 2026.
- Update product roadmaps for code-driven demand. Near-term: accelerate development and certification of non-combustible variants and provide clear testing data to specifiers. Mid-term: diversify platform designs to allow a rapid swap of infill panels and insulation cores without retooling major assemblies.
- Reconfigure sourcing and pricing models to absorb commodity shocks. Near-term: add commodity pass-through clauses in new contracts, secure forward purchase agreements for critical metals, and evaluate partial localization of panel fabrication. Mid-term: invest in alternative material R&D to reduce metal intensity per square meter.
- Build compliance-as-a-service capabilities. Near-term: provide standardized certification packages, third-party testing coordination, and documentation bundles to make bids “code-proof.” Mid-term: offer subscription-based monitoring and updates to customers as regulations evolve.
- Pursue selective M&A and partnerships focused on certification, specialty materials, and regional scale. Near-term: prioritize bolt-on assets that deliver testing labs or non-combustible material capacity. Mid-term: evaluate catalytic acquisitions that close time-to-market gaps in high-growth regions.
- Differentiate through systems integration and lifecycle economics. Near-term: quantify total cost of ownership (TCO) benefits—maintenance, energy, and insurance impacts—and incorporate these narratives into tenders. Mid-term: develop product-service bundles (warranties, maintenance) that lock in longer-term revenue streams.
- Accelerate digital spec tools and BIM content. Near-term: ensure ready-to-use BIM families with compliance metadata for major markets. Mid-term: embed cost and carbon metrics in digital tools to make sustainability and regulatory trade-offs transparent to architects and clients.
Commercial Impact: Modeling Outcomes and KPIs
Decision-makers should track a focused set of KPIs tied to the strategies above: warranty claims tied to fire performance, market-win rate on tenders exceeding code requirements, margin delta attributable to hedging strategies, and revenue share from certified non-combustible products. Under our base forecast—supported by an 8.2% CAGR—firms that execute on the prioritized plays are positioned to outpace market growth and improve margin resilience as commodity and regulatory pressures persist.
How to Use This Insight in Practice (90‑ to 180‑Day Playbook)
- Run a 90-day supply-chain stress test: map single-source dependencies, quantify tariff exposure by SKU, and initiate at least two alternative sourcing conversations.
- Launch a compliance sprint: complete third-party testing and certification roadmaps for top three product families aimed at high-risk geographies.
- Prepare two commercial pilots: one targeting retrofit programs with non-combustible offerings and one targeting new high-rise construction with architect partnerships.
- Set a six-month M&A screening cadence for targets meeting capacity, certification, or regional distribution criteria.
Closing: Why PW Consulting’s Market View Matters for 2026
Rainscreen cladding is now a convergence point for safety regulation, sustainability goals, and architectural ambition. The choices firms make in 2026—about product portfolios, sourcing footprint, certification investment, and go-to-market motions—will determine who captures the premium value that accrues to compliant, cost-effective, and low-risk systems over the next eight years. Our report couples a transparent macro forecast with executable commercial tools to reduce execution risk and accelerate market capture.
For full segment-level intelligence, supplier scorecards, and downloadable implementation toolkits, access the complete PW Consulting Rainscreen Cladding Market report. The detailed breakouts and modeled scenarios are intentionally reserved to give subscribers the competitive advantage required to act decisively in 2026.
For detailed analysis of this topic, please visit the official page: Rainscreen Cladding Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Spunbond Nonwoven Fabrics Market Poised for 6.1% CAGR Through 2032
By pmarketresearch, 2026-07-23
Spunbond Nonwoven Fabrics: Strategic Intelligence for 2026 Decision-Making
As PW Consulting’s senior strategic advisor and lead industry analyst, I present a high-fidelity preview of our latest Spunbond Nonwoven Fabrics Market study — designed to be the operational intelligence brief executives, corporate strategists and investors will use to make decisive moves in 2026. The global spunbond market has demonstrated resilient expansion, climbing from roughly USD 13.1 Billion in 2020 to about USD 17.6 Billion in 2025, and is modeled to continue growing at an annualized pace of approximately 6.1% through the 2026–2032 forecast horizon. This trajectory underpins a multiyear opportunity set, but it is layered with cost, regulatory and structural inflection points that will determine winners and losers.
Spunbond Nonwoven Fabrics Market
Why this study matters for 2026 strategy
-
Timing: 2026 is a pivot year. Recent capacity announcements and raw-material volatility have compressed the window for capacity deployment, pricing renegotiations, and sustainability investments. Our study maps actionable entry and exit signals tied to those dynamics.
Spunbond Nonwoven Fabrics Market -
Clarity: You will get a holistic view of demand drivers, supply elasticity, and regulatory pressure that goes beyond surface-level growth rates — enabling precise allocation of capital and commercial effort without overexposure to cyclical shocks.
Spunbond Nonwoven Fabrics Market -
Execution-Focused: The report translates market intelligence into playbooks — from procurement hedging to product roadmaps — so leadership teams can convert market forecasts into quarterly and annual plans.
High-level market context and growth outlook
The spunbond market’s steady scale-up since 2020 reflects accelerating end-market adoption across hygiene, medical, filtration, construction and engineered goods. From the 2020 base to the 2025 midpoint, demand expanded materially, reflecting both volume growth and an ongoing premiumization toward higher-performance and sustainability-focused grades. With a projected compound annual growth in the mid-single digits through 2032, the market presents attractive tailwinds for incumbents and new entrants — provided they navigate three structural constraints: feedstock cost volatility, regulatory headwinds on plastics and differential investment in capacity and technology.
Key demand and supply inflection points for 2026
-
Demand sequencing: Hygiene and medical applications remain demand anchors, while industrial and automotive segments are staging higher-margin, specialized opportunities. Buyers are increasingly discriminating on lifecycle performance and recycled content — shifting procurement criteria from cost-only to total-cost-of-ownership and circularity metrics.
-
Raw-material pressure: Polypropylene feedstock experienced sharp input-price turbulence in the most recent cycle, increasing by roughly a quarter on a year-over-year basis as of early 2026. That magnitude of movement is sufficient to force margin recalibrations, accelerate pass-through negotiations, and trigger supplier consolidation where scale reduces feedstock exposure.
-
Regulatory re-pricing: Trade measures (notably tariffs affecting polypropylene imports), the EU’s carbon and packaging policy frameworks, and chemical-substance compliance (REACH/SVHC) are already reshaping regional cost competitiveness and forcing product reformulation. For 2026 planners, regulatory timelines create discrete investment milestones: compliance by a given date, supply-chain requalification windows, and potential cost adders that must be modeled into pricing strategies.
Competitive landscape — who matters and why
The industry is populated by global diversified polymers and materials players, specialist nonwovens manufacturers, and regionally focused producers. Leading names — from integrated converters to technology-intensive suppliers — are pursuing differentiated strategies: scale investments, product premiumization, sustainability certification, and customer-centric integration. Key market participants include several major global groups and regional champions; each operates with distinct value propositions tied to scale, technology, geographic footprint and end-market focus.
-
Scale players are leveraging vertical integration and multi-site footprints to defend margins and service global customer platforms. These companies are the primary bidders in large hygiene and consumer contracts and often set the market’s benchmark pricing cadence.
-
Technology-driven suppliers focus on high-performance and filtration grades, where production complexity and product specification create higher barriers to entry and permit premium pricing.
-
Regional specialists capture niche demand and offer agility on localized specifications, but face higher cost and feedstock exposure during commodity swings.
Recent capacity developments underscore these strategic archetypes: several major investments announced in 2025 expanded high-speed, flexible spunbond lines and large-scale polypropylene capacity in North America and select export hubs — moves that materially shift supply-side dynamics and will create localized overhangs if demand slows or if recycled-content adoption compresses demand for virgin-resin grades.
What this means for competition in 2026
-
Margin stratification will deepen. Companies that combine scale with sustainability-verified recycled content or bio-based alternatives will command stronger pricing leverage.
-
Contract structures will evolve. Buyers will seek blended sourcing agreements with embedded environmental clauses, longer take-or-pay commitments for critical volumes, and more frequent escalation clauses tied to feedstock indices.
-
M&A choreography will intensify around recycling technologies, meltblown/spunbond hybrid capabilities, and regional capacity that provides trade-shift advantages in the face of tariffs and carbon-adjustment regimes.
Practical playbook: actions for executives in 2026
-
Hedge and diversify feedstock exposure. Use a mix of supply contracts, resin-forward purchases and strategic partnerships with refiners or recyclers to smooth margin volatility. Scenario-run your P&L across a +/- 30% resin-price swing to understand cash-flow sensitivity.
-
Accelerate sustainable product migration. Prioritize product lines where recycled content or bio-based inputs offer price parity or a defensible margin advantage when regulatory compliance costs are internalized by competitors.
-
De-risk capacity rollout. Stage greenfield investments with modular, high-speed lines and include contractual off-ramps or buyer commitments where possible. Alternative: pursue bolt-on acquisitions of established lines to compress time-to-market.
-
Rework commercial contracts. Insert indexed pricing mechanisms tied to transparent resin indices, and negotiate clauses that protect against abrupt trade-policy shifts (e.g., import tariff shocks).
-
Invest in traceability. Implement chain-of-custody and LCA tools to meet REACH/SVHC and packaging-waste compliance while creating commercial differentiation for sustainability-conscious buyers.
M&A and capital allocation signals to watch
Investment flows in 2025–26 highlight where strategic buyers see value: capacity that supports premium, high-loft or filtration grades; recycling and polymer-reprocessing capabilities that shortcut compliance risk; and manufacturing lines that can be retooled across product classes. Buyers should favor targets with stable customer contracts, clean environmental records and demonstrable cost takeout potential via integration. Conversely, vintages of assets heavily tied to virgin-polypropylene without a clear retrofit pathway will face greater integration risk and valuation pressure.
Report contents — what the full study delivers (practical, not theoretical)
-
Comprehensive market-size model with base-year calibration (2025) and scenario-based forecasts through 2032, including sensitivity to raw-material price regimes and regulatory cost advents.
-
Actionable commercial playbooks, with templates for pricing escalation clauses, RFP language for recycled-content supply and procurement hedging frameworks.
-
Detailed competitive benchmarking across product capability, capacity footprint, technology mix, and go-to-market strength — enabling rapid identification of partners, acquisition targets and at-risk competitors.
-
Regulatory-roadmap annexes that map compliance deadlines, certification needs and likely compliance-cost trajectories for major trade regions.
-
Interactive scenario models (licenseable) that let you test capacity deployment, margin resiliency and payoff periods for sustainability investments under multiple policy and price assumptions.
How PW Consulting’s insight translates into 2026 outcomes
Decision-makers who use the study will be able to: prioritize CAPEX and M&A with a disciplined trigger framework; reconfigure commercial contracts to protect margins in an era of feedstock volatility and trade-policy uncertainty; and accelerate product and process innovation in areas where regulatory and buyer preferences create durable value. The study is deliberately operational — you get frameworks you can implement in 90–180 day planning cycles rather than abstract projections.
Next steps
This preview outlines the strategic contours of the spunbond nonwoven landscape entering 2026: a market with reliable mid-single-digit growth at the aggregate level, but one being actively reshaped by input cost shocks, regulatory realignments and a wave of capacity and technology investments. For teams that need executable intelligence — actionable models, granular segment analysis, company-level diagnostics and an acquisition playbook tailored to your balance-sheet — the full PW Consulting report and its accompanying tools provide the granular detail required for confident, timely execution.
Contact PW Consulting to access the full study, including proprietary segment matrices, company profiles, and the scenario engine that underpins our recommendations. Use the report to make your 2026 capital and commercial choices with conviction — not conjecture.
For detailed analysis of this topic, please visit the official page: Spunbond Nonwoven Fabrics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Microcrystalline Wax Market to Hit USD 1,934 Million by 2032 at 4.15% CAGR
By pmarketresearch, 2026-07-23
Microcrystalline Wax Market — 2026 Strategic Preview
Executive snapshot
As PW Consulting’s lead industry analyst, I present a strategic preview of the Microcrystalline Wax market designed to inform high-consequence decisions in 2026. The market is transitioning from a post‑pandemic recovery phase into a structurally reshaped environment driven by feedstock volatility, tightening trade regimes, and a sustainability‑centred product race. On a macro basis, the market was valued at approximately USD 1,425 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of about 4.15% through our forecast horizon, arriving near USD 1,934 Million by 2032. Concentration metrics indicate a moderately consolidated supply base, with the top three and top five players accounting for a meaningful share of industry supply — a dynamic that amplifies the impact of strategic moves by incumbents.
Microcrystalline Wax Market
Why this briefing matters for 2026 decision-makers
-
Time-sensitive regulatory changes and trade actions in 2025–2026 have altered risk profiles for sourcing and market access. Procurement, legal, and commercial teams must re-evaluate supplier exposure and customs duty scenarios now, not later.
Microcrystalline Wax Market -
Feedstock price shocks and logistics dislocations have compressed margins for downstream formulators; our actionable scenarios enable CFOs and sourcing leads to model hedging, pass‑through, and inventory strategies under realistic stress cases.
Microcrystalline Wax Market -
Product and sustainability differentiation is becoming commercially meaningful: suppliers with low‑PCF (Product Carbon Footprint) grades and micronized offerings are securing faster adoption in coatings, cosmetics, and specialty applications. R&D and commercial leaders require a prioritized playbook for portfolio moves and customer segmentation to capture premium value.
Market snapshot and trajectory
Our consolidated market model shows steady expansion from the 2020 base through 2025 and a continuation of growth across the 2026–2032 forecast window. While headline CAGR is modest, the path to that average is uneven: short windows of price appreciation and periodic demand shifts create tactical windows for margin capture as well as downside risk. The market’s CR3 and CR5 concentration ratios confirm that strategic moves by a handful of large refiners and specialty producers materially influence pricing, availability, and service levels for downstream customers.
Key demand and supply dynamics (high-level)
-
Demand drivers: end‑use innovation in adhesives, packaging, and personal care continues to expand total addressable demand, while premiumization (high‑purity and low‑PCF grades) is carving out faster‑growing subsegments.
-
Supply constraints and cost pressure: crude benchmarks and refinery throughput constraints have pushed feedstock costs higher; the sector saw average price increases in early 2026 driven by those input costs. Logistics and intermediate feedstock availability remain sensitive to regional conflicts and refinery maintenance cycles.
-
Trade and regulatory friction: recent import restrictions and targeted trade measures have raised the cost and complexity of cross‑border flows for mineral waxes, requiring commercial teams to bake tariff and compliance contingencies into annual planning.
Regulatory and trade environment — immediate implications
Three developments in 2025–2026 materially changed the operating envelope:
-
Targeted import restrictions implemented by select jurisdictions have explicitly named mineral waxes — this raises compliance overhead for importers and encourages near‑sourcing where possible.
-
U.S. trade actions in early 2026 expanded forced‑labor import bans and proposed ad valorem duties affecting mineral waxes, increasing the cost of certain supply corridors and elevating supplier vetting requirements.
-
Harmonized Tariff Schedule entries and per‑weight duties (as applied in certain markets) introduce a predictable but non‑negligible incremental cost that procurement teams must include when comparing landed costs across suppliers.
For executives, the immediate takeaways are threefold: (1) revalidate supplier compliance and traceability, (2) quantify landed‑cost sensitivity to tariff and duty scenarios, and (3) build contingency sourcing and inventory options into 2026 operating plans.
Competitive landscape — who moves markets
The competitive axis is split between large integrated petrochemical majors and focused specialty wax houses. Each class of player brings different levers:
-
Global majors: offer scale, broad geographic reach, and capacity flexibility. Example: a major integrated energy company markets a branded microcrystalline portfolio spanning fully refined to semi‑refined grades for packaging, adhesives, construction, personal care, and rubber — enabling one‑stop supply contracts for multinational formulators.
-
Specialty and regional players: focus on FDA‑compliant grades, niche delivery formats (granules, pellets, slabs, liquid blends), and closer customer service for industries such as cosmetics and food‑grade packaging. Their agility is an advantage in tailored formulations and speed to market.
-
Technology‑ and sustainability‑focused suppliers: have begun to commercialize micronized and lower‑PCF grades, attracting customers targeting lower Scope 3 footprints in coatings, inks, and plastics.
Notable company moves in 2024–2026 — product launches at the top end of the market and portfolio expansions at specialty houses — underscore the bifurcation between scale and specialty. Recent activity includes the introduction of high‑purity microcrystalline lines by a major integrated producer and expanded micronized low‑PCF grades by a leading chemical company, both of which materially affect competitive dynamics and customer sourcing choices.
Recent developments that reshape near‑term strategy
-
Product innovations: suppliers launched new high‑purity and micronized microcrystalline wax grades with demonstrably lower product carbon footprints — these products command strategic attention from formulators seeking downstream sustainability claims.
-
Trade measures and customs updates: amendments to certain countries’ trade controls and tariff headings now explicitly include mineral waxes, prompting immediate reassessment of import protocols.
-
Feedstock and geopolitical shocks: conflict‑related disruptions to regional feedstock flows have increased volatility in naphtha, LPG and natural gas derivatives, translating to raw material cost swings for wax producers.
What PW Consulting’s full report delivers (practical and actionable)
Our full market study is built for practitioners who must translate analysis into P&L outcomes. Highlights include:
-
Transparent financial model: scenario‑based revenue and price modeling (base, upside, and stress cases) with configurable inputs for feedstock cost, tariff exposure, and contract pass‑through assumptions.
-
Supply‑chain mapping and risk heatmap: validated supplier lists, logistics corridors, and single‑point‑of‑failure nodes with mitigation playbooks (dual sourcing, forward inventory, tolling options).
-
Commercial playbooks: pricing playbooks for premium vs. commoditized grades, route‑to‑market options for new product introductions, and customer segmentation matrices keyed to margin expansion opportunities.
-
Regulatory compliance matrix and customs impact module: jurisdictional rules, likely duty outcomes under multiple scenarios, and a checklist for import compliance and due‑diligence documentation.
-
M&A and partnership screen: prioritized target shortlist and valuation sensitivity framework for buyers seeking capacity, specialty grades, or regional footholds.
-
R&D and sustainability roadmap: comparative analysis of low‑PCF approaches, micronization economics, and likely adoption curves across end industries.
Each section includes raw datasets, supplier scorecards, and model templates that executives can adapt directly into procurement negotiation decks, strategic plans, and board papers.
Strategic imperatives for 2026
-
Operationalize traceability now: integrate supplier audits, chain‑of‑custody data, and customs compliance into quarterly procurement KPI targets to avoid near‑term trade disruptions.
-
Segment product strategy by value capture rather than volume alone: prioritize commercialization of lower‑PCF and high‑purity grades where customers will pay a premium.
-
Stress‑test supply and pricing with live scenarios: use the report’s financial model to quantify margin outcomes across tariff, feedstock, and demand shock permutations and set trigger points for hedging/stocking.
-
Pursue targeted partnerships and bolt‑on acquisitions: identify specialty producers that accelerate access to regulated or premium end markets, rather than broad, undifferentiated capacity buys.
-
Embed regulatory intelligence into commercial planning: anticipate further tightening of forced‑labour and import regimes; build compliance costs into long‑term supplier contracts.
How PW Consulting’s insights turn into competitive advantage
In 2026, the winners will be companies that translate market intelligence into operational change quickly. That means converting scenario outputs into procurement contracts, turning supplier scorecards into preferred‑supplier programs, and aligning R&D roadmaps with the commercial appetite for low‑PCF grades. Our market model and tactical playbooks are designed to move teams from insight to action within 30–90 days.
Next steps
This preview illustrates the strategic contours and immediate levers for executives in 2026. The full Microcrystalline Wax Market report contains the detailed datasets, proprietary supplier scoring, and executable templates that underpin the recommendations summarized above. For teams preparing budget cycles, sourcing strategies, or M&A screens this year, our analysis provides a plug‑and‑play foundation. Contact PW Consulting to access the complete dataset, bespoke scenario runs, and an executive briefing tailored to your company’s exposure.
For detailed analysis of this topic, please visit the official page: Microcrystalline Wax Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Concrete Expansion Joint Market hits USD 596.4M in 2025, eyes 5.8% CAGR
By pmarketresearch, 2026-07-23
Concrete Expansion Joint Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a strategic introduction to our Concrete Expansion Joint Market research — the intelligence that should sit at the center of any 2026 commercial, procurement, and M&A decision related to infrastructure and building sealants and joint systems. The market is neither static nor purely technical; it is shaped by macro construction cycles, materials chemistry, regulatory shifts, and a fragmented supplier base. Our study uses a 2025 base year and traces market movements from 2020 through 2025 before delivering a scenario-tested forecast to 2032. Under the central scenario, the market grows at a compound annual growth rate (CAGR) of 5.8%, expanding from a mid-single‑hundreds million USD base in 2025 to a substantially larger addressable market by 2032.
Concrete Expansion Joint Market
Why this research matters for 2026 decisions
-
Timing of capital: Infrastructure funding cycles and retrofit windows are driving concentrated procurement in the next 18–36 months. The report pinpoints where near-term demand acceleration is most likely and which product attributes will determine win rates when contracts are tendered.
Concrete Expansion Joint Market -
Cost-to-serve optimization: Material cost volatility is elevating margin risk. We translate raw-material price swings into procurement levers and specification changes that buyers and manufacturers can use to protect margins or strengthen bids.
Concrete Expansion Joint Market -
M&A and consolidation: With national and regional players holding modest shares (the three largest firms together account for a low double-digit share and the top five remain small in aggregate), there is room for strategic roll-ups — especially for buyers seeking scale in manufacturing, distribution, or specification influence.
-
Regulatory and sustainability risk: VOC limits and evolving environmental requirements are impacting product formulations and project specifications; our analysis details compliance cost trajectories and practical reformulation pathways.
What the full report delivers (practical, transaction-grade content)
-
Actionable market sizing and forecast model (2020–2032): Transparently modelled, with scenario toggles for construction activity, raw-material price stress, and regulatory tightening. The base-case shows a consistent growth path post-2025 at a 5.8% CAGR through 2032.
-
Demand drivers and use-case playbooks: Segmented buyer archetypes, specification decision trees (public works vs. private developers), and lifecycle cost comparisons that move beyond installed cost to whole-of-life value propositions.
-
Competitive landscaping and target lists: Profiles of incumbent specialists and cross-sector entrants, capability matrices, and an evidence-based shortlist of likely acquisition targets for strategic buyers. (Download the full report for granular target scoring and valuations.)
-
Procurement and hedging toolkit: Practical contracts language, inventory and hedging strategies for polyurethane and silicone-based sealants, and supplier risk-assessment templates keyed to feedstock exposure.
-
Regulatory impact matrix: Stepwise cost implications of VOC limits, preferred test methods, and recommended product reformulations to maintain compliance while safeguarding performance.
-
Technology and product roadmap: Material innovation priorities, durability benchmarks, and spec-level guidance for systems that reduce maintenance cycles and total cost of ownership.
-
Risk scenarios and stress tests: Quantified impact of raw-material shocks, trade-tariff episodes, and rapid regional construction slowdowns on revenues and margins.
Market dynamics you need to integrate into 2026 planning
-
Raw-material volatility: Formulations for polymeric sealants and elastomeric joints remain exposed to specific feedstocks. Polyurethane systems, for example, depend on isocyanate and polyol chemistry — with pricing and availability closely linked to the economics of toluene di‑isocyanate and MDI production and, broadly, petroleum-derived feedstock costs. Procurement teams must map exposure to these inputs and layer in contingency pricing clauses or alternative-sourcing plans.
-
Commodity supply shocks: In Q1 2026, Dimethyldichlorosilane prices rose sharply year-on-year — a near-term driver of silicone-based sealant cost inflation. The proximate causes were outages at chlor-alkali production units and higher tariffs on silicon metal. Separately, major chemical suppliers have announced price increases in response to energy and feedstock disruptions; for example, a leading producer implemented a mid-single-digit price adjustment in April 2026. Our report includes supplier-by-supplier exposure maps that translate these developments into P&L impacts.
-
Regulatory tightening: Stricter VOC emission limits are increasing formulation complexity and elevating production costs for construction sealants. Manufacturers face a dual pressure: invest in low‑VOC chemistry and capture specification authority through testing and certification, or risk losing share as public and institutional buyers mandate compliant materials.
-
Fragmented competitive structure: Market concentration metrics indicate a fragmented industry — with the top three and top five suppliers together controlling a modest portion of total sales. Low concentration creates both risk (price competition) and opportunity (roll-up plays, national distribution agreements, and specification capture through service differentiation).
Competitive posture: what incumbents and challengers are doing
-
D.S. Brown Company (North Baltimore, OH): A specialist in engineered rubber and elastomeric expansion systems for bridges and pavements, D.S. Brown emphasizes durability and high-movement solutions. Recent communications highlight strip-seal technologies as among the longest-lasting sealed expansion joint systems and capable of accommodating significant movement ranges. For buyers and specifiers, that performance profile translates into a premium value proposition for long-span bridges and heavy-duty pavements — but also a need to benchmark lifecycle costs against competing modular or foam-based systems.
-
Sika Emseal (USA): Emseal brings elastomeric expansion joint systems, covers, and complementary sealants targeted at buildings and infrastructure. Their strength lies in integrated system solutions and a focus on specification support for projects where airtightness, fire resistance, or acoustic performance drives procurement decisions. For strategic planners, Emseal represents the archetypal supplier that converts specification authority into recurring project wins via performance guarantees and rigorous certification.
Strategic implications and recommended plays for 2026
-
For manufacturers: Prioritise raw-material diversification and invest in low‑VOC reformulations that preserve adhesion and movement capacity. Use short-term hedging and strategic procurement partnerships with chemical suppliers to blunt margin erosion from feedstock spikes.
-
For buyers and contractors: Embed lifecycle costing into tender evaluations and insist on performance warranties that shift long-term maintenance risk to suppliers. For large infrastructure portfolios, negotiate volume-linked pricing or long-term supply agreements with performance KPIs.
-
For investors and private equity: Look for roll-up opportunities that consolidate manufacturing scale, distribution, and specification services. Targets that bring integrated testing laboratories, specification-writing capabilities, or strong regional government contract pipelines command a premium.
-
For product managers and R&D: Focus on systems that reduce installation time and maintenance frequency — for instance, durable strip-seal solutions that handle wide movement ranges, and modular covers that simplify replacement operations. Certification pathways (fire, acoustic, VOC) are increasingly value-driving.
Decision framework and KPIs we recommend
-
Revenue resilience score (3-year): Combines contract backlog, publicworks exposure, and product lifetime-service contracts.
-
Feedstock exposure index: Quantifies percentage of cost base tied to volatile inputs (isocyanates, silicone precursors) and the availability of alternates.
-
Specification capture metric: Tracks the share of projects where the supplier is named on the approved product list or included in pre-approved vendor lists for major agencies.
-
Maintenance-at-risk ratio: Projected future maintenance spend per linear meter by product class — a lever for differentiating bids via total cost of ownership.
How to use this preview
This introduction outlines the strategic contours of the Concrete Expansion Joint Market and the practical levers that matter in 2026. To preserve the operational value of the study, detailed regional, type and application splits, and granular company-level revenue breakouts are withheld from this preview. The full report contains the complete segmentation tables, supplier scorecards, and downloadable financial models that enable scenario testing and transaction modelling.
If you are evaluating procurement strategies, assessing an acquisition, or defining a product roadmap for 2026, PW Consulting’s full Concrete Expansion Joint Market report will provide the calibrated, operational intelligence you need to move from insight to action. Contact our research team to arrange access to the full dataset, model access, and a tailored briefing that aligns the findings to your business objectives.
For detailed analysis of this topic, please visit the official page: Concrete Expansion Joint Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Long Glass Fiber-Reinforced PP to reach USD 11,124.5M by 2032 (6.8% CAGR)
By pmarketresearch, 2026-07-23
Long Glass Fiber Reinforced Polypropylene (LGF PP): Strategic Preview for 2026 Decision-Makers
Executive snapshot
As organizations plan capital allocation and product roadmaps for 2026, understanding the trajectory of long glass fiber reinforced polypropylene (LGF PP) has moved from a technical curiosity to a commercial necessity. PW Consulting’s latest market positioning work shows the LGF PP market expanding from roughly USD 7.67 billion in our 2025 base year to more than USD 11.12 billion by 2032, underpinned by a forecast compound annual growth rate (CAGR) of 6.8% across the 2026–2032 horizon. These macro dynamics create discrete opportunity windows—and corresponding risk vectors—for resin producers, compounders, OEMs, and converters. This article previews the strategic value of our full study for 2026 decision-making while preserving the core segment-level intelligence that subscribers will find in the full report.
Long Glass Fiber Reinforced Polypropylene Market
Why LGF PP matters to corporate strategy in 2026
-
Regulatory pressure is forcing product and material choices. Vehicle emissions targets in key markets—driven by EU directives and US regulatory trajectories—are accelerating the adoption of lightweight, high-stiffness polymers. LGF PP is positioned as a leading thermoplastic replacement for metal and glass-filled alternatives where structural performance and weight reduction are required.
Long Glass Fiber Reinforced Polypropylene Market -
Market growth is broad-based but not uniform. The market’s expansion to the low double-digit billions by 2032 reflects new and expanded use-cases in automotive, aerospace, electrical & electronics, and engineered consumer applications. Crucially, adoption is being driven both by product performance advances (higher fiber contents, improved fiber-matrix adhesion) and by manufacturing-scale efficiencies in compound production and injection molding.
Long Glass Fiber Reinforced Polypropylene Market -
Supply-chain economics are actively reshaping competitive advantage. Volatility in upstream feedstocks—propylene price shifts noted in early 2025—and recent movements in glass fiber pricing (notably a price point observed in December 2025) are compressing some producer margins while creating windows for vertically integrated players and those with secured feedstock arrangements to expand market share.
How this market snapshot should shape 2026 choices
-
Portfolio and capacity planning: Firms setting capacity investments or plant re-tooling for 2026 should use a demand-led approach focused on high-growth use-cases identified in our full report. Our long-range projections indicate sustained demand that justifies selective greenfield or brownfield expansion—if tied to identifiable purchasing commitments or OEM program wins.
-
M&A and partnership playbook: With market concentration metrics showing a top-three share that indicates meaningful consolidation (our analysis flags a CR3 around the high‑fifties and CR5 approaching seventy percent), 2026 is a tactically attractive year for bolt-on acquisitions that provide technical differentiation (e.g., proprietary impregnation technologies, coupling agents) or route-to-customer access in priority verticals.
-
Price & margin management: Operators should adopt scenario-driven pricing models that incorporate feedstock volatility and the elasticities we model for key end-markets. Near-term raw material indices suggest downward pressure on glass fiber into late 2025, but propylene-driven resin cost pressure remained notable through early 2025—creating asymmetric cost risk for compounders lacking hedging or vertical integration.
Value-chain implications: from raw material to OEM
-
Raw materials: Glass fiber and polypropylene feedstock dynamics are the proximate determinants of LGF PP manufacturing economics. Our study models several feedstock scenarios and their midcycle impacts on compound pricing. Buyers and suppliers should align contracts and consider blended procurement strategies to protect margins while preserving price competitiveness for OEMs.
-
Compounding & processing: Advances in melt impregnation and continuous fiber technologies are shifting the performance-cost frontier. Companies that invest in process control, quality consistency, and higher-fiber-load capabilities can unlock OEM design wins for structural components that previously defaulted to heavier materials.
-
OEM engineering and qualification: For automotive and aerospace OEMs, LGF PP offers a path to meet CO2/fuel efficiency targets without redesigning entire architectures. However, qualification timelines and safety/performance validation remain non-trivial—time-to-production hinges on early supplier involvement and rigorous part-level testing, considerations we map in program-level case studies in the full report.
Competitive landscape: what leading players are investing in
The LGF PP competitive map is a mix of global petrochemical majors, specialty compounders, and regional systems houses. Key companies we profile include SABIC, BASF, LyondellBasell, Japan Polypropylene Corporation, RTP Company, Avient, Celanese, and Mitsui Chemicals. Each entity approaches the market with distinct capabilities:
-
SABIC (Riyadh) combines resin development with application-focused formulations—highlighted by product lines aimed at automotive lightweighting and structural components.
-
BASF (Ludwigshafen) leverages a materials-science basis to position LGF PP within a broader engineering plastics portfolio for technical applications.
-
LyondellBasell (Houston) emphasizes proprietary resin platforms and scale, aiming to supply OEM-driven demand at competitive price points.
-
Japan Polypropylene Corporation (Tokyo) and Mitsui Chemicals (Tokyo) bring process-specific differentiation—particularly in melt impregnation technologies and an Asia–US–Japan manufacturing footprint tailored to regional OEM requirements.
-
Specialty compounders—RTP (Winnebago), Avient (Cincinnati), and Celanese (Irving)—focus on custom formulations, engineering support, and certifications that facilitate fast OEM adoption, particularly where program compliance and specific mechanical property targets are decisive.
Our competitive assessment in the full report pairs these strategic positions with capability heatmaps, program-win case studies, and supplier negotiation playbooks—insights crucial for both incumbents and entrants planning 2026 moves.
What the full report delivers (practical, decision-ready content)
-
Validated market sizing and growth scenarios. We provide a base-year benchmark and multiple forecast trajectories tied to policy, macroeconomic, and technology adoption inputs—so you can stress-test capacity and revenue plans against plausible futures.
-
Adoption pathways and OEM qualification timelines. For each priority vertical we map engineering milestones, typical qualification lead times, and cost thresholds that determine program viability.
-
Supply-chain and margin sensitivity analyses. Our models quantify margin sensitivity across feedstock and fiber price swings and show the break-even points where vertical integration or long-term offtake secures competitive advantage.
-
Commercial go-to-market playbooks. We provide tactics for supplier selection, price negotiation, co-development agreements, and M&A prioritization to accelerate share capture without overpaying for growth.
-
Competitive intelligence dossier. For the companies named above, the report contains capability matrices, recent strategic moves, technological differentiators, and program references—suitable for informing RFPs, JV discussions, or acquisition targets.
Strategic recommendations for 2026 planning cycles
-
Prioritize dual-track investments: retain optionality between incremental capacity upgrades and targeted strategic acquisitions. The market’s projected growth is sufficient to support both, but timing and execution must match OEM program cycles.
-
Lock in raw material strategies: pursue a mix of long-term contracts, index-based hedges, and selective vertical integration to smooth margin volatility driven by resin and fiber pricing.
-
Invest in manufacturability and qualification capabilities: supplychain wins are frequently decided at the part-development stage. Investing in prototype tooling, engineering support, and application labs reduces go-to-market friction.
-
Use concentrated market structure to your advantage: where CR metrics show a top-tier concentration, small, targeted partnerships or bolt-on acquisitions can deliver outsized access to OEM programs and established distribution channels.
Closing — the strategic value of the PW Consulting study
For executives and strategy teams preparing budgets and program plans for 2026, our LGF PP market study transforms general market optimism into actionable decisions. By converting headline growth—an expected rise from a multibillion-dollar base in 2025 to over USD 11 billion by 2032—into decision-ready intelligence (demand by use-case, supplier capabilities, margin sensitivities, and program-level qualification timelines), the report reduces execution risk and accelerates time-to-revenue.
We intentionally withheld granular segment-level disclosures in this preview to ensure subscribers obtain the unredacted data, commercial mappings, and supplier metrics that underpin confident capital and commercial commitments. To access the complete forecast tables, segmentation breakdowns, company dossiers, and the tactical playbooks tailored for 2026 implementation, please visit the full study on our website.
For detailed analysis of this topic, please visit the official page: Long Glass Fiber Reinforced Polypropylene Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com