

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Spunbond Nonwoven Fabrics Market Poised for 6.1% CAGR Through 2032

Spunbond Nonwoven Fabrics: Strategic Intelligence for 2026 Decision-Making
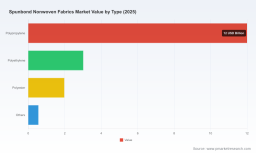
As PW Consulting’s senior strategic advisor and lead industry analyst, I present a high-fidelity preview of our latest Spunbond Nonwoven Fabrics Market study — designed to be the operational intelligence brief executives, corporate strategists and investors will use to make decisive moves in 2026. The global spunbond market has demonstrated resilient expansion, climbing from roughly USD 13.1 Billion in 2020 to about USD 17.6 Billion in 2025, and is modeled to continue growing at an annualized pace of approximately 6.1% through the 2026–2032 forecast horizon. This trajectory underpins a multiyear opportunity set, but it is layered with cost, regulatory and structural inflection points that will determine winners and losers.
Spunbond Nonwoven Fabrics Market
Why this study matters for 2026 strategy
-
Timing: 2026 is a pivot year. Recent capacity announcements and raw-material volatility have compressed the window for capacity deployment, pricing renegotiations, and sustainability investments. Our study maps actionable entry and exit signals tied to those dynamics.
Spunbond Nonwoven Fabrics Market -
Clarity: You will get a holistic view of demand drivers, supply elasticity, and regulatory pressure that goes beyond surface-level growth rates — enabling precise allocation of capital and commercial effort without overexposure to cyclical shocks.
Spunbond Nonwoven Fabrics Market -
Execution-Focused: The report translates market intelligence into playbooks — from procurement hedging to product roadmaps — so leadership teams can convert market forecasts into quarterly and annual plans.
High-level market context and growth outlook
The spunbond market’s steady scale-up since 2020 reflects accelerating end-market adoption across hygiene, medical, filtration, construction and engineered goods. From the 2020 base to the 2025 midpoint, demand expanded materially, reflecting both volume growth and an ongoing premiumization toward higher-performance and sustainability-focused grades. With a projected compound annual growth in the mid-single digits through 2032, the market presents attractive tailwinds for incumbents and new entrants — provided they navigate three structural constraints: feedstock cost volatility, regulatory headwinds on plastics and differential investment in capacity and technology.
Key demand and supply inflection points for 2026
-
Demand sequencing: Hygiene and medical applications remain demand anchors, while industrial and automotive segments are staging higher-margin, specialized opportunities. Buyers are increasingly discriminating on lifecycle performance and recycled content — shifting procurement criteria from cost-only to total-cost-of-ownership and circularity metrics.
-
Raw-material pressure: Polypropylene feedstock experienced sharp input-price turbulence in the most recent cycle, increasing by roughly a quarter on a year-over-year basis as of early 2026. That magnitude of movement is sufficient to force margin recalibrations, accelerate pass-through negotiations, and trigger supplier consolidation where scale reduces feedstock exposure.
-
Regulatory re-pricing: Trade measures (notably tariffs affecting polypropylene imports), the EU’s carbon and packaging policy frameworks, and chemical-substance compliance (REACH/SVHC) are already reshaping regional cost competitiveness and forcing product reformulation. For 2026 planners, regulatory timelines create discrete investment milestones: compliance by a given date, supply-chain requalification windows, and potential cost adders that must be modeled into pricing strategies.
Competitive landscape — who matters and why
The industry is populated by global diversified polymers and materials players, specialist nonwovens manufacturers, and regionally focused producers. Leading names — from integrated converters to technology-intensive suppliers — are pursuing differentiated strategies: scale investments, product premiumization, sustainability certification, and customer-centric integration. Key market participants include several major global groups and regional champions; each operates with distinct value propositions tied to scale, technology, geographic footprint and end-market focus.
-
Scale players are leveraging vertical integration and multi-site footprints to defend margins and service global customer platforms. These companies are the primary bidders in large hygiene and consumer contracts and often set the market’s benchmark pricing cadence.
-
Technology-driven suppliers focus on high-performance and filtration grades, where production complexity and product specification create higher barriers to entry and permit premium pricing.
-
Regional specialists capture niche demand and offer agility on localized specifications, but face higher cost and feedstock exposure during commodity swings.
Recent capacity developments underscore these strategic archetypes: several major investments announced in 2025 expanded high-speed, flexible spunbond lines and large-scale polypropylene capacity in North America and select export hubs — moves that materially shift supply-side dynamics and will create localized overhangs if demand slows or if recycled-content adoption compresses demand for virgin-resin grades.
What this means for competition in 2026
-
Margin stratification will deepen. Companies that combine scale with sustainability-verified recycled content or bio-based alternatives will command stronger pricing leverage.
-
Contract structures will evolve. Buyers will seek blended sourcing agreements with embedded environmental clauses, longer take-or-pay commitments for critical volumes, and more frequent escalation clauses tied to feedstock indices.
-
M&A choreography will intensify around recycling technologies, meltblown/spunbond hybrid capabilities, and regional capacity that provides trade-shift advantages in the face of tariffs and carbon-adjustment regimes.
Practical playbook: actions for executives in 2026
-
Hedge and diversify feedstock exposure. Use a mix of supply contracts, resin-forward purchases and strategic partnerships with refiners or recyclers to smooth margin volatility. Scenario-run your P&L across a +/- 30% resin-price swing to understand cash-flow sensitivity.
-
Accelerate sustainable product migration. Prioritize product lines where recycled content or bio-based inputs offer price parity or a defensible margin advantage when regulatory compliance costs are internalized by competitors.
-
De-risk capacity rollout. Stage greenfield investments with modular, high-speed lines and include contractual off-ramps or buyer commitments where possible. Alternative: pursue bolt-on acquisitions of established lines to compress time-to-market.
-
Rework commercial contracts. Insert indexed pricing mechanisms tied to transparent resin indices, and negotiate clauses that protect against abrupt trade-policy shifts (e.g., import tariff shocks).
-
Invest in traceability. Implement chain-of-custody and LCA tools to meet REACH/SVHC and packaging-waste compliance while creating commercial differentiation for sustainability-conscious buyers.
M&A and capital allocation signals to watch
Investment flows in 2025–26 highlight where strategic buyers see value: capacity that supports premium, high-loft or filtration grades; recycling and polymer-reprocessing capabilities that shortcut compliance risk; and manufacturing lines that can be retooled across product classes. Buyers should favor targets with stable customer contracts, clean environmental records and demonstrable cost takeout potential via integration. Conversely, vintages of assets heavily tied to virgin-polypropylene without a clear retrofit pathway will face greater integration risk and valuation pressure.
Report contents — what the full study delivers (practical, not theoretical)
-
Comprehensive market-size model with base-year calibration (2025) and scenario-based forecasts through 2032, including sensitivity to raw-material price regimes and regulatory cost advents.
-
Actionable commercial playbooks, with templates for pricing escalation clauses, RFP language for recycled-content supply and procurement hedging frameworks.
-
Detailed competitive benchmarking across product capability, capacity footprint, technology mix, and go-to-market strength — enabling rapid identification of partners, acquisition targets and at-risk competitors.
-
Regulatory-roadmap annexes that map compliance deadlines, certification needs and likely compliance-cost trajectories for major trade regions.
-
Interactive scenario models (licenseable) that let you test capacity deployment, margin resiliency and payoff periods for sustainability investments under multiple policy and price assumptions.
How PW Consulting’s insight translates into 2026 outcomes
Decision-makers who use the study will be able to: prioritize CAPEX and M&A with a disciplined trigger framework; reconfigure commercial contracts to protect margins in an era of feedstock volatility and trade-policy uncertainty; and accelerate product and process innovation in areas where regulatory and buyer preferences create durable value. The study is deliberately operational — you get frameworks you can implement in 90–180 day planning cycles rather than abstract projections.
Next steps
This preview outlines the strategic contours of the spunbond nonwoven landscape entering 2026: a market with reliable mid-single-digit growth at the aggregate level, but one being actively reshaped by input cost shocks, regulatory realignments and a wave of capacity and technology investments. For teams that need executable intelligence — actionable models, granular segment analysis, company-level diagnostics and an acquisition playbook tailored to your balance-sheet — the full PW Consulting report and its accompanying tools provide the granular detail required for confident, timely execution.
Contact PW Consulting to access the full study, including proprietary segment matrices, company profiles, and the scenario engine that underpins our recommendations. Use the report to make your 2026 capital and commercial choices with conviction — not conjecture.
For detailed analysis of this topic, please visit the official page: Spunbond Nonwoven Fabrics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com