

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Carbon-Carbon Composites to hit USD 334.67M by 2032 (6.55% CAGR)

Carbon-Carbon Composites 2026 Strategic Preview: Why This Market Report Matters to Executive Decision-Making
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused preview of our new Carbon-Carbon Composite Material Market study — a practical, decision-oriented resource tailored for boardrooms, corporate development teams, and industrial strategists preparing for 2026. This preview synthesizes the macro trajectory, structural dynamics, and competitive moves that should shape any capital, sourcing or commercial decision in the coming 18–36 months. Detailed, segment-level intelligence is intentionally reserved for the full report; the purpose here is to show analytical depth while preserving the tactical granularity that drives commercial advantage.
Carbon-Carbon Composite Material Market
Market trajectory — a compact, actionable view
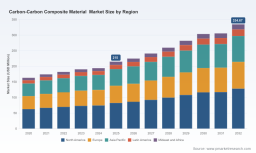
The carbon-carbon composite market has moved from niche specialty material into a scaling commercial sector with clear demand drivers and rising strategic importance. Our baseline sizing shows the market increasing from approximately USD 163.2 million in 2020 to USD 215.0 million by the 2025 base year — reflecting both steady end-market adoption and price dynamics. Looking forward, the market is forecast to grow at a compound annual growth rate (CAGR) of 6.55% through our 2026–2032 forecast window, reaching roughly USD 334.7 million by 2032.
Carbon-Carbon Composite Material Market
Two practical takeaways for 2026 planning: first, the growth profile is sufficiently robust to justify targeted capacity investments and R&D commitments for those seeking to capture premium end-markets (aerospace thermal protection, high-temperature industrial components, and advanced braking systems). Second, growth is uneven by capability and application; value will accrue to firms that combine material science leadership with qualified supply relationships into aerospace and defense OEMs.
Carbon-Carbon Composite Material Market
Structural dynamics that will determine winners and losers
- Supplier concentration and precursor risk: The upstream supply of carbon fiber precursors is highly concentrated. This creates a pinch-point for carbon-carbon producers and elevates the value of secured, diversified precursor arrangements — especially during periods of demand acceleration or policy-driven trade shifts.
- Production economics: Global production tonnage and pricing trends matter as much as revenue growth. In 2024, global production reached the tens of thousands of tonnes, with an average selling price in the low thousands of USD per tonne; nuances of capacity utilization and product mix will drive margin differentials more than headline revenue in 2026.
- Policy and tariff sensitivity: Recent tariff framework changes and evolving trade policy have already increased export costs and highlighted the need for redundant manufacturing footprints close to key end-markets. Firms with global footprint flexibility and near-market production will gain a competitive edge in contract awards.
- Environmental and feedstock regulation: Environmental restrictions impacting PAN-based precursor production are not peripheral — they affect upstream costs, capital intensity, and permit timing. Leaders will be those who incorporate precursor security and regulatory scenario planning into capital allocation decisions.
- Market concentration at producer level: The industry displays a high degree of seller concentration — the top suppliers capture the majority of the market — which favors incumbents on long-term contracts but opens windows for regional challengers who can guarantee supply continuity or superior cost.
Why this report is operationally valuable for 2026 decisions
Board-level questions in 2026 will be less about “is this market growing?” and more about “how do we allocate scarce capital and managerial attention to maximize rate-of-return while de-risking supply?” Our report is structured to answer those questions with tools and templates you can operationalize immediately:
- Actionable market sizing and three-tier scenario modeling (conservative, base, upside) calibrated to tariff, precursor availability, and aerospace demand shocks.
- Manufacturing cost curves and margin sensitivity analyses (unit economics by process route), enabling rapid ROI checks on capacity projects and retrofits.
- Supply-chain resilience playbook: supplier scorecards, dual-sourcing templates, and contracting strategies to lock precursor supply without overpaying for optionality.
- Commercial playbooks for OEM partnerships — with negotiation levers and risk allocation language for long-term off-take agreements.
- M&A screening and integration checklist targeted at bolt-on targets, vertical-integration candidates (precurors, densification specialists), and regional capacity entrants.
- Regulatory and ESG impact matrix addressing PAN precursor regulation, tariff scenarios and permitting timelines for new facilities.
- Proprietary company dossiers, supplier maps and a competitive heat map to prioritize commercial outreach and partnership testing.
Competitive landscape — what incumbents are doing and why it matters
The current competitive set includes global materials champions, specialty carbon firms, and a growing cohort of regional producers. Several recent industry moves crystallize the strategic playbook:
- Capacity expansion aligns with aerospace and advanced mobility demand: Major producers and OEM partners have announced or initiated capacity increases aimed at the high-margin aerospace and premium automotive segments. These moves indicate companies are betting on sustained demand for thermal protection and braking systems that favor carbon-carbon composites.
- Strategic vertical plays and product launches: Firms are both extending upstream (precursor and precursor technology) and enhancing product portfolios (next-gen prepregs, densified C/C). Sustainability- and performance-branded launches signal that differentiation will increasingly rest on proprietary processing and lifecycle advantages.
- Portfolio reshaping through asset transactions: Divestments and acquisitions in the space suggest players are optimizing for focus on core technologies — enabling faster commercialization cycles for niche thermal protection systems while creating acquisition targets for scaling manufacturers.
For executive teams, the competitive implications are clear: scale matters for meeting OEM qualification timelines, but specialty IP and supply security are equally critical. A binary strategy — either scale at all costs or remain a niche player — is risky. The optimal position for 2026 is hybrid: selective capacity growth combined with strategic partnerships or minority stakes in precursor and processing technology providers.
Emerging strategic options to consider for 2026
- Near-market capacity investments: Prioritize small- to mid-scale production nodes in geographies exposed to tariff volatility to shorten lead times and reduce logistics risk.
- Precursor hedging and JV models: Move beyond spot contracts. Consider joint ventures or long-term offtakes with leading precursor producers to secure volumes and stabilize input costs.
- Product differentiation via densification and surface engineering: Invest in processing capabilities that improve durability under extreme thermal cycling — a value driver for aerospace thermal protection and braking systems.
- Selective M&A and strategic minority stakes: Use capital to access IP and supplier continuity (e.g., densification specialists, precursor recyclers) rather than pursuing broad horizontal consolidation.
- Regulatory and ESG roadmap: Build an upstream emissions and feedstock compliance plan; this reduces permitting risk and can be a commercial differentiator for OEM partners focused on ESG.
Case in point: signals from recent industry developments
- Large-scale capacity expansions at leading chemical and composites firms underscore a near-term supply response to aerospace and space program demand.
- OEM-led facility investments and contract shifts reflect a desire to secure qualified domestic supply chains for critical thermal protection and braking systems.
- Product launches with sustainability branding indicate that customers are beginning to value lifecycle attributes — a trend that will shape procurement specifications over the next three years.
What the full PW Consulting report delivers (reserved tactical detail)
The full report translates the strategic implications above into executable initiatives. It contains segment-level market shares, regional demand curves, application-specific adoption timelines, supplier pricing matrices, and a prioritized deal pipeline for M&A and JV targets. We also include a ready-to-use board briefing deck and an executive decision matrix that maps capital allocation choices to expected IRR ranges under alternative policy and demand scenarios.
For executives evaluating capex, M&A, or supply-chain diversification in 2026, this is not an academic exercise — it is the operational intelligence that reduces execution risk and concentrates investment where the highest, fastest returns are available. To preserve competitive advantage, we reserve the full, segment-level data and model access for report subscribers.
Next steps for corporate leaders
- Begin or update a two-way stress test of your supply chain under tariff and precursor-constrained scenarios. Use the results to define minimum viable local capacity needs.
- Identify one or two precursor counterparties for deeper commercial engagement (JV or long-term offtake) and perform fast-track diligence using the supplier scorecards in our toolkit.
- Prioritize investment in processing capabilities that convert carbon-carbon advantages (thermal, high-temp structural) into certified products for aerospace and premium automotive OEMs.
- Request the full PW Consulting report to access the segment-level modeling, company dossiers, and the transactional playbook required to operationalize these steps.
In 2026, decisions about where to invest, whom to partner with, and how to manage precursor risk will determine which companies capture disproportionate value as the carbon-carbon market scales. PW Consulting’s report transforms those strategic choices from high-level debate into executable programs — but the granular data that unlocks specific commercial moves is reserved for the full study. Contact PW Consulting to obtain access and convert this strategic preview into a robust 2026 action plan.
For detailed analysis of this topic, please visit the official page: Carbon-Carbon Composite Material Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com