

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Rainscreen Cladding Market to Grow at 8.2% CAGR Through 2032

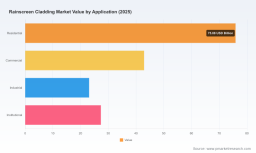
Rainscreen Cladding Market: Strategic Imperatives for 2026 Decision-Making
As PW Consulting’s lead industry analyst, I present a focused executive primer on the rainscreen cladding market designed to inform strategic decisions through 2026 and beyond. This piece synthesizes our latest market modeling (base year 2025, historical window 2020–2025, forecast 2026–2032) and situates actionable recommendations against the most material industry developments—regulatory shifts, raw-material inflation, supplier moves, and changing buyer requirements. Consider this a high-fidelity trailer: it reveals the analytical framework, directional market performance, competitive dynamics, and tactical playbooks you need to align near-term investments, while reserving full segment granularity to the complete report.
Rainscreen Cladding Market
Why 2026 is a Strategic Inflection Point
- Market momentum: The global rainscreen cladding market has expanded rapidly over the past half-decade and continues on a clear growth trajectory. Our base-year modeling shows meaningful expansion from 2020 through 2025, and an 8.2% CAGR underpins projections into the 2026–2032 forecast window. The market’s scale in 2025 and its projected size by the end of the forecast horizon reflect substantial addressable demand for façade systems that meet modern thermal, acoustic, and fire-safety expectations.
- Regulatory tightening and material substitution: Starting in 2025–2026, a cluster of high-impact regulations and local code updates (notably in the UK and key U.S. states) are redefining acceptable cladding materials and certification pathways. These mandates create both compliance risk and product-adoption opportunities for manufacturers and specifiers.
- Supply-side pressure: Volatility in key commodity inputs—principally aluminum and steel—combined with new tariffs and capacity investments are shifting cost curves and creating winners and losers among regional suppliers. Procurement and design decisions made in 2026 will materially affect margin trajectories and time-to-market for new systems.
What the Full Report Delivers (Practical, Transaction-Ready)
PW Consulting’s full Rainscreen Cladding Market report is oriented to drive commercial outcomes. It contains:
Rainscreen Cladding Market
- Proprietary market-sizing and top-down forecast (2026–2032) with scenario variants reflecting regulatory stringency and raw-material price pathways.
- Supplier and product map: verified vendor capabilities, route-to-market profiles, and an investment heatmap for manufacturing and distribution footprints.
- Commercial impact models: cost-to-serve simulations, margin sensitivity to input-price shocks and tariffs, and price-elasticity guidance for tender strategy.
- Regulatory playbook: certification checklists, testing roadmaps, and compliance risk matrices keyed to major markets (including new UK and U.S. requirements).
- Procurement and supply-chain playbooks: hedging approaches, dual-sourcing templates, and near-term capex prioritization frameworks to manage lead times and price spikes.
- M&A and partnership intelligence: target characteristics, valuation comps, and integration risk checklists designed for acquirers or JV partners.
- Implementation templates: specification language to embed in RFPs, product bundling strategies for architects and contractors, and a go-to-market sprint plan for 12–18 months.
Competitive Dynamics: Who’s Moving, and What It Means
The market remains moderately fragmented, with the top three and top five vendors capturing meaningful but not overwhelming shares of the market. Our concentration metrics show a market where leaders exert influence—particularly over standards and system-level solutions—but mid-sized and specialist players still command niche and regional advantage. This structure creates room for both scale-driven consolidation and focused differentiation plays.
Rainscreen Cladding Market
- Kingspan Group plc (Ireland): Continuing product innovation and a recent launch of eco-focused rainscreen systems highlight Kingspan’s strategy of combining sustainability credentials with façade performance. For competitors and specifiers, Kingspan’s moves ratchet up the sustainability bar for global tenders and public-sector specifications.
- Rockwool International A/S (Denmark): Expanded European manufacturing capacity for stone wool reflects anticipatory positioning around non-combustible insulation demand. This capacity expansion tightens supply-side competition for mineral-based solutions and accelerates availability for large-scale retrofit programs.
- Cladding Corp (United States): As a North American systems integrator, Cladding Corp’s full-engineering support model shows the commercial advantage of bundling drained and back-ventilated systems with specification and installation engineering—especially in markets where local codes demand rigorous documentation.
- Alucobond (Germany): The strategic partnership with architectural practices to co-develop high-rise cladding indicates a route-to-spec advantage for aluminum-composite offerings, despite recent commodity volatility. Architectural partnerships can accelerate adoption in premium high-rise projects.
- Sotech Optima Company (UK): Product introductions such as non-combustible brick-look systems illustrate how smaller innovators can capture specification momentum by solving narrow but urgent problems—e.g., reconciling aesthetic demand with new fire-safety expectations.
Regulatory and Cost Drivers to Watch (and Hedge Against)
- Material bans and stricter testing: National and regional rules (including a complete ban in certain jurisdictions on specific combustible core materials) are narrowing acceptable material sets for new construction and some retrofits. These changes create near-term demand for compliant alternatives and longer-term advantages for vendors with validated non-combustible systems and fast certification pathways.
- Tariffs and commodity inflation: Recent aluminum and steel price surges, together with new import tariffs in select jurisdictions, materially raise landed costs for metal-based panels and framing. Procurement plays should focus on local sourcing, forward contracts, and modularization strategies that reduce metal intensity where possible.
- Local code divergence: Increasingly strict rules in leading U.S. states and municipalities favor non-combustible systems above a certain building height, changing specification behavior for large developers and system integrators. This will accelerate uptake of stone-wool, ceramic, and certain engineered composite systems in those markets.
Strategic Plays for 2026: Priorities and Actions
Below are prioritized moves that executives should consider to manage risk and capture upside in 2026.
- Update product roadmaps for code-driven demand. Near-term: accelerate development and certification of non-combustible variants and provide clear testing data to specifiers. Mid-term: diversify platform designs to allow a rapid swap of infill panels and insulation cores without retooling major assemblies.
- Reconfigure sourcing and pricing models to absorb commodity shocks. Near-term: add commodity pass-through clauses in new contracts, secure forward purchase agreements for critical metals, and evaluate partial localization of panel fabrication. Mid-term: invest in alternative material R&D to reduce metal intensity per square meter.
- Build compliance-as-a-service capabilities. Near-term: provide standardized certification packages, third-party testing coordination, and documentation bundles to make bids “code-proof.” Mid-term: offer subscription-based monitoring and updates to customers as regulations evolve.
- Pursue selective M&A and partnerships focused on certification, specialty materials, and regional scale. Near-term: prioritize bolt-on assets that deliver testing labs or non-combustible material capacity. Mid-term: evaluate catalytic acquisitions that close time-to-market gaps in high-growth regions.
- Differentiate through systems integration and lifecycle economics. Near-term: quantify total cost of ownership (TCO) benefits—maintenance, energy, and insurance impacts—and incorporate these narratives into tenders. Mid-term: develop product-service bundles (warranties, maintenance) that lock in longer-term revenue streams.
- Accelerate digital spec tools and BIM content. Near-term: ensure ready-to-use BIM families with compliance metadata for major markets. Mid-term: embed cost and carbon metrics in digital tools to make sustainability and regulatory trade-offs transparent to architects and clients.
Commercial Impact: Modeling Outcomes and KPIs
Decision-makers should track a focused set of KPIs tied to the strategies above: warranty claims tied to fire performance, market-win rate on tenders exceeding code requirements, margin delta attributable to hedging strategies, and revenue share from certified non-combustible products. Under our base forecast—supported by an 8.2% CAGR—firms that execute on the prioritized plays are positioned to outpace market growth and improve margin resilience as commodity and regulatory pressures persist.
How to Use This Insight in Practice (90‑ to 180‑Day Playbook)
- Run a 90-day supply-chain stress test: map single-source dependencies, quantify tariff exposure by SKU, and initiate at least two alternative sourcing conversations.
- Launch a compliance sprint: complete third-party testing and certification roadmaps for top three product families aimed at high-risk geographies.
- Prepare two commercial pilots: one targeting retrofit programs with non-combustible offerings and one targeting new high-rise construction with architect partnerships.
- Set a six-month M&A screening cadence for targets meeting capacity, certification, or regional distribution criteria.
Closing: Why PW Consulting’s Market View Matters for 2026
Rainscreen cladding is now a convergence point for safety regulation, sustainability goals, and architectural ambition. The choices firms make in 2026—about product portfolios, sourcing footprint, certification investment, and go-to-market motions—will determine who captures the premium value that accrues to compliant, cost-effective, and low-risk systems over the next eight years. Our report couples a transparent macro forecast with executable commercial tools to reduce execution risk and accelerate market capture.
For full segment-level intelligence, supplier scorecards, and downloadable implementation toolkits, access the complete PW Consulting Rainscreen Cladding Market report. The detailed breakouts and modeled scenarios are intentionally reserved to give subscribers the competitive advantage required to act decisively in 2026.
For detailed analysis of this topic, please visit the official page: Rainscreen Cladding Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com