

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Precision Glass Molding Market to Reach USD 30,423M by 2032 at 7.2% CAGR

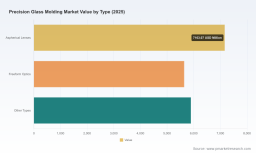
Precision Glass Molding Market: Strategic Primer for 2026 Decision-Makers
By PW Consulting — Senior Strategic Advisor & Chief Industry Analyst
Precision Glass Molding Market
Executive overview
Precision glass molding (PGM) is shifting from a niche manufacturing technique to a strategic manufacturing platform for optics across consumer electronics, automotive, industrial sensing, and infrared imaging. Our latest market model — calibrated to a 2025 base year and covering 2026–2032 — quantifies a clear expansion trajectory: the PGM market is estimated at roughly USD 18.7 billion in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 7.2% through the forecast window, reaching the low‑to‑mid tens of billions by 2032. This steady expansion reflects converging demand drivers: optical performance requirements that exceed injection-molded plastics, accelerating volume production for compact multi-lens modules, and new materials and tooling innovations that materially compress unit cost curves.
Precision Glass Molding Market
Why this matters for 2026 strategy
-
Investment timing: The 7.2% CAGR creates a runway for measured capacity expansion. Companies that commit selectively in 2026 — either through CAPEX for molding machines or targeted partnerships with experienced PGM suppliers — can secure yield and time-to-market advantages as OEMs demand higher optical fidelity.
Precision Glass Molding Market -
Material and supply‑chain risk: Rising raw-material cost pressure remains the single largest adoption barrier, particularly where glass costs and specialized preforms dominate unit economics. Concurrently, geopolitical controls (notably export restrictions on materials such as germanium) are catalyzing alternative material pathways, including broader industrial adoption of chalcogenide glasses for infrared optics. These dual forces require procurement and product teams to simulate alternative supply scenarios now.
-
Competitive positioning: The market exhibits meaningful concentration — the top-tier PGM suppliers control a substantial share of volume production — creating both barriers and opportunities. New entrants must either differentiate on proprietary tooling and process intelligence or pursue vertical integration to compress per-unit cost.
What PW Consulting’s report delivers (practical, transaction‑ready content)
This study was designed as an operational playbook for executives, product leads, and corporate development teams. It blends quantitative market sizing and forward-looking scenarios with actionable diagnostics. Key inclusions:
-
Proprietary market model (2020–2032) with base-year validation: granular topline and scenario runs that allow sensitivity testing of raw-material inflation, mold-capacity lead times, and alternate material adoption curves.
-
Supply‑chain maps and make-vs‑buy decision trees: componentized cost stacks for typical PGM assemblies, bottleneck analysis (tooling, preform supply, AR coatings), and recommended hedging tactics for 12–36 month planning horizons.
-
Commercial playbook: go-to-market options for OEMs, tier‑1 suppliers, and foundries — including sample partnership structures, pricing anchors, and ramp calendars for contract negotiations.
-
Technology & CAPEX primer: comparison of molding equipment classes, expected throughput and yield metrics, and a capital ROI template calibrated to varying production scales.
-
M&A and JV screening: a short‑list of target archetypes, valuation heuristics, and integration checklists tailored for strategic acquirers looking to buy optical capacity or proprietary tooling expertise.
-
Regulatory and material risk matrix: scenario-played impacts of export controls, environmental compliance in key geographies, and transition plans for alternative optical glasses.
Competitive landscape: capabilities that matter
Understanding supplier strengths — not just capacity — is essential. Our competitive diagnostic focuses on three axes: production scale & repeatability, material expertise, and vertical integration of tooling and coatings. Highlights from primary company analysis:
-
Rochester Precision Optics (RPO): Recognized for high-volume asphere production and end-to-end vertical integration (tooling, preforms, centering, AR coatings). Recent strategic financing in early 2025 materially strengthens their capacity and R&D capability — a clear signal that competition for volume contracts will intensify.
-
INGENERIC GmbH: A European center of expertise for micro-optics and complex micro‑lens arrays. Their demonstrated ability to move from prototype to scalable runs is a differentiator for multispectral and multifunctional optics applications.
-
LightPath Technologies: Specialized in chalcogenide glass molding for IR optics and thermal imaging, they exemplify the material‑driven niche players who can capture market share as germanium supply uncertainty persists. Their material qualification focus is strategically synchronous with macro supply risk.
-
Toshiba Machine / Shibaura Machine: These OEMs for glass-molding equipment determine the rhythm of capacity expansion. Machine makers set achievable throughput, tool life, and automation levels — all of which cascade into customer unit economics.
-
Syntec Optics: A smaller, design-to-assembly player that illustrates the integrated service model (design + molding + assembly) some OEMs favor to reduce coordination risk and accelerate module validation.
Technology inflection points and what they mean for your roadmap
Two near-term technology developments will shape supplier economics and product roadmaps in 2026:
-
Advances in mold materials and tooling: Recent academic and industrial work on wafer-scale vitreous carbon molds indicates potential for lower-cost scalable replication of aspheres at wafer throughput — a structural improvement that could meaningfully lower per-unit tooling amortization for certain lens families.
-
Material substitution dynamics: Export-control-driven constraints on traditional IR substrate supply are accelerating qualification of alternative glasses such as chalcogenides. Firms that have early material-qualification pipelines and testbeds reduce product calendar risk and can capture displaced demand.
Practical recommendations for 2026 planning cycles
-
Adopt a two-track sourcing strategy: a core long-term supplier relationship for volume certainty and a secondary agile supply line for material or tooling experimentation. Use 2026 to negotiate multi-year capacity windows tied to volume milestones rather than spot buys.
-
Prioritize tooling IP and process know‑how: If your product roadmap depends on low‑tolerance aspheres or complex freeform elements, consider investment in in‑house mold maintenance capabilities or exclusive tooling arrangements to protect lead times.
-
Scenario‑test material supply shocks: Run a structured stress test of your BOM against a range of raw-material price moves and export-control events. Build a phased material‑substitution matrix with qualification gates aligned to product refresh cycles.
-
Evaluate strategic partnerships with machine OEMs: For companies considering onshore capacity, partnering with machine builders can accelerate automation and shorten industrialization timelines versus a pure greenfield factory build.
-
Embed regulatory monitoring in product development: Regulatory shifts can alter the economics of IR optics overnight. Make policy intelligence a standing input for quarterly product reviews.
Where granular intelligence is intentionally held back — and why
Consistent with our “trailer” principle, this primer surfaces the strategic contours and executable guidance procurement, product, and M&A teams need to start planning now. We have intentionally omitted granular region-by-region or application-specific share tables and detailed segment revenue lines from this public summary. Those data points are included in the full PW Consulting Precision Glass Molding Market report, which contains the actionable segmentation and supplier benchmarking matrix required for tendering, M&A underwriting, and operations planning.
Next steps for executives
-
Request a tailored briefing: Schedule a 45–60 minute workshop with our PGM practice to align market scenarios to your product roadmaps and procurement calendars.
-
Pursue a rapid diagnostic: Commission a 6–8 week diagnostic that maps your product portfolio to PGM readiness, including a cost-to-serve estimate, tooling requirements, and a prioritized supplier shortlist.
-
Consider pre-emptive strategic moves: For OEMs facing short windows to market, early binding commitments with leading PGM partners or targeted minority investments can secure capacity and accelerate time-to-volume.
Precision glass molding is now a strategic lever, not just a manufacturing choice. With market size expanding from the current base and predictable mid-single-digit CAGR dynamics, 2026 is the year to convert market visibility into durable competitive advantage. PW Consulting’s full report equips leaders with the granular segmentation, supplier scorecards, and scenario models necessary to execute with confidence.
Contact PW Consulting to access the full Precision Glass Molding Market report and bespoke advisory engagements tailored for your 2026 strategic planning cycle.
For detailed analysis of this topic, please visit the official page: Precision Glass Molding Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com