

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Holographic Anti-counterfeiting Marks to Reach USD 985M by 2032 at 4.0% CAGR

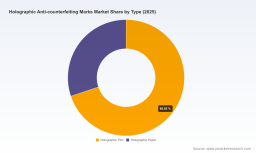
Holographic Anti-counterfeiting Marks Market: Strategic Preview for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present an executive preview of our new Holographic Anti-counterfeiting Marks Market study — a working guide built to inform enterprise strategy in 2026. The study synthesizes a decade of market observation, validated vendor intelligence, regulatory scanning, and techno-commercial scenario planning to equip executives with the frameworks they need to act now and iterate later. Below I summarize the report’s strategic value, the forces reshaping supplier economics, competitive positioning trends, and immediate, executable choices for market participants — while deliberately retaining the report’s proprietary micro-segmentation and model outputs to encourage full access to the primary research.
Holographic Anti-counterfeiting Marks Market
Why this study matters in 2026: the strategic context
Holographic anti-counterfeiting marks remain a core element of visual authentication strategies across regulated goods and high-value consumer products. After steady expansion through the early 2020s, the global market recorded a base-year size of USD 754 million in 2025 and is modeled to continue expanding at a compound annual growth rate (CAGR) of approximately 4.0% through the 2026–2032 forecast horizon. That trajectory reflects a balance of tailwinds — regulatory mandates, brand-protection programs, and incremental technology adoption — against structural headwinds such as raw material cost pressure and the emergence of digital verification alternatives.
Holographic Anti-counterfeiting Marks Market
For 2026 corporate planners, this combination translates into a market that is sizable and predictable, but not explosive; the window for shaping category economics and securing supply arrangements is now. Late movers can still achieve meaningful differentiation, but they will face higher costs and longer lead times if they await market inflection points that may not materialize until later in the decade.
Holographic Anti-counterfeiting Marks Market
What the full report delivers (practical, executable content)
- Market sizing and validated time series (historical 2020–2025, base year 2025) and a scenario-driven forecast (2026–2032) that models regulatory, raw material and technology-risk tails.
- Regulatory and standards matrix that maps requirements (pharmaceuticals, tobacco, high-value packaging) to solution classes and compliance timelines, enabling compliance-first product roadmaps.
- Technology and production segmentation that explains where value accrues — from hologram master origination through replication, metallization and finishing — and an equipment-capex vs. outsourcing decision framework.
- Supplier landscape and concentration analysis, including competitive benchmarking, capability heat maps, and a CR-analysis that clarifies market power dynamics and partner selection criteria.
- Commercial playbooks: procurement levers, total-cost-of-ownership models, licensing and co-development structures, and a prioritized list of pragmatic quick-win pilots for 6–12 month horizons.
- M&A and partnership scouting: identification of strategic tuck-ins, technology licensors and geographic footholds that accelerate market entry or capability build.
- Operational risk and continuity scenarios: raw-material volatility, equipment lead times (notably for laser-based photoresist recording systems), and contingency actions to protect manufacturing continuity.
- Data annex and methodologies: detailed assumptions, model sensitivities, and guidance for tailoring forecasts to bespoke corporate exposures without exposing our full segmentation tables in this preview.
Market structure and competitive dynamics — what to watch
The global supplier base is fragmented but shows meaningful concentration among a cohort of established optical-security specialists and integrated packaging players. Our concentration analysis indicates that the top firms capture a sizeable share of value — a reminder that trusted credentials, master origination capability, and high-security production lines remain barriers to entry. For buyers, this translates into a trade-off between working with a few deep-specialist partners versus a broader set of regional suppliers for cost or service resilience.
Notable vendor archetypes emerging from our research:
- Heritage optical-security manufacturers with proprietary master-origination and embossing technology — these firms lead on security-grade features and high-certainty delivery for banknote- or document-grade projects.
- Regional converters and packaging conglomerates who combine holographic overlays with flexible-packaging services — attractive for CPG brands seeking end-to-end packaging authentication integrated into manufacturing lines.
- Specialist tamper-evident and transactional security vendors focusing on tapes, seals and labels — they command expertise in tamper and void technologies used in regulated goods.
- New entrants and nimble specialist start-ups bringing digital verification layers or niche micro-structure innovations — capable of accelerating proof-of-concept pilots but often lacking scale at launch.
Our vendor review profiles dozens of players; a selection of noteworthy names demonstrates the breadth of capability and routes to market: multi-decade optical-security producers with global reach, regional specialist manufacturers in high-demand markets, and packaging firms that now include holographic security as part of hybrid solutions. Recent industry shifts — including new membership categories and data tools launched by international optical-security associations in 2026 — are lowering the barrier for innovation collaboration and verification tooling, altering partnership calculus.
Regulation, standards and production realities: decisive forces
Three intertwined dynamics are shaping demand and supplier choices in 2026:
- Regulatory mandates: Recent directives require tamper-proof visual indicators for certain prescription medicines and stronger authentication on regulated products. These compliance timelines are a primary driver of near-term procurement and expansion plans for many manufacturers and brands.
- Standards and verification protocols: Industry-grade standards (including guidance aligned with ISO 12931) and association-led verification tools are raising the floor for what counts as an effective optical-security solution, prompting firms to favor certified production paths and traceable master-origination processes.
- Production-critical hardware and master origination: High-security hologram production hinges on specialized equipment — notably laser-based photoresist recording systems and master origination capabilities — which are capital-intensive and have long lead times. Control over these upstream steps materially affects supply security and margin capture.
These forces favor firms that can combine technically robust originations with compliant manufacturing and rapid integration into packaging lines. For buyers, the practical implication is clear: prioritize partners who can demonstrate traceable masters, standards alignment, and audited production processes.
Recent signals from the field (implications for strategy)
- Association-led initiatives in 2026 expanded membership categories and rolled out practitioner tools for document verification, signaling a push toward standardized verification ecosystems. For corporates, this opens opportunities for interoperability and off-the-shelf verification services to accompany holographic marks.
- Market incumbents continue to mark milestones and expand capabilities — reinforcing that reputation and manufacturing pedigree remain market differentiators. Expect increased consolidation pressure among niche producers as larger players seek vertical integration.
- Evidence from manufacturers highlights that hologram master origination and specialized recording hardware remain the single most critical technical levers. Firms that secure capacity and IP in these areas will influence premium pricing and high-security contracts.
Recommendations for 2026 corporate decision-makers (actionable priorities)
Our study translates market intelligence into a six-point action agenda tailored to three corporate archetypes: brand owners, converters/packagers, and technology providers.
- For brand owners (regulated or high-fraud exposure): map your compliance timeline against regional regulatory mandates, secure long-lead procurement slots for certified suppliers, and pilot multi-factor authentication (visual holograms + digital verification) in high-value SKUs. Treat holographic marks as part of a broader authentication stack rather than a standalone artifact.
- For converters and packaging groups: assess the strategic economics of upstream capability — can you justify capital spend for master origination equipment, or will partnership/licensing deliver better returns? Our TCO model in the report helps quantify break-even timelines under alternate demand scenarios.
- For technology providers and investors: focus on micro-nano structure IP, interoperable verification APIs, and scalable replication processes. Target tuck-in acquisitions that add master-origination expertise or unique tamper-evident chemistries to accelerate product-market fit.
- Cross-cutting: formalize supplier risk assessments that incorporate equipment lead times, raw-material exposure, and certification status. Secure service-level agreements that include quality audits, audit trails for masters, and contingency production pathways.
KPIs, timelines and governance
Start with three practical metrics to govern 2026 programs: (1) time-to-deployment for a pilot SKU (target 90–120 days), (2) certified-master traceability coverage across regulated SKUs (target percent depends on portfolio risk), and (3) supplier continuity score that combines capacity, geographic diversity and certification depth. Embed these into quarterly portfolio reviews and tie procurement commitments to staged performance milestones.
Closing: why read the full report
This preview outlines the strategic stakes: a stable mid-sized market growing at roughly 4% annually, a supplier landscape where mastery of origination and certified processes drives differentiation, and a regulatory/standards backdrop accelerating commercial adoption. The full PW Consulting report contains the operational models, vendor scorecards, regulatory timelines, and executable negotiation playbooks you need to turn this strategic context into near-term wins. We intentionally reserve the segment-level data and granular vendor scoring for the full publication — precisely because those are the elements that power transactional advantage.
For organizations preparing procurement roadmaps, R&D investments, or M&A screens in 2026, this study is designed to be the single reference that converts market signals into disciplined commercial action. PW Consulting is ready to brief your leadership team with a tailored session that maps these insights directly onto your exposure and objectives.
For detailed analysis of this topic, please visit the official page: Holographic Anti-counterfeiting Marks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com