

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: HF Acid Market to Reach USD 4,405 Million by 2032 at 5.15% CAGR

Hydrofluoric Acid Market 2026: Strategic Primer for Executive Decision-Making
As companies plan capital allocation and supply-chain strategy for 2026, hydrofluoric acid (HF) is resurfacing as a material strategic risk and commercial opportunity. PW Consulting’s latest market study — grounded in a 2020–2025 historical series and a 2026–2032 forecast — synthesizes the demand drivers, supply-side shocks, regulatory inflection points and competitive positions that will determine winners and losers in the HF value chain. This primer distills the report’s highest-value insights to inform board-level discussions, while intentionally withholding detailed segment tables and plant-level exposures that are included in the full research deliverable.
Hydro Fluoric Acid Market
Market trajectory at a glance
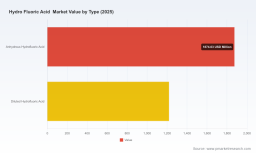
Our base-year snapshot (2025) shows a global HF market approximately USD 3,093 million (USD Million, base year 2025), following steady expansion from about USD 2,500 million in 2020. Momentum into 2026 projects a market exceeding USD 3,240 million, with an expected compound annual growth rate (CAGR) of roughly 5.15% through 2032, when the market is modeled to surpass USD 4,400 million. The near-term acceleration reflects recovery and reinvestment across fluorochemicals, specialty refrigerants and industrial applications; the longer-term curve is driven by electronics demand, material substitution, and evolving environmental constraints.
Hydro Fluoric Acid Market
Why HF matters for 2026 corporate strategy
- Feedstock criticality: HF is not a generic commodity — it is a feedstock for fluorochemicals, specialty refrigerants, aluminum processing and electronics manufacturing. Short-term availability or quality disruptions ripple rapidly through downstream product lines.
- Concentrated supply base: Industry concentration means a small group of producers exerts meaningful influence over accessible supply and pricing. A focused commercial strategy — with contingency for supplier risk — is therefore non-negotiable.
- Regulatory and social license risk: Emerging regulatory actions and public-health scrutiny are elevating operational and reputational risk for producers and users alike.
Supply and raw-material dynamics shaping 2026
Two linked upstream dynamics are especially material. First, fluorspar — the primary source of fluorine inputs — experienced a modest global production contraction in 2025. Second, import/export flows have shifted meaningfully in recent quarters: certain markets have seen sharp increases in imports amid local mining disruptions and safety-driven rectification. These dynamics collectively compress the short-term buffer that typically cushions HF production, making import dependencies and logistics resilience critical inputs to procurement strategy.
Hydro Fluoric Acid Market
For North American buyers, recent trade flows underscore exposure concentration: a dominant share of HF imports originated from a single neighboring supplier market in late 2025. That pattern creates a vulnerability to trade-policy shifts, route-specific logistics incidents and seasonal demand spikes.
Regulation and public policy — immediate watchpoints
- State-level product rules and toxic-substances lists have moved to the center of HF risk. A prominent U.S. state agency initiated rulemaking in mid-2026 to designate cleaning products containing HF as a priority product — a development with potential downstream implications for formulators and distributors.
- Parallel to product-level action, several producers are undertaking capacity rationalization or site exits as part of corporate restructuring. These closures tighten available global HF capacity and require buyers to reassess contracted volumes and alternate sources.
- Environmental health scrutiny and emergency-response obligations are growing. For producers, enhanced community engagement, capital earmarked for containment and emergency preparedness will increasingly be treated as cost of doing business.
Competitive landscape — what the major players reveal
The HF market is served by a mix of global integrators, regional specialists and niche suppliers. Leading players combine feedstock integration with downstream fluorochemical platforms; others focus on aqueous blends and specialty grades for industrial customers. Key strategic profiles to consider:
- Large integrated producers: Global chemical majors operate high-capacity plants that supply both anhydrous and aqueous HF grades and feed integrated fluorochemical chains. Their strategic advantage is operational scale and the ability to prioritize internal feedstock flows.
- Regional high-purity specialists: Certain Asian and European producers distinguish themselves through high-purity product lines tailored to electronics and specialty etching applications, supported by localized technical service and just-in-time logistics.
- Aqueous and customized-blend suppliers: Regional distributors and manufacturers provide tailored aqueous concentrations and localized supply, emphasizing safety compliance and shorter lead times for industrial markets.
Understanding each supplier’s commercial priorities — export orientation, captive downstream demand, and willingness to supply third parties under spot or contract terms — is critical to shaping procurement strategies and negotiating resilient contracts.
Recent industry events that should change your 2026 plans
- A regulatory initiative in mid-2026 to list certain HF-containing consumer cleaning products as priority items highlights how state-level actions can cascade into commercial restrictions and heightened compliance costs for formulators and retailers.
- Corporate restructuring and site exits announced in the past 12–18 months will remove optionality in specific corridors, necessitating earlier and more diversified sourcing decisions for buyers.
- Industry thought leadership by regional suppliers on trust and domestic-supply advantages underscores an emergent commercial narrative: buyers are increasingly willing to trade unit-cost savings for supply assurance and regulatory alignment.
Strategic implications and recommended actions for 2026
Time horizon matters. Actions that reduce risk in the next 12 months differ from those that create advantage across the 2026–2032 forecast period.
- Near-term (0–12 months): Secure rolling contracts with dual-sourced supply clauses, institute inventory-buffer optimization tied to scenario-based stress tests, and renegotiate freight terms to protect against route-specific shocks. Prioritize suppliers with demonstrable contingency plans and transparent quality systems.
- Medium-term (12–36 months): Evaluate co-investment in local blending or small-scale production to reduce import exposure; incorporate supplier scorecards that weight regulatory resilience and community acceptance; and audit downstream conversion processes to optimize HF consumption efficiency.
- Strategic portfolio decisions (36+ months): Consider partnerships or M&A to secure upstream fluorspar access or HF production capacity, and develop differentiated product offerings based on high-purity or low-environmental-impact credentials aligned with decarbonization and substitution trends.
Operational playbook highlights included in the full report
To support executable decisions, our full study contains granular tools and templates oriented to procurement, operations and corporate strategy teams. These include:
- Supply-risk heatmaps and supplier scorecards (including operational, regulatory and reputational dimensions).
- Scenario-based supply-demand models and price path simulations for 2026–2032.
- Contract playbooks with recommended clauses for force majeure, diversion rights, and environmental compliance pass-through.
- Plant-level risk assessments and emergency-response benchmarking templates.
- M&A screening criteria for upstream feedstock and downstream integration opportunities.
Each tool is calibrated to the market’s expected growth trajectory and to contemporary regulatory pressures. The full report also includes an annex of company profiles and links to primary sources used in our analysis.
How to think about commercial negotiation in 2026
Market tightening and regulatory uncertainty mean price will not be the only leverage in negotiations. Buyers should shift to a total-cost-of-supply framework that captures inventory carrying costs, regulatory compliance expenses, logistics risk premiums and the cost of potential supply restoration. Contract structures that combine volume-flexibility, pre-agreed escalation mechanics and operational transparency (e.g., supplier audits, third-party monitoring) will outperform spot-only strategies in both cost and continuity.
What PW Consulting’s research delivers (and what we intentionally withhold here)
We designed this study to be immediately actionable for executives. The report provides:
- Validated historical market sizing (2020–2025) and a detailed forecast model (2026–2032) with scenario outputs.
- Plant-level exposure matrices, regional flow maps, and application demand curves for downstream sectors.
- Competitive intelligence dossiers on leading suppliers, including strategic intent indicators and likely response scenarios to supply shocks.
- Regulatory and raw-material monitoring dashboards that flag rulemaking, trade-flow shifts and mine production notices.
- A prioritized list of tactical and strategic initiatives tailored to buyer, producer and investor profiles.
To preserve the commercial value of the study and to respect proprietary supplier data, this primer omits full regional and application splits, plant-level capacities and specific contractual language — all of which are available in the subscription report and accompanying datasets.
Immediate next steps for executive teams
- Run a 30–60 day rapid diagnostic using the report’s supplier scorecard to identify single-source exposures and critical-path dependencies.
- Convene a multi-disciplinary steering committee (procurement, operations, HSE, legal) to stress-test existing contracts against the regulatory scenarios highlighted in this study.
- Prioritize small-scale resilience investments — alternate blending capability, buffer inventory, and logistics redundancies — that can be executed within a single budget cycle.
The hydrofluoric acid market is entering a period where strategic foresight, not short-term spot savings, will determine operational continuity and margin stability. PW Consulting’s full study equips decision-makers with the data, scenarios and playbooks to make those calls confidently in 2026.
Accessing the full intelligence
If your 2026 planning cycle requires the detailed tables, regional and application breakdowns, plant-level risk heatmaps and supplier scorecards referenced above, we invite you to consult the complete Hydrofluoric Acid Market report on our website or contact PW Consulting for a briefing. The full dataset contains the granular numbers and scenario models necessary to translate the strategic imperatives summarized here into executable plans.
For detailed analysis of this topic, please visit the official page: Hydro Fluoric Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com