

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Microcrystalline Wax Market to Hit USD 1,934 Million by 2032 at 4.15% CAGR

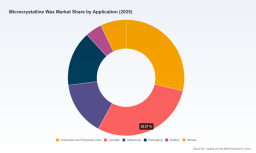
Microcrystalline Wax Market — 2026 Strategic Preview
Executive snapshot
As PW Consulting’s lead industry analyst, I present a strategic preview of the Microcrystalline Wax market designed to inform high-consequence decisions in 2026. The market is transitioning from a post‑pandemic recovery phase into a structurally reshaped environment driven by feedstock volatility, tightening trade regimes, and a sustainability‑centred product race. On a macro basis, the market was valued at approximately USD 1,425 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of about 4.15% through our forecast horizon, arriving near USD 1,934 Million by 2032. Concentration metrics indicate a moderately consolidated supply base, with the top three and top five players accounting for a meaningful share of industry supply — a dynamic that amplifies the impact of strategic moves by incumbents.
Microcrystalline Wax Market
Why this briefing matters for 2026 decision-makers
-
Time-sensitive regulatory changes and trade actions in 2025–2026 have altered risk profiles for sourcing and market access. Procurement, legal, and commercial teams must re-evaluate supplier exposure and customs duty scenarios now, not later.
Microcrystalline Wax Market -
Feedstock price shocks and logistics dislocations have compressed margins for downstream formulators; our actionable scenarios enable CFOs and sourcing leads to model hedging, pass‑through, and inventory strategies under realistic stress cases.
Microcrystalline Wax Market -
Product and sustainability differentiation is becoming commercially meaningful: suppliers with low‑PCF (Product Carbon Footprint) grades and micronized offerings are securing faster adoption in coatings, cosmetics, and specialty applications. R&D and commercial leaders require a prioritized playbook for portfolio moves and customer segmentation to capture premium value.
Market snapshot and trajectory
Our consolidated market model shows steady expansion from the 2020 base through 2025 and a continuation of growth across the 2026–2032 forecast window. While headline CAGR is modest, the path to that average is uneven: short windows of price appreciation and periodic demand shifts create tactical windows for margin capture as well as downside risk. The market’s CR3 and CR5 concentration ratios confirm that strategic moves by a handful of large refiners and specialty producers materially influence pricing, availability, and service levels for downstream customers.
Key demand and supply dynamics (high-level)
-
Demand drivers: end‑use innovation in adhesives, packaging, and personal care continues to expand total addressable demand, while premiumization (high‑purity and low‑PCF grades) is carving out faster‑growing subsegments.
-
Supply constraints and cost pressure: crude benchmarks and refinery throughput constraints have pushed feedstock costs higher; the sector saw average price increases in early 2026 driven by those input costs. Logistics and intermediate feedstock availability remain sensitive to regional conflicts and refinery maintenance cycles.
-
Trade and regulatory friction: recent import restrictions and targeted trade measures have raised the cost and complexity of cross‑border flows for mineral waxes, requiring commercial teams to bake tariff and compliance contingencies into annual planning.
Regulatory and trade environment — immediate implications
Three developments in 2025–2026 materially changed the operating envelope:
-
Targeted import restrictions implemented by select jurisdictions have explicitly named mineral waxes — this raises compliance overhead for importers and encourages near‑sourcing where possible.
-
U.S. trade actions in early 2026 expanded forced‑labor import bans and proposed ad valorem duties affecting mineral waxes, increasing the cost of certain supply corridors and elevating supplier vetting requirements.
-
Harmonized Tariff Schedule entries and per‑weight duties (as applied in certain markets) introduce a predictable but non‑negligible incremental cost that procurement teams must include when comparing landed costs across suppliers.
For executives, the immediate takeaways are threefold: (1) revalidate supplier compliance and traceability, (2) quantify landed‑cost sensitivity to tariff and duty scenarios, and (3) build contingency sourcing and inventory options into 2026 operating plans.
Competitive landscape — who moves markets
The competitive axis is split between large integrated petrochemical majors and focused specialty wax houses. Each class of player brings different levers:
-
Global majors: offer scale, broad geographic reach, and capacity flexibility. Example: a major integrated energy company markets a branded microcrystalline portfolio spanning fully refined to semi‑refined grades for packaging, adhesives, construction, personal care, and rubber — enabling one‑stop supply contracts for multinational formulators.
-
Specialty and regional players: focus on FDA‑compliant grades, niche delivery formats (granules, pellets, slabs, liquid blends), and closer customer service for industries such as cosmetics and food‑grade packaging. Their agility is an advantage in tailored formulations and speed to market.
-
Technology‑ and sustainability‑focused suppliers: have begun to commercialize micronized and lower‑PCF grades, attracting customers targeting lower Scope 3 footprints in coatings, inks, and plastics.
Notable company moves in 2024–2026 — product launches at the top end of the market and portfolio expansions at specialty houses — underscore the bifurcation between scale and specialty. Recent activity includes the introduction of high‑purity microcrystalline lines by a major integrated producer and expanded micronized low‑PCF grades by a leading chemical company, both of which materially affect competitive dynamics and customer sourcing choices.
Recent developments that reshape near‑term strategy
-
Product innovations: suppliers launched new high‑purity and micronized microcrystalline wax grades with demonstrably lower product carbon footprints — these products command strategic attention from formulators seeking downstream sustainability claims.
-
Trade measures and customs updates: amendments to certain countries’ trade controls and tariff headings now explicitly include mineral waxes, prompting immediate reassessment of import protocols.
-
Feedstock and geopolitical shocks: conflict‑related disruptions to regional feedstock flows have increased volatility in naphtha, LPG and natural gas derivatives, translating to raw material cost swings for wax producers.
What PW Consulting’s full report delivers (practical and actionable)
Our full market study is built for practitioners who must translate analysis into P&L outcomes. Highlights include:
-
Transparent financial model: scenario‑based revenue and price modeling (base, upside, and stress cases) with configurable inputs for feedstock cost, tariff exposure, and contract pass‑through assumptions.
-
Supply‑chain mapping and risk heatmap: validated supplier lists, logistics corridors, and single‑point‑of‑failure nodes with mitigation playbooks (dual sourcing, forward inventory, tolling options).
-
Commercial playbooks: pricing playbooks for premium vs. commoditized grades, route‑to‑market options for new product introductions, and customer segmentation matrices keyed to margin expansion opportunities.
-
Regulatory compliance matrix and customs impact module: jurisdictional rules, likely duty outcomes under multiple scenarios, and a checklist for import compliance and due‑diligence documentation.
-
M&A and partnership screen: prioritized target shortlist and valuation sensitivity framework for buyers seeking capacity, specialty grades, or regional footholds.
-
R&D and sustainability roadmap: comparative analysis of low‑PCF approaches, micronization economics, and likely adoption curves across end industries.
Each section includes raw datasets, supplier scorecards, and model templates that executives can adapt directly into procurement negotiation decks, strategic plans, and board papers.
Strategic imperatives for 2026
-
Operationalize traceability now: integrate supplier audits, chain‑of‑custody data, and customs compliance into quarterly procurement KPI targets to avoid near‑term trade disruptions.
-
Segment product strategy by value capture rather than volume alone: prioritize commercialization of lower‑PCF and high‑purity grades where customers will pay a premium.
-
Stress‑test supply and pricing with live scenarios: use the report’s financial model to quantify margin outcomes across tariff, feedstock, and demand shock permutations and set trigger points for hedging/stocking.
-
Pursue targeted partnerships and bolt‑on acquisitions: identify specialty producers that accelerate access to regulated or premium end markets, rather than broad, undifferentiated capacity buys.
-
Embed regulatory intelligence into commercial planning: anticipate further tightening of forced‑labour and import regimes; build compliance costs into long‑term supplier contracts.
How PW Consulting’s insights turn into competitive advantage
In 2026, the winners will be companies that translate market intelligence into operational change quickly. That means converting scenario outputs into procurement contracts, turning supplier scorecards into preferred‑supplier programs, and aligning R&D roadmaps with the commercial appetite for low‑PCF grades. Our market model and tactical playbooks are designed to move teams from insight to action within 30–90 days.
Next steps
This preview illustrates the strategic contours and immediate levers for executives in 2026. The full Microcrystalline Wax Market report contains the detailed datasets, proprietary supplier scoring, and executable templates that underpin the recommendations summarized above. For teams preparing budget cycles, sourcing strategies, or M&A screens this year, our analysis provides a plug‑and‑play foundation. Contact PW Consulting to access the complete dataset, bespoke scenario runs, and an executive briefing tailored to your company’s exposure.
For detailed analysis of this topic, please visit the official page: Microcrystalline Wax Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com