

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Fabric Reinforcement Rubber Diaphragm Market set to grow at 5.6% CAGR (2026-2032)

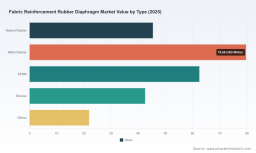
Fabric Reinforcement Rubber Diaphragm Market — Strategic Imperatives for 2026 Decision-Making
As PW Consulting’s lead industry analyst, I present a focused preview of our comprehensive Fabric Reinforcement Rubber Diaphragm Market study — a briefing designed to arm executive teams with the strategic line-of-sight required for confident 2026 planning. This article synthesizes the report’s macro trajectory, regulatory and technology dynamics, competitive architecture, and the practical diagnostic modules that deliver immediate commercial value. It deliberately showcases analytical depth while withholding granular segment-by-segment figures to drive stakeholders to the full research package for transaction-ready detail.
Fabric Reinforcement Rubber Diaphragm Market
Why this market matters for 2026
The fabric-reinforced rubber diaphragm market is no longer a narrowly technical niche: it sits at the intersection of infrastructure modernization, emissions regulation, and high-reliability applications across automotive, aerospace, industrial, and energy sectors. Our bottom-up sizing shows steady expansion from a 2020 base through to 2025, and the outlook through 2032 reflects sustained growth driven by both replacement cycles and new-build demand in pneumatic actuation, precision regulators, and high-integrity sealing systems.
Fabric Reinforcement Rubber Diaphragm Market
-
Historical trajectory: the global market advanced meaningfully between 2020 and 2025 (base year 2025), reflecting recovery in capital equipment and rising specification complexity in regulated end-markets.
Fabric Reinforcement Rubber Diaphragm Market -
Forecast envelope: with a 2026–2032 compound annual growth rate (CAGR) of 5.6%, the market is projected to expand materially by the end of the forecast window — a profile that supports strategic investment but rewards disciplined prioritization.
-
Practical implication: for procurement, R&D and corporate development teams, the mid-single-digit CAGR signals a market where category consolidation, product premiumization, and specification-driven premium segments will deliver disproportionate margin capture.
What executives need to know — high-level takeaways
-
Demand composition is shifting from purely cost-driven procurement toward performance- and compliance-driven selection. Regulatory drivers (e.g., fugitive emissions control in oil & gas, aerospace fatigue-life mandates, and ISO/ASME conformity requirements) are elevating the value of certified, fabric-reinforced diaphragm solutions.
-
Materials and reinforcement decisions increasingly determine total cost of ownership (TCO). Compound choice (notably EPDM in many applications) and reinforcement architecture are the primary levers that reconcile longevity, chemical compatibility, and cycle-life under dynamic loading.
-
Infrastructure spending in developed markets is a near-term demand tailwind for pneumatic actuator retrofits and new valve installations — an important source of volume lift that also creates opportunities for aftermarket differentiation.
-
Fragmented supply structure: concentration metrics show the top suppliers collectively hold a modest share of market volume, pointing to substantial white space for fast-movers that combine engineering differentiation with scale-up capabilities.
Report contents — what the PW Consulting study delivers
Our full report is structured to convert insight into action. Highlights include:
-
Market sizing and trend analysis (base year 2025, historical 2020–2025, forecast 2026–2032), with demand scenarios, sensitivity testing, and upside/downside cases tied to macro drivers and regulation shifts.
-
Commercial segmentation frameworks and applied use-case economics — enabling price vs. performance trade-offs, end-user TCO models, and specification-driven willingness-to-pay matrices.
-
Supplier benchmarking and capability maps that go beyond logos — assessing engineering depth, testing & certification capacities, manufacturing scale, geographic footprint, and OEM qualification status.
-
Raw material and input-cost analysis, including compound availability dynamics and supply chain risk heatmaps — essential for procurement to lock in margins and for product teams to optimize formulations.
-
Regulatory and standards catalogue: a concise compliance playbook aligned to ISO, ASME, and sector-specific mandates (oil & gas fugitive emission rules; aerospace fatigue-life certification pathways).
-
Go-to-market playbooks and commercial KPIs for market entry, aftermarket expansion, and OEM partnership strategies — complete with product localization checklists and pricing matrices.
-
M&A and partnership screening filters — a prioritized list of capability targets, earnout architectures, and integration risk profiles to accelerate inorganic growth.
-
Implementation roadmaps: 90/180/365 day action plans for product development, certification programs, and channel expansion calibrated to investment appetite and risk tolerance.
Market dynamics and segmentation (directional)
Rather than reproducing every cell from the segmentation tables, the report adds actionable interpretation: materials (natural rubbers, nitrile, EPDM, silicone and specialty elastomers) play differentiated roles across end-uses; device type and reinforcement weave determine fatigue life and chemical resistance; and application context (from automotive actuation to medical fluid systems) dictates testing and traceability requirements. Notably, EPDM compounds have emerged as a dominant production choice in many applications because of their broad chemical compatibility and favorable temperature envelope — an important design consideration for anyone specifying diaphragms today.
We also map how infrastructure spending patterns and sector-specific regulations are changing the mix of new-build versus retrofit demand. This directional segmentation enables clients to prioritize which product development bets and supply-chain investments will generate the highest return through 2026 and beyond.
Competitive landscape — who matters and why
The market features a mix of global engineering brands, specialized elastomer houses, and regional volume producers. Key players profiled in the study include global engineering leaders that supply certified, high-integrity diaphragms for regulated sectors, as well as specialist manufacturers that focus on specific applications such as irrigation, process sealing, or medical fluidics. The report’s supplier dossiers provide:
-
Strategic profiles and go-to-market models for the principal firms.
-
Capability audits (materials expertise, testing labs, OEM approvals).
-
Commercial posture analysis (OEM focus vs. aftermarket, custom tooling capabilities, contract manufacturing readiness).
For commercial planning, the critical insight is that the market’s top firms — while widely recognized for technological leadership — do not yet command overwhelmingly dominant share. This creates windows for strategically differentiated entrants to win OEM-qualified positions or to vertically integrate into adjacent supply chains.
Technology, regulation and procurement implications
Three converging forces will shape supplier economics and procurement strategies through 2026:
-
Regulatory tightening: fugitive-emission controls and aerospace/defense fatigue-life specifications raise the floor for diaphragm performance. Suppliers lacking robust certification programs will face limited access to high-value projects.
-
Materials engineering: compound selection and reinforcement architecture are the primary mechanisms to extend life under cyclic loading and aggressive chemistries. Clients should re-evaluate legacy bill-of-materials for mission-critical applications, prioritizing TCO over unit cost alone.
-
Supply resilience: near-term raw-material availability and regional manufacturing capacity matter for lead times and cost volatility. Procurement teams must integrate long-lead raw-material risk into reorder strategies and qualification timelines.
Recommended actions for 2026 planning
-
Prioritize certification-led product upgrades where regulations create differentiated value. A targeted investment in test-lab capacity and third-party certification can unlock premium contract channels.
-
Use TCO models in procurement negotiations. Buying on lowest unit price alone exposes operators to replacement and downtime costs that exceed material premium.
-
Seek strategic OEM partnerships and co-development arrangements to embed specification requirements early — moving from vendor to innovation partner reduces switching risk.
-
Evaluate bolt-on acquisitions that provide either specialty materials expertise or OEM qualifications that are costly to build organically within certification timelines.
Risk framing and monitoring
The report includes a concise risk matrix tying probability and business impact to the primary threats: regulatory shifts, raw material supply shocks, certification delays, and competitive pricing pressure from unqualified low-cost producers. For each risk we propose monitoring triggers and mitigating tactics — for example, dual-sourcing strategies, hedged raw-material contracts, and staged certification milestones linked to customer acceptance criteria.
Next steps — where to get the full intelligence
This article is a strategic preview intended to surface the most consequential insights for 2026 decision cycles. The full PW Consulting study contains the granular segmentation, detailed supplier scorecards, downloadable financial models, and executable 90/180/365 day playbooks required to act decisively. For teams charged with procurement optimization, product roadmapping, or M&A scouting in this space, the report converts market momentum into a practical program.
Access the complete market intelligence and the datasets that underpin our forecasts through the PW Consulting portal — the exact segmentation tables, pricing ladders, and supplier benchmarking matrices are available there to support your strategic and transaction workstreams.
For detailed analysis of this topic, please visit the official page: Fabric Reinforcement Rubber Diaphragm Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com