
Blogs
PW Consulting: Powder Coatings Market Hits $17.00B in 2025, Poised for 6.73% CAGR Growth Through 2032
By pmarketresearch, 2026-09-15
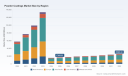
Powering Durability: Strategic Insights into the Powder Coatings Market Through 2032
Executive Overview
The global powder coatings market stands at a critical inflection point. As industries transition toward sustainable manufacturing and stricter environmental compliance, powder coatings have emerged as a cornerstone technology for protective and decorative finishes. Our latest market research provides a comprehensive roadmap for navigating the period from 2026 through 2032, offering decision-makers the granular intelligence required to align capacity planning, supply chain strategy, and product development with evolving demand patterns.
Built on a foundation of historical analysis spanning 2020 to 2025, this study projects market trajectories with a compound annual growth rate of 6.73 percent. The forecast period captures the structural shifts that will define competitive advantage over the next seven years, from regulatory-driven substitution trends to the realignment of regional production networks. This preview outlines the strategic framework of the report and the actionable insights it delivers to executives, procurement leaders, and R&D directors.
Market Trajectory and Growth Dynamics
The market has experienced a pronounced expansion phase over the past half-decade, with revenue figures climbing from approximately 57.7 billion USD in 2020 to an estimated 17.0 billion USD by 2025 when measured against the report's standardized valuation framework. This growth trajectory reflects sustained investment in industrial finishing, architectural applications, and automotive component protection, alongside a broader industry shift away from solvent-based systems.
Looking ahead to the 2026-2032 window, the market is positioned to surpass 25.5 billion USD by the terminal forecast year. The 6.73 percent CAGR projected for this period is not merely a statistical projection; it represents the cumulative effect of several reinforcing forces:
- Accelerating adoption of powder coatings in sectors historically dominated by liquid systems, driven by volatile organic compound (VOC) restrictions and carbon-neutrality mandates.
- Rising demand for high-performance, weather-resistant formulations in architectural and infrastructure projects across both developed and emerging economies.
- Expanding appliance and furniture manufacturing capacity, particularly in regions where export-oriented production is scaling with localized finishing requirements.
- Investment in bio-based and recycled-content coating formulations as original equipment manufacturers pursue Scope 3 emission reductions.
The report dissects these drivers with sector-specific depth, mapping how each application vertical is expected to contribute to overall revenue expansion. Rather than presenting undifferentiated growth figures, the analysis isolates the structural factors that will differentiate high-growth segments from those facing margin compression or substitution risk.
Coil Coatings Market
Segmentation Analysis: Where Value Is Created
Understanding the market requires more than top-line projections. The research provides a multi-dimensional segmentation framework that examines type, application, and regional distribution with surgical precision. This approach enables stakeholders to identify which product categories and end-use markets offer the most favorable risk-reward profiles in the current pricing environment.
Type Segmentation
The market is fundamentally divided between thermoset and thermoplastic powder coatings, each serving distinct performance requirements and cost structures. Thermoset formulations continue to command a dominant share of the revenue base, reflecting their superior cross-linking properties, chemical resistance, and widespread adoption in automotive, appliance, and architectural finishing. Thermoplastic options, while representing a smaller share, are gaining traction in applications where recyclability, remeltability, and specific mechanical properties are prioritized.
The report provides a detailed comparison of resin chemistry adoption trends, curing energy requirements, and performance benchmarks across these categories. It also evaluates the pricing dynamics that distinguish premium high-solids formulations from commodity-grade offerings, giving procurement teams the context needed to negotiate supplier contracts with confidence.
Application Segmentation
Demand is distributed across a diverse set of industrial and consumer end-markets. Automotive applications represent a substantial share of total consumption, driven by the need for durable, corrosion-resistant finishes on both structural components and decorative surfaces. Appliances follow closely, with powder coatings increasingly specified for indoor and outdoor units where aesthetic consistency and long-term durability are non-negotiable.
Architecture and construction equipment form another significant demand cluster, particularly in regions where infrastructure investment and urban development programs are accelerating. Furniture manufacturing, general industrial finishing, and a broad "others" category encompassing specialized niche applications round out the consumption picture.
Crucially, the report does not treat these segments as static buckets. It tracks how application mix is shifting in response to:
- Regulatory pressure on solvent-based coatings in consumer-facing product categories.
- Supplier-led innovation in low-temperature cure formulations that expand the addressable market for heat-sensitive substrates.
- Shifts in global manufacturing footprints, with finished goods production migrating toward regions that impose stricter environmental standards on coating processes.
Regional Distribution
The global demand landscape is geographically diverse, with significant concentration in Asia Pacific, Europe, and North America. Asia Pacific leads in volumetric terms, reflecting the region's manufacturing intensity across automotive, appliances, architecture, and general industrial sectors. Europe's market is characterized by high value-add per unit, driven by stringent regulatory frameworks and a mature architectural and infrastructure coating sector. North America maintains a robust industrial base, with strong demand from construction equipment, furniture, and appliance manufacturing.
Latin America and the Middle East & Africa represent emerging growth vectors, though at smaller absolute scales. The report maps regional growth rates, regulatory timelines, and supply chain infrastructure maturity for each territory, enabling multinational operators to prioritize market entry or capacity expansion with data-backed confidence.
Powder Coatings Market
Competitive Landscape and Strategic Positioning
The powder coatings market is characterized by a moderately concentrated competitive structure, with the top three players commanding approximately 35.2 percent of total revenue and the top five accounting for roughly 45.3 percent. This concentration level indicates a market where scale advantages, formulation IP, and customer relationships create meaningful barriers to entry, but where regional specialists and niche innovators can still secure profitable positions through differentiated offerings.
Key Incumbents and Strategic Profiles
Several global and regional players define the current competitive architecture:
- Axalta Coating Systems , headquartered in Philadelphia, operates the Alesta brand and has built a reputation in automotive and industrial applications, with a growing portfolio of bio-based options that align with OEM sustainability targets.
- PPG Industries , based in Pittsburgh, produces the EnviroLuxe and EnviroCaron product lines, emphasizing recycled content and PFAS-free formulations that respond directly to evolving regulatory and customer preferences.
- BASF SE , from Ludwigshafen, serves as a critical upstream supplier of resins and additives, including neopentylglycol used in powder coating formulations, positioning the company at the intersection of raw material supply and end-product performance.
- The Sherwin-Williams Company , in Cleveland, markets powder coatings under its own brand, leveraging a broad distribution network and integrated customer relationships across industrial and architectural segments.
- Jotun , headquartered in Asker, Norway, operates as a global producer of protective and decorative powder coatings with a strong presence in marine, infrastructure, and industrial markets.
- Kansai Paint Co., Ltd. , in Osaka, specializes in industrial powder coatings under its Kansai Powder Coatings banner, serving Asian manufacturing sectors with regionally tailored formulations.
- American Powder Coatings Inc. , a U.S.-based manufacturer, focuses on industrial and architectural applications, catering to domestic demand with specialized service and custom formulation capabilities.
- Nippon Paint Holdings Co., Ltd. , also based in Osaka, produces decorative and industrial powder coatings, extending the company's broader coatings portfolio into powder-based finishing systems.
- Teknos Group Oy , from Espoo, Finland, provides waterborne and solvent-free powder coating systems, aligning product development with the broader industry transition toward lower environmental impact.
- Tiger Coatings GmbH and Co. KG , in Vienna, specializes in high-performance powder coatings for architectural and industrial use, competing on quality, durability, and application-specific engineering.
Competitive Dynamics and Recent Developments
The competitive environment is not static. Recent developments in April 2026 illustrate the pricing and supply chain pressures that are reshaping margin structures across the value chain:
- PPG Industries announced a global price increase of up to 20 percent across its paints, coatings, and specialty products portfolio, citing rising raw materials, logistics, energy, and packaging costs.
- BASF SE implemented a price increase for NEOL (neopentylglycol) in the United States and Canada across all grades and packaging, effective April 15 or as existing contracts permit, due to further increases in logistics and raw material feedstock costs.
- BASF SE also introduced a further price increase of up to 25 percent for antioxidants, process stabilizers, and light stabilizers used in plastic applications, effective immediately, in response to raw material prices, energy, and logistics costs.
These moves reflect a broader pattern of cost pass-through in an environment where epoxy resin prices have been on the upswing and geopolitical conflicts have triggered raw material price surges. Industry data indicates that powder coating prices averaged between 3.00 and 6.50 USD per pound in 2025, depending on resin type, performance specifications, and end-use industry, underscoring the price dispersion that procurement teams must navigate.
The report quantifies how these cost pressures propagate through the value chain, identifies which players have the pricing power to absorb or pass on increases, and evaluates the substitution risks that arise when end-users face disproportionate cost burdens.
Regulatory and Environmental Catalysts
Regulatory frameworks are no longer peripheral concerns; they are central drivers of market structure. Stringent EU VOC and carbon-neutrality regulations are accelerating the adoption of solvent-free powder coatings as the best available technique under the Industrial Emissions Directive. This regulatory tailwind is expanding the addressable market for powder-based systems while simultaneously raising performance and compliance expectations for formulators.
The report maps regulatory timelines across major jurisdictions, identifies the specific compliance requirements that affect formulation choices, and evaluates the cost implications of regulatory adaptation for both incumbents and new entrants. It also examines how carbon accountability frameworks, including Scope 3 reporting obligations, are influencing material selection decisions among large industrial customers.
Supply Chain Resilience and Raw Material Exposure
The powder coatings value chain is exposed to volatility in resin pricing, energy costs, and logistics networks. Epoxy resin prices have experienced significant upward pressure, and geopolitical disruptions have driven raw material cost surges in certain regions, with epoxy resin increases of 7,000 to 8,000 RMB per ton documented in industry data. These cost dynamics create a challenging environment for manufacturers that lack vertical integration or diversified sourcing strategies.
Our analysis provides a structured assessment of raw material exposure by formulation type, geographic supply base, and customer concentration. It identifies which cost categories represent the largest margin risks and which procurement strategies offer the greatest mitigation potential. The report also tracks supplier pricing behavior and contract structures to help buyers anticipate adjustment cycles and negotiate more effectively.
What the Full Report Delivers
This preview captures the strategic architecture of the study, but the full report contains the operational detail required to turn insight into execution. Subscribers gain access to:
- Granular segmentation data across type, application, and region, including revenue splits, growth rates, and market share trajectories for each sub-segment.
- Company-level competitive profiles with product portfolio assessments, regional presence, recent strategic moves, and positioning analysis.
- Regulatory impact assessments that translate compliance requirements into commercial implications for specific market segments.
- Raw material cost tracking and sensitivity analysis, enabling scenario planning for resin, additive, and logistics cost fluctuations.
- Strategic recommendations for capacity investment, supplier selection, formulation development, and market entry or expansion.
- Forecast models that allow users to test assumptions around regulatory adoption speed, raw material price paths, and regional demand shifts.
The report is designed for executives who need to move beyond high-level trend narratives and into the specifics that drive capital allocation, operating plan development, and competitive response. Every dataset is contextualized within the broader market dynamics, ensuring that readers understand not just what the numbers are, but what they mean for decision-making in 2026 and beyond.
Strategic Imperatives for 2026 and Beyond
As the market moves through its next growth cycle, several strategic imperatives emerge for industry participants:
- Align product development with regulatory momentum, particularly in regions where VOC restrictions and carbon accountability frameworks are tightening fastest.
- Build pricing resilience through diversified sourcing, long-term supplier agreements, and formulation flexibility that allows cost optimization without sacrificing performance.
- Invest in bio-based and recycled-content offerings where customer sustainability commitments create willingness to pay for differentiated products.
- Evaluate regional capacity deployment against demand growth trajectories, ensuring that manufacturing footprints are aligned with the markets that will drive the highest value growth.
- Monitor competitive moves closely, as pricing adjustments and raw material cost pass-throughs are reshaping the margin landscape and creating both threats and opportunities for players with strong customer relationships.
The powder coatings market is entering a phase where strategic clarity matters more than ever. The combination of regulatory pressure, raw material cost volatility, and sustained demand growth from automotive, appliances, architecture, and industrial applications creates a complex operating environment. Organizations that equip themselves with precise, forward-looking intelligence will be best positioned to capture value while competitors navigate uncertainty with less visibility.
Our full market research report provides the depth, structure, and actionable insight required to make informed decisions across the 2026-2032 horizon. We invite you to explore the complete study for the comprehensive data, competitive analysis, and strategic recommendations that will guide your next moves in this evolving market.
For detailed analysis of this topic, please visit the official page: Powder Coatings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Clinical Mass Spectrometry Market to Hit $2.36B by 2032 with 9.35% CAGR
By pmarketresearch, 2026-09-15
Unlocking Precision: A Strategic Roadmap for the Clinical Mass Spectrometry Market Through 2032
Executive Overview
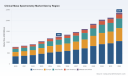
The clinical mass spectrometry landscape is undergoing a fundamental transformation, driven by the convergence of regulatory simplification, assay automation, and an expanding menu of precision diagnostics. Between 2020 and 2025, the global market demonstrated robust momentum, rising from approximately 785 million USD to an estimated 1.26 billion USD. As we enter 2026, the sector is projected to reach roughly 1.347 billion USD, with sustained growth expected across the 2026–2032 forecast horizon under a compound annual growth rate of 9.35 percent. By 2032, revenue is positioned to exceed 2.36 billion USD, signaling a structural shift from niche, laboratory-intensive workflows toward routine, clinically integrated testing paradigms.
PW Consulting’s latest Clinical Mass Spectrometry Market research equips executive teams, product strategists, and commercial leaders with a decision-grade framework to navigate this inflection point. Rather than delivering static snapshots, this study translates macro-level momentum into actionable go-to-market intelligence, competitive positioning insights, and regulatory-readiness guidance tailored to 2026 planning cycles.
Why This Study Matters Now
Strategic planning in the clinical diagnostics space has never been more complex. Manufacturers, laboratory directors, and health-system procurement teams are simultaneously evaluating platform investments, reimbursement pathways, and multi-year commercialization roadmaps. Three forces are reshaping the decision environment:
- Regulatory and complexity reclassification. Recent classification updates are lowering operational barriers for mass spectrometry-based testing, enabling broader deployment outside highly specialized centers. This expansion changes adoption curves, service models, and competitive intensity.
- Assay menu expansion and automation. Vendors are accelerating integrated reagent-and-platform strategies that bundle analyzers with clinically meaningful test menus, shifting purchasing decisions from standalone instrumentation toward total solution value.
- Reimbursement and coding dynamics. Evolving procedure coding frameworks and payer-specific coverage variability are influencing laboratory budgeting and test selection, making reimbursement intelligence a direct driver of commercial success.
For decision-makers, the challenge is no longer simply recognizing that the market is expanding. The strategic imperative is understanding where value is consolidating, which workflow models are becoming standard, and how to align product, pricing, and partnership choices with the next phase of market maturation.
Market Trajectory and What It Reveals
The historical record from 2020 through 2025 reflects a market that has more than kept pace with advancing clinical demand and technology maturation. The progression from mid-2020 levels toward the 1.26 billion USD mark in 2025 demonstrates not only volume growth but also deepening adoption across institutional and commercial laboratory settings. Entering 2026, the forecast trajectory remains consistently upward, extending toward 2.36 billion USD by 2032.
Importantly, this growth is not uniform across all technology categories or clinical use cases. The study examines how specific platform architectures, application focus areas, and regional adoption patterns diverge in terms of maturity, pricing power, and competitive density. Rather than presenting high-level percentages in isolation, the full report maps these relationships to real-world purchasing behavior and service economics. Readers seeking exact regional or segment breakdowns will find those delineated within the complete analysis, but the core strategic message is clear: future winners will be defined by workflow integration, evidence generation, and regulatory alignment rather than instrument specs alone.
The market’s concentration profile further underscores the importance of positioning. With the top three players accounting for a majority share and the top five holding an even larger portion of total revenue, new entrants and expanding incumbents must avoid head-to-head commoditization in saturated segments. Instead, the report identifies whitespace opportunities tied to specialized assays, simplified operational workflows, and regional partnership models that can accelerate commercial traction.
Inside the Report: Actionable Intelligence for 2026 Decision-Making
Designed for strategy, R&D, and commercial leadership, this study goes beyond top-line forecasts to address the operational questions that determine execution quality. The full research package includes:
- Market sizing and forecast architecture across historical baselines and forward-looking scenarios, with transparent methodology to support internal modeling and investment committees.
- Technology and workflow mapping that compares platform categories and their clinical fit, enabling organizations to assess where automation, software, and reagent integration will matter most.
- Application-level analysis covering the clinical domains shaping demand, including therapeutic monitoring, screening programs, hormone and hemoglobin testing, and adjacent utility areas.
- Competitive benchmarking of leading organizations, focused on portfolio strategy, product differentiation, and recent commercial and regulatory milestones.
- Regulatory and reimbursement context that ties classification decisions, clearance events, and coding updates to laboratory uptake and commercial viability.
- Strategic recommendations for segmentation targeting, pricing architecture, channel strategy, and partnership design, calibrated to the current competitive landscape.
Each section is structured to support immediate decision-making while also providing the foundational data needed for long-range planning. The emphasis is on interpretation over enumeration: the study highlights where attention should be allocated, what trade-offs are likely to emerge, and which indicators can serve as early signals of shift in adoption or competitive intensity.
Competitive Landscape and Strategic Positioning
The competitive field reflects a blend of broad-diagnostics scale, specialized mass spectrometry heritage, and increasingly integrated software-plus-hardware solutions. Several organizations stand out as reference points for understanding how portfolios are being shaped:
Thermo Fisher Scientific continues to anchor its clinical mass spectrometry strategy in quantitative workflows, emphasizing solutions designed for biomarker verification, quantitative clinical analysis, and precision medicine pipelines. Its platform-oriented approach highlights the growing importance of software-enabled quantification in real laboratory environments.
MALDI-TOF Mass Spectrometer Market
Waters Corporation has focused on analytical performance for therapeutic drug monitoring, biomarker testing, and TDM applications, with FDA-cleared systems reinforcing its emphasis on clinically validated workflows. This orientation illustrates the strategic value of regulatory clearance in building institutional trust and expanding access to routine use cases.
Bruker Daltonics GmbH & Co. KG has extended its presence through systems and software aimed at microorganism identification and differentiation from clinical samples. Recent regulatory clearance for its clinical mass spectrometry microorganism identification and differentiation system, classified as Class II with special controls under 21 CFR 866.3378, underscores the expanding role of mass spectrometry in infectious disease diagnostics and the importance of clear regulatory pathways for adoption.
Roche Diagnostics International AG has been moving aggressively to expand an automated mass spectrometry menu for routine clinical use. With a cobas-based mass spec solution, Ionify reagent packs covering antibiotics, steroid hormones, and vitamin D metabolites, and a broad IVD menu aligned with CE Mark recognition, the company has been positioning mass spectrometry as part of a broader, automation-friendly diagnostic offering. Recent milestones include CE Mark approval for antibiotic drug monitoring reagents and FDA classification of steroid assays as moderate-complexity under CLIA, both of which expand the potential scope of deployment in standard laboratory settings.
Taken together, these profiles reveal a market in which differentiation is increasingly tied to operational simplification, regulatory readiness, and clinically relevant assay breadth. The complete study provides deeper comparative analysis, including how each organization’s strategy intersects with purchasing criteria, laboratory workflow priorities, and regional adoption patterns.
Regulatory, Reimbursement, and Operational Signals Shaping Strategy
Recent developments are shifting the operational baseline for clinical mass spectrometry and, by extension, the commercial strategy required to capture demand:
Clinical Mass Spectrometry Market
- Regulatory approval and clearance events are broadening the practical scope of mass spectrometry in routine diagnostics, particularly where automation and reagent integration reduce hands-on complexity.
- Complexity reclassification is lowering the operational barrier for certain assays, extending access beyond specialized laboratories and creating new pathways for volume expansion.
- Reimbursement coding updates continue to evolve, with procedure-level frameworks such as CPT 82542 influencing how laboratory testing is documented and reimbursed. Because payer coverage and analyte-specific reimbursement can vary widely, test selection and commercial planning increasingly depend on reimbursement intelligence rather than technical feasibility alone.
- Industry engagement remains active, with sector conferences and professional bodies contributing to standards discussion, best-practice sharing, and technology adoption signals that can inform timing and positioning decisions.
For companies planning multi-year investments, the strategic implication is that product excellence is necessary but no longer sufficient. Commercial success depends on orchestrating regulatory alignment, reimbursement readiness, service models, and evidence generation in a coordinated way. The report translates these dynamics into practical checkpoints for decision-makers evaluating product roadmaps, partnership opportunities, and market entry timing.
Strategic Takeaways for 2026 Planning
As organizations finalize strategy for 2026, the clinical mass spectrometry market offers both clear opportunity and sharper competitive contrast. The most relevant implications include:
- Prioritize workflow value over instrument specifications. Decision-makers are increasingly weighing total solution benefits, including software enablement, reagent integration, and operational burden, rather than isolated analytical performance metrics.
- Use regulatory milestones as competitive moats. Clearance, classification, and approval events can shape adoption speed and laboratory eligibility. Mapping these milestones to commercial messaging and launch sequencing is becoming essential.
- Tailor regional and application strategies to real adoption conditions. Maturity levels differ across geographies and clinical applications. A disciplined approach to where, how, and with whom to scale can improve return on commercial investment.
- Plan for concentration dynamics. With a relatively consolidated revenue base among leading players, expanding firms should define defensible differentiation and identify partnership or specialization routes that reduce exposure to undifferentiated competition.
- Embed reimbursement intelligence early. Because coverage and coding realities influence laboratory purchasing and test volume, commercial models that account for reimbursement uncertainty are better positioned to withstand budget constraints and payer scrutiny.
Secure the Complete Strategic Intelligence
This overview is designed to demonstrate the strategic depth and decision relevance of PW Consulting’s Clinical Mass Spectrometry Market research without diluting the proprietary segmentation analysis and scenario detail that executives need. The full report provides the regional and application-level breakdowns, forecast trajectories, competitive benchmarking, and operational recommendations necessary to convert market visibility into measurable advantage.
For leadership teams preparing capital allocation, product roadmap reviews, partnership evaluations, or regional expansion plans, the complete analysis offers a structured basis for de-risking choices in a fast-evolving environment. To access the full dataset, segmentation detail, and executive recommendations, request the comprehensive study and make 2026 planning decisions with a stronger foundation.
For detailed analysis of this topic, please visit the official page: Clinical Mass Spectrometry Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Silicon Wafer Market to Hit $209.6M by 2032, 6.5% CAGR
By pmarketresearch, 2026-09-15
Strategic Imperatives in the Silicon Wafer Market: 2026 Outlook and Beyond
The silicon wafer remains the foundational substrate upon which the modern semiconductor industry is built. As chip architectures grow more complex and demand surges from artificial intelligence, automotive electrification, and high-performance computing, the wafer market has transitioned from a commoditized supply chain component to a strategic bottleneck. PW Consulting's latest market research on the Silicon Wafer Market offers a comprehensive lens into this evolving landscape, providing enterprise leaders with the intelligence required to navigate the period from 2026 through 2032.
This report is not merely a collection of statistics. It is a strategic toolkit designed to inform capital allocation, supply chain resilience planning, and competitive positioning. In an environment defined by geopolitical friction, capacity expansions, and rapid technological shifts, understanding the macro trajectory and the nuanced dynamics of the supply base is critical. The following insights preview the depth of analysis available in the full study, highlighting why this intelligence is essential for decision-makers in 2026.
Market Trajectory and Growth Vectors
The silicon wafer market has demonstrated resilient growth over the past half-decade, recovering from pandemic-era disruptions and capitalizing on the digital transformation boom. Our analysis tracks revenue performance from 2020 through the base year of 2025, establishing a robust historical baseline. The market has expanded steadily, reflecting the insatiable demand for integrated circuits and the gradual recovery of solar applications. Looking forward, the forecast period from 2026 to 2032 projects a compound annual growth rate of 6.5%. This growth is not linear; it is punctuated by cycles of capacity addition, technological node transitions, and regional policy interventions.
Revenue projections indicate a clear upward path, with market size expected to surpass significant milestones by the end of the decade. The acceleration is underpinned by the proliferation of advanced packaging, the adoption of wider diameters for cost efficiency, and the specific requirements of logic and memory manufacturers pushing the boundaries of performance. However, growth rates vary across segments and regions, influenced by local industrial policies and capacity utilization rates. The full report dissects these variations without losing sight of the overarching trend: the silicon wafer market is entering a phase of sustained expansion driven by structural demand rather than temporary cyclical upticks.
Silicon Wafer Market
Stakeholders must recognize that these figures represent more than headline numbers. They reflect the aggregate outcome of investment decisions made by major producers, the timing of fab constructions, and the interplay between supply constraints and demand elasticity. For instance, recent shipment data from industry bodies indicates continued momentum in square inch deliveries, corroborating the revenue growth trajectory observed in financial metrics. This alignment between physical volume and monetary value reinforces the reliability of the forecast model employed in this study.
Segmentation Dynamics: Type, Application, and Regional Nuances
A superficial view of the market obscures the critical divergences that dictate profitability and strategic risk. The silicon wafer market is segmented by type, application, and region, each presenting distinct challenges and opportunities. Our research provides a granular breakdown of these segments, analyzing share contributions and growth rates to identify where value is being created and where competition is intensifying.
Product Type and Technology Transitions
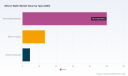
The market is anchored by established substrate types, yet innovation in specialized wafers is reshaping the competitive landscape. Prime polished substrates continue to command the largest share, serving as the workhorse for general-purpose semiconductor manufacturing. However, the growth premium is increasingly found in Silicon on Insulator and Epitaxial and Specialty wafers. These high-value products are essential for advanced logic, radio frequency applications, and power management devices.
The shift toward wider diameters, particularly the dominance of 300 mm wafers in leading-edge logic and memory production, drives efficiency gains for manufacturers but requires substantial capital investment. Meanwhile, 200 mm wafers retain relevance in automotive, analog, and mature node applications. The report evaluates the capacity mix across these types, highlighting how leading producers are reallocating resources to capture high-margin segments. For example, the expansion of epitaxial capabilities by key players signals a strategic bet on the convergence of AI workloads and high-performance power devices. Understanding the balance between standard and specialty wafers is crucial for forecasting margin profiles and supply security.
Application Drivers and Demand Centers
Demand for silicon wafers is heterogeneous, driven by diverse end-use applications. Integrated Circuits remain the dominant consumption center, reflecting the pervasiveness of semiconductors in electronics, computing, and communications. However, other applications are gaining traction. Solar Cells, while subject to policy fluctuations and technology shifts, continue to represent a significant volume segment, with wafer requirements tied to global renewable energy targets. The "Others" category encompasses niche but high-growth areas such as MEMS and RF devices, which often demand specialized wafer specifications.
The report analyzes how application mix influences regional demand patterns. For instance, regions with strong automotive manufacturing bases exhibit different wafer consumption profiles compared to hubs focused on consumer electronics or data center infrastructure. By mapping application demand to regional production and trade flows, the study reveals potential vulnerabilities in supply chains. Companies relying on wafers for specific applications must assess whether their suppliers are adequately exposed to those end markets or if portfolio diversification offers a buffer against sector-specific downturns.
Regional Landscape and Policy Influence
Geography plays a pivotal role in the silicon wafer market, shaped by manufacturing concentration, proximity to logic fabs, and government incentives. Asia Pacific stands as a colossal region in terms of market size, reflecting the dense concentration of semiconductor fabrication in East and Southeast Asia. North America and Europe, while smaller in aggregate volume, are experiencing renewed strategic interest due to onshore manufacturing initiatives and supply chain security concerns. Latin America and the Middle East and Africa represent emerging or niche markets with specific growth potentials tied to local industrial development or investment inflows.
Policy interventions are reshaping regional dynamics. Regulations and incentives are altering the calculus for capacity location. In China, targets for domestic usage of advanced silicon wafers by major chipmakers signal a push for self-sufficiency that could impact global trade flows and pricing dynamics. Concurrently, in the United States, preliminary terms under the CHIPS and Science Act for major wafer suppliers indicate support for constructing new 300 mm facilities, aiming to bolster domestic supply for critical industries. These policy-driven shifts create both opportunities for suppliers aligned with national strategies and risks for those exposed to trade barriers or subsidy-driven distortions.
Semiconductor Silicon Wafer Market
The full report provides detailed regional analysis, including market size estimates and growth projections for each area, while respecting the complexity of local market structures. It avoids oversimplification, instead offering a nuanced view of how regional policies, infrastructure, and talent pools interact to shape competitive outcomes. Decision-makers can use this analysis to evaluate market entry strategies, partnership opportunities, and risk exposure in specific geographies.
Competitive Landscape: Incumbents, Strategies, and Moves
The silicon wafer industry is characterized by high barriers to entry, significant capital intensity, and technological expertise. Market concentration is substantial, with the top three companies commanding a large share of global revenue and the top five consolidating an even greater portion. This concentration underscores the importance of monitoring the strategic moves of key players. PW Consulting's report profiles the major companies shaping the market, analyzing their product portfolios, geographic footprints, and recent developments.
Shin-Etsu Chemical Co., Ltd. and SUMCO Corporation, both headquartered in Tokyo, remain titans in the global arena. Shin-Etsu produces a comprehensive range of 300 mm prime, epitaxial, SOI, and annealed silicon wafers for logic, memory, and power devices, maintaining a broad technology base. SUMCO manufactures high-quality polished and epitaxial silicon wafers, with production sites spanning Japan, Malaysia, and the United States, reflecting a globalized operational model. Siltronic AG, based in Munich, specializes in 300 mm prime, epitaxial, and power device wafers, with manufacturing capabilities in Germany, Singapore, the United States, and Asia. Recent announcements, such as the inauguration of a new 300 mm epitaxial wafer fabrication facility in Singapore, highlight the ongoing investment in advanced capacity and customer qualification efforts.
GlobalWafers Co., Ltd., headquartered in Hsinchu, Taiwan, supplies 200 mm, 300 mm, and SOI silicon wafers for leading-edge logic, memory, and automotive applications, with facilities in Taiwan, Japan, and the United States. Its involvement in CHIPS Act-related discussions underscores the strategic importance of wafer supply in national security contexts. SK Siltron Co., Ltd., located in Gumi, South Korea, produces 200 mm and 300 mm silicon wafers primarily for memory, logic, and power devices, leveraging proximity to key memory manufacturers.
Wafer Works, based in Taipei, manufactures 150 mm, 200 mm, and 300 mm polished and epitaxial silicon wafers for IC, MEMS, and RF applications, catering to a diverse set of device requirements. Zhonghuan Advanced Semiconductor Materials Co., Ltd., in Yixing, China, produces 150 mm, 200 mm, and 300 mm silicon wafers for semiconductor and related industries, representing the expanding domestic capabilities in the region. Okmetic Oyj, headquartered in Vantaa, Finland, manufactures 150 mm, 200 mm, and 300 mm silicon wafers for MEMS, RF, power, and logic applications, adding a European dimension to the supply base.
Beyond company profiles, the report analyzes recent developments that signal shifts in strategy or market conditions. Shipment forecasts from the SEMI Silicon Manufacturers Group indicate growth trajectories driven by AI-related demand for advanced epitaxial and HBM wafers, with updates showing increases in square inch volumes through late 2025 and into 2026. However, not all news is positive; structural shifts in the global semiconductor market have led to delays in construction projects for some major producers, illustrating the volatility and cyclical nature of capacity planning. These events provide critical context for understanding near-term supply availability and competitive responses.
Strategic Applications of the Report
PW Consulting's Silicon Wafer Market report is designed to be actionable. It equips stakeholders with the insights needed to address pressing strategic questions.
- Capital Investment and Capacity Planning: Evaluate the timing and scale of capacity expansions against demand forecasts. Assess the risk of overcapacity or shortages in specific wafer types or regions, and align investment decisions with long-term growth vectors.
- Supply Chain Resilience: Identify dependencies on concentrated suppliers or regions. Analyze the impact of geopolitical policies, such as domestic usage targets or subsidy programs, on supplier viability and trade routes. Develop strategies to mitigate disruption risks.
- Competitive Benchmarking: Compare your organization's position against key competitors in terms of product coverage, geographic presence, and technological capabilities. Understand the strategic priorities of market leaders to anticipate moves in pricing, capacity, or customer engagement.
- Segment and Application Focus: Determine which wafer types and applications offer the most attractive growth and margin profiles. Align product development or procurement strategies with the segments driving value creation, while monitoring the dynamics of mature or cyclical segments.
- Policy and Regulatory Navigation: Understand the landscape of industrial policy affecting the silicon wafer market. Assess how regulations and incentives might alter market structure, influence supplier behavior, and create new opportunities or constraints for market participants.
The report synthesizes macro data with micro-level analysis, providing a holistic view that supports scenario planning and risk assessment. By integrating shipment data, facility announcements, and policy developments, the study offers a dynamic perspective on market evolution. It helps leaders move beyond static assumptions and prepare for a range of possible futures.
Conclusion: Navigating the Next Phase of Growth
The silicon wafer market stands at a critical juncture. The convergence of technological advancement, capacity expansion, and geopolitical realignment is reshaping the industry's structure and competitive dynamics. With a projected compound annual growth rate of 6.5% through 2032 and a market size on a clear upward trajectory, the sector offers significant opportunities for those equipped with the right intelligence. However, success requires more than optimism; it demands a deep understanding of the factors driving growth, the segments where value is shifting, and the strategic actions of key competitors.
PW Consulting's comprehensive research provides the foundation for informed decision-making. It reveals the data and analysis necessary to navigate the complexities of the silicon wafer market with confidence. We invite industry leaders, investors, and supply chain professionals to explore the full report to access the detailed segmentation data, regional breakdowns, and competitive intelligence that will inform their strategies for 2026 and beyond. In a market where information is a strategic asset, this report delivers the clarity needed to act decisively.
For detailed analysis of this topic, please visit the official page: Silicon Wafer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects 9% CAGR for $32.3B Tax Software Market Through 2032
By pmarketresearch, 2026-09-15
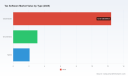
Strategic Intelligence for an Evolving Compliance Landscape: Inside the 2026 Tax Software Market Research
The global tax software market stands at a critical inflection point. Built on a foundation of sustained expansion from 2020 through 2025, the sector has demonstrated remarkable resilience in the face of regulatory shifts, technological disruption, and evolving user expectations. Our newly released market research report offers a comprehensive, forward-looking analysis designed specifically to equip executive teams, product strategists, and investment decision-makers with the intelligence required to navigate 2026 and beyond.
This is not a retrospective exercise. It is a strategic instrument. By synthesizing historical trajectories, near-term projections, and the structural forces reshaping the industry, the report provides a clear vantage point from which to evaluate competitive positioning, technology adoption timelines, and market entry opportunities. The tax software ecosystem is no longer defined solely by filing efficiency. It is increasingly shaped by cloud migration, regulatory modernization, accessibility mandates, and the consolidation of professional and consumer-grade platforms. Understanding how these currents intersect is essential for organizations that intend to lead rather than react.
A Macro Trajectory Grounded in Structural Momentum
The market’s recent performance underscores the durability of its growth drivers. Over the past half-decade, total industry revenue has climbed steadily, reflecting both incremental adoption and the widening scope of tax technology across individual, small business, and enterprise segments. As we move into the 2026-2032 forecast window, the sector is projected to advance at a sustained compound annual growth rate of approximately 9.0 percent. This trajectory points toward a market that will meaningfully expand its total addressable base, driven by digital transformation mandates, elevated compliance complexity, and the ongoing shift away from legacy, on-site infrastructure.
It is important to recognize that this growth is not uniform or inevitable. It is contingent upon the strategic choices being made now: how vendors balance usability with functionality, how regulators recalibrate filing infrastructure, and how organizations allocate resources between standalone tax tools and integrated financial platforms. The report contextualizes these dynamics within a broader economic and regulatory framework, enabling leaders to differentiate between noise and genuine inflection points.
What the Research Delivers: Actionable Architecture, Not Abstract Commentary
This study was designed with execution in mind. Rather than offering high-level observations, it provides a granular, operationally relevant mapping of the tax software landscape. The analysis spans technology delivery models, user segments, and regional deployment patterns, with each dimension examined through the lens of market performance, adoption barriers, and competitive differentiation. Readers will find structured assessments of how product architecture influences customer retention, how regulatory expectations are forcing feature prioritization, and where consolidation pressures are reshaping vendor strategies.
Accounting Software Market
The report also dissects the operational realities of the market. Licensing economics, integration requirements, and the cost structures associated with multi-user professional environments are evaluated alongside the compliance obligations that define vendor viability. By connecting these operational variables to broader market behavior, the research enables stakeholders to model scenarios with greater precision. Whether you are assessing product roadmap investments, evaluating partnership opportunities, or mapping acquisition targets, the framework is built to support decision-making that must withstand scrutiny.
Competitive Positioning and the Architecture of Market Leadership
The competitive field in tax software is concentrated and distinctly layered. A handful of dominant players command a significant share of the addressable market, while a broad array of specialized providers compete on niche functionality, regional compliance depth, and pricing architecture. The market’s concentration profile, with leading firms collectively representing a substantial portion of total industry revenue, reflects the high barriers to entry associated with regulatory approvals, continuous software modernization, and the trust required in tax preparation workflows.
Intuit Inc., headquartered in Mountain View, California, remains a defining presence in the consumer and self-employed segments, leveraging widely recognized preparation and filing platforms that emphasize accessibility and guided user experiences. Across the professional and small business landscape, firms such as H&R Block Inc. and TaxAct, LLC continue to refine individual filing pathways while integrating e-filing support and accuracy-driven service models. Meanwhile, specialized preparers and smaller practices are served by providers including Drake Software, TaxSlayer LLC, On-Line Taxes, Inc., CFS Tax Software, Inc., and Advanced Tax Solutions, each offering targeted capabilities that align with specific practitioner workflows and compliance requirements.
On the enterprise and professional services side, Wolters Kluwer N.V. and Thomson Reuters Corporation maintain influential positions through comprehensive suites designed for accounting firms and corporate tax departments. Their offerings emphasize multi-user collaboration, regulatory update cadence, and the integration of tax workflows into broader professional practice ecosystems. The competitive interplay between these groups is not simply a matter of scale; it is defined by how well each organization aligns its product cadence with regulatory timelines, user expectations, and the shifting economics of software delivery. The report maps these dynamics in detail, revealing where differentiation is becoming durable and where it remains vulnerable to disruption.
Recent activity among these players highlights the operational tempo required to remain competitive. Throughout early 2026, several major vendors conducted update webinars and released version enhancements aimed at addressing program changes, newly enacted tax laws, and workflow improvements. Simultaneously, compliance bodies have continued to formalize expectations for electronic submission quality, error validation, and rapid processing feedback. These developments are not incidental. They illustrate the market’s increasing reliance on continuous modernization and the premium placed on providers who can deliver reliable, timely updates under compressed compliance cycles.
Regulatory Modernization and the Reshaping of Vendor Obligations
The operating environment for tax software is being rewritten in real time. Regulatory modernization efforts on the federal level have introduced stricter testing and data formatting expectations for electronic filing providers, requiring vendors to demonstrate consistent compliance with processing standards before their solutions can be approved for use. This dynamic elevates the strategic importance of certification readiness, technical infrastructure, and the speed at which updates can be validated and deployed.
Tax Software Market
At the state level, similar expectations are taking hold. Recent guidance from tax authorities, including recent franchise tax preparation software approval processes, has reinforced the requirement for electronic submission support, enhanced error detection, and prompt feedback mechanisms. These mandates affect not only large professional platforms but also the broader ecosystem of preparers and accounting firms that depend on compliant, current, and interoperable tools. For vendors, this means that regulatory alignment is no longer a back-office concern. It is a core product differentiator and a determinant of market access.
The accessibility dimension adds another layer of strategic complexity. Government-supported guided preparation options, available to taxpayers below specific income thresholds, continue to shape consumer expectations around cost, usability, and service availability. At the same time, professional tax software packages remain subject to annual licensing economics that influence adoption decisions among firms seeking multi-user access. These intersecting forces, affordability on one side and professional-grade functionality on the other, are reshaping how value is defined across the market. The research examines how vendors are responding to these tensions and where opportunity lies for those who can balance compliance rigor with user experience.
Why This Research Matters for 2026 Decision-Making
As organizations plan for the remainder of 2026 and the years that follow, the tax software market presents both opportunity and complexity. Growth is real, but it is not distributed evenly across segments, technologies, or geographies. Firms that succeed will be those that can interpret where demand is structurally accelerating, where competitive positions are being fortified or eroded, and where regulatory shifts will create new requirements for vendor performance. The report is built to provide precisely that clarity.
Executive audiences will find particular value in the study’s integrated treatment of market behavior and competitive design. Rather than isolating data points from their strategic context, the analysis ties market movement to the underlying drivers that matter most: technology delivery preferences, compliance demands, licensing economics, and the evolving expectations of both individual filers and professional preparers. By doing so, it equips leaders to make informed choices about product investment, market entry, partnership strategy, and risk exposure.
This research is also intended to support scenario planning. Because the tax software landscape is sensitive to legislative action, infrastructure modernization, and user adoption cycles, the ability to test assumptions against a structured industry baseline is a meaningful advantage. The report provides that baseline, along with the analytical tools needed to evaluate how different external variables could alter competitive outcomes over the forecast period.
Accessing the Full Strategic Picture
The insights summarized here represent only the opening layer of a much deeper body of analysis. The complete report contains the detailed segmentation architecture, competitive benchmarking, regulatory mapping, and forward-looking evaluation necessary to translate high-level market direction into concrete business strategy. To fully assess where the tax software market is heading and how your organization should position itself within it, we invite you to access the full research on our website.
For teams responsible for product planning, market expansion, investment allocation, or competitive intelligence, the full study offers the depth required to move beyond assumption and into structured, evidence-based decision-making. The market will continue to evolve under the pressure of regulatory change, technological adoption, and shifting user expectations. The organizations that prepare now will be the ones best positioned to shape that evolution.
For detailed analysis of this topic, please visit the official page: Tax Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Denim Market to Hit $252M by 2032, Growing at 5.8% CAGR
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Denim Jeans Market: Navigating Growth, Compliance, and Competitive Shifts in 2026
The global denim jeans market stands at a pivotal inflection point as it moves through the mid-2020s. What was once viewed as a stable segment of the broader apparel industry is now shaped by intersecting forces: shifting consumer expectations around sustainability and fit, evolving trade and compliance frameworks, and a competitive landscape that rewards both scale and specificity. For executives, category leaders, and supply chain decision-makers, the task ahead is no longer simply to track volume. It is to understand where value is being created, which structural risks are becoming structural costs, and how to position portfolios for the forecast period through 2032.
The market research introduced in this report is designed to convert those complexities into decision-ready intelligence. It provides a structured lens on revenue trajectories, segmentation behavior, competitive positioning, and the operational realities that will shape profitability in the years ahead.
A Market Reshaped by Scale, Momentum, and Reallocation
Denim jeans continue to occupy a distinctive place in global wardrobes, but their commercial dynamics are being rewritten. Over the historical window from 2020 to 2025, the market absorbed significant volatility in demand patterns, sourcing priorities, and inflationary pressure on input costs. That period set the stage for a clearer growth trajectory in the forecast years. The overall market size is projected to rise from approximately 170.0 million USD in 2025 to 184.58 million USD in 2026, with continued expansion thereafter. By 2032, revenue is expected to reach 252.0 million USD, implying a forecast CAGR of 5.8 percent across the 2026 to 2032 period.
These figures are more than top-line markers. They reflect a market in which growth is being distributed unevenly across categories, regions, and business models. Total market size alone does not tell leaders where to invest, how to price, or which sourcing strategies will hold up under regulatory scrutiny. That is why the study goes beyond aggregate numbers and examines the structural drivers underneath them.
Several contextual forces are already reshaping how participants plan for 2026 and beyond. Input cost expectations remain a central concern, with cotton projected to reach up to 1.75 USD per kilogram in 2026, a 2.9 percent increase from prior forecasts, against a backdrop of global cotton production contraction of up to 2 percent during the 2025 to 2026 season. Trade policy uncertainty is equally significant. Tariff exposure on denim jeans imports from Vietnam and Turkey could face potential baseline rates of 46 percent and 10 percent respectively following 2025 policy changes and any 90-day pauses. At the same time, regulatory actions are sharpening the focus on supply chain integrity, as seen in the November 2025 U.S. Customs and Border Protection Withhold Release Order against Firemount Group Ltd. for garments, textiles, and apparel manufactured in Mauritius due to indicators of forced labor. These developments do not merely create headline risk; they change the cost of doing business and the criteria by which sourcing decisions are evaluated.
Why This Research Matters for 2026 Decision-Making
The strategic value of this study lies in its suitability for real operating decisions. It is not a retrospective summary of market size; it is a forward-looking framework for executives who must allocate capital, adjust assortments, renegotiate sourcing terms, and prepare for policy-driven disruption. The report is built to support three core decision domains: portfolio strategy, supply chain resilience, and competitive positioning.
In portfolio strategy, the research helps leaders interpret where demand is concentrated and how different product types and use cases contribute to overall market behavior. Rather than presenting narrow percentage splits that can be misread in isolation, the analysis frames segmentation in terms of relative importance, demand logic, and strategic implications. That approach allows teams to evaluate category priorities with more context than a single static table can provide.
In supply chain planning, the study connects market structure to operational risk. Sourcing diversification, factory concentration, transparency expectations, and compliance due diligence all influence margin stability. The inclusion of recent regulatory and trade developments gives decision-makers a practical basis for scenario planning, particularly where sourcing footprints span multiple jurisdictions.
In competitive positioning, the report examines how major participants differentiate themselves through product architecture, sourcing models, sustainability claims, and distribution strength. The objective is to show not just who is active in the market, but how each player's strategy affects their exposure to pricing pressure, demand volatility, and regulatory change.
What the Report Covers: Content Designed for Execution
The study is organized to move from market structure to actionable implications. It combines quantitative framing with qualitative interpretation, so that readers can understand both the direction of travel and the operational consequences. The content is intended to help teams translate market signals into prioritized actions.
Key components of the report include:
- A comprehensive market overview that situates historical performance within the forecast period, highlighting the base year reference point of 2025 and the forward trajectory through 2032.
- Segmentation analysis that explores how product types, end-use applications, and regional dynamics contribute to overall market behavior, without reducing the market to oversimplified share figures.
- Competitive profiling of leading participants, with attention to sourcing footprints, product emphasis, transparency practices, and strategic differentiation.
- Industry context covering regulatory actions, raw material cost expectations, trade policy exposure, and event-driven innovation signals that are likely to influence planning assumptions.
- Practical interpretation for corporate strategy, including where concentration, compliance, and cost pressures are most likely to shape margin outcomes.
The report also integrates recent developments that illustrate how quickly market conditions can shift. In August 2026, Denim Show returned to Pragati Maidan in New Delhi, India, creating a platform for denim brands to launch new products and explore innovation trends. In September 2025, Candiani Denim extended its product lines with the launch of a new made-in-Italy denim capsule collection with customizable Millesimo fits through Alberto Candiani x Velasca. In November 2025, Levi Strauss & Co. expanded availability of its Blue Tab premium line, featuring Japanese selvedge-inspired heavier denim jeans, to more stores for fall 2026. These examples are not isolated announcements; they reflect broader patterns in premiumization, regional sourcing identity, and product innovation that matter for assortment planning and brand positioning.
Competitive Landscape: Differentiation Under Pressure
The denim jeans market is not highly concentrated in the traditional sense. Reported concentration indicators point to a CR3 of 14.0 percent and a CR5 of 16.0 percent, suggesting that no small group of firms dominates total market revenue. That fragmentation creates both opportunity and risk. It allows new product concepts and specialized sourcing models to gain traction, but it also raises the importance of brand strength, distribution reach, and compliance credibility.
Among the most visible participants, Levi Strauss & Co. remains closely associated with the category through its Levi's franchise and global sourcing footprint. Its profile reflects a model built on design, marketing, and broad contract manufacturing across more than 32 countries, reinforced by supply chain transparency tools such as an interactive supplier map. For competitors and partners, this combination of brand equity and visibility is strategically significant because it links consumer trust to operational disclosure.
Gap Inc. operates through its Gap and Old Navy brands, with sourcing diversification that includes Vietnam and Bangladesh for denim and woven bottoms. This broader manufacturing base illustrates a practical response to cost, capacity, and risk management considerations, but it also means that tariff exposure and compliance oversight must be managed carefully across multiple production ecosystems.
H&M Group continues to rely on a large outsourced manufacturing network, with supplier lists spanning many tier-1 factories, primarily in Asia, and updated on a quarterly basis. The scale of this sourcing architecture underscores the importance of supplier governance, audit cadence, and the ability to respond when regulatory or reputational expectations change.
MUD Jeans represents a different strategic direction, emphasizing premium circular denim produced from post-consumer recycled jeans and lower-impact production for men and women. Its positioning highlights a growing market appetite for sustainability-led differentiation, while also illustrating the operational complexity of recycled-material sourcing and product traceability.
Candiani Denim operates at the fabric and product level with a focus on high-end denim, regenerative cotton, post-consumer recycled denim, and biodegradable stretch jeans. Its supplier relationships with fashion brands show how upstream innovation can shape downstream product claims and premium positioning. The September 2025 capsule collaboration with Alberto Candiani x Velasca, introducing customizable Millesimo fits, is a useful reminder that product-level innovation can be as important as volume expansion in competitive markets.
Firemount Group Ltd. illustrates the vertically integrated manufacturing model, with production in Mauritius and documented supply chain details. However, the November 2025 Withhold Release Order from U.S. Customs and Border Protection demonstrates how quickly a sourcing model can become a strategic liability if labor compliance concerns arise. This case is particularly important because it shows that even vertically integrated structures do not automatically insulate a company from regulatory exposure when forced labor indicators are identified.
Denim and Beyond LLC rounds out the competitive picture as an importer and provider of denim jeans, including lines associated with Levi Strauss and Banana Republic, handling U.S. distribution and import logistics. Its role reflects the importance of intermediary distribution, import execution, and category specialization within a fragmented market.
Taken together, these profiles show that competitive advantage in denim jeans increasingly depends on more than cost efficiency. Brand trust, product differentiation, transparency, compliance readiness, and sourcing flexibility all influence which firms can sustain margin and share as the market evolves.
Operational Realities: Cost, Compliance, and Trade Exposure
For 2026 planning, three overlapping pressures deserve particular attention: raw material cost, trade policy, and compliance enforcement. Each can independently affect margin, but together they can reshape sourcing economics and product pricing strategies.
Denim Market
On raw materials, cotton cost expectations are moving higher, with a projected price of up to 1.75 USD per kilogram in 2026 and a 2.9 percent increase from earlier forecasts. This sits against a global production contraction of up to 2 percent during the 2025 to 2026 season. For denim manufacturers and brands, that combination can translate into tighter input availability, more volatile purchase timing, and greater pressure on fabric negotiation strategies. Companies that depend heavily on conventional cotton may need to evaluate hedging approaches, alternative fiber blends, or supplier relationships that provide more stable access.
On trade policy, the potential for elevated baseline tariffs on imports from key sourcing countries creates uncertainty for cost modeling. Tariff exposure on denim jeans imports from Vietnam and Turkey could reach potential baseline rates of 46 percent and 10 percent respectively, depending on 2025 policy changes and any 90-day pauses. Even when pauses or negotiations modify the final outcome, the mere presence of such risk forces companies to rethink lead times, country mix, inventory positioning, and scenario-based pricing.
On compliance, the November 2025 Withhold Release Order directed at Firemount Group Ltd. is a clear signal that enforcement can interrupt supply and damage supplier credibility. The order directed detention of garments, textiles, and apparel manufactured in Mauritius due to indicators of forced labor. For brands and distributors, this reinforces the need for robust supplier due diligence, traceability, and rapid response capabilities when regulatory actions occur. It also illustrates why transparency tools and documented supply chain details are increasingly part of competitive positioning rather than optional ESG narrative.
These dynamics are not abstract. They affect cost-to-serve, product availability, launch timing, and the credibility of sustainability and sourcing claims. The study incorporates these factors so that decision-makers can assess them as part of integrated strategy rather than as isolated external events.
Implications for Strategic Planning
The most effective use of this research is to connect market structure with operational choices. The data points to a market that is growing, but not uniformly, and not without cost and risk. Participants that succeed in 2026 and beyond are likely to be those that can balance several priorities at once: protect margin against input and trade pressures, differentiate through product and sustainability credibility, and maintain sourcing flexibility without weakening compliance standards.
That balance requires granular understanding. It is not enough to know that the market is expanding from 170.0 million USD in 2025 toward 252.0 million USD in 2032. Leaders also need to understand how segmentation behavior, competitive models, and regulatory exposure interact in practice. The report is designed to provide that connecting tissue, helping teams move from awareness to action.
Denim Jeans Market
Get the Full Intelligence
This overview reveals the strategic shape of the denim jeans market and why it matters for 2026 decision-making, but the full study contains the deeper analysis, segmentation logic, competitive detail, and operational interpretation needed for execution. The complete report provides the structured market framework, participant profiles, and context-driven implications that support sourcing strategy, category planning, risk management, and investment prioritization.
To access the full market research and the detailed intelligence behind these insights, visit the PW Consulting report page and obtain the complete Denim Jeans Market study.
For detailed analysis of this topic, please visit the official page: Denim Jeans Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Encrypted USB Market Hits $200M in 2025, Poised for 7.5% CAGR Growth Through 2032
By pmarketresearch, 2026-09-15
Strategic Imperatives in the Encrypted USB Flash Drives Market: A 2026 Outlook
In an era where data breaches can cripple reputations and incur billions in fines, the humble USB flash drive has evolved from a simple storage accessory into a critical endpoint security asset. As organizations navigate the complex intersection of remote work, stringent regulatory compliance, and escalating cyber threats, the demand for secure removable media is no longer optional—it is a foundational requirement for operational resilience. PW Consulting has released a comprehensive market research report detailing the trajectory of the Encrypted USB Flash Drives Market, offering vital intelligence for stakeholders looking to secure their data infrastructure through 2032.
This market has demonstrated remarkable resilience and growth over the past half-decade. Historical analysis from 2020 to 2025 reveals a consistent upward trend, with the overall market valuation climbing from 120.0 million USD to a projected 200.0 million USD by the base year. This trajectory underscores a shifting paradigm where security is prioritized over convenience. Looking forward, the forecast period from 2026 to 2032 suggests that this momentum will not only continue but accelerate, driven by tighter government mandates and enterprise security protocols.
Market Trajectory and Growth Dynamics
The financial outlook for this sector is robust. Starting from a valuation of 210.95 million USD in 2026, the market is expected to expand significantly, reaching 330.0 million USD by 2032. This growth is anchored by a compound annual growth rate (CAGR) of 7.5 percent over the forecast period. Such performance indicates that investment in encrypted storage solutions is becoming a standard line item in IT security budgets rather than a niche expenditure. The expansion is not merely a function of price increases but reflects a deepening penetration of secure storage solutions across diverse industry verticals.
Several key factors are fueling this expansion. First, the proliferation of remote and hybrid work models has decentralized data storage, increasing the risk surface associated with removable media. Employees moving between secure corporate networks and public spaces require portable storage that does not become a liability. Second, the regulatory landscape is hardening. Recent updates to state-level security standards, such as the Iowa Removable Storage Device Security Standard effective June 2025, mandate the use of 256-bit AES or stronger encryption for devices storing confidential data. Similarly, NIST SP 800-111 guidelines continue to require self-encrypting USB drives for federal agencies handling sensitive data on removable media.
Furthermore, the transition from FIPS 140-2 to FIPS 140-3 Level 3 validation represents a critical threshold for high-assurance government and defense applications. Cryptographic modules used in encrypted USB flash drives for these sectors must now meet stricter validation criteria, effectively creating a barrier to entry that favors established, compliant manufacturers. This regulatory pressure acts as a tailwind for the market, compelling organizations to upgrade their hardware to meet compliance standards, thereby driving volume and value.
Segmentation and Value Distribution
Understanding where value resides within the market is crucial for strategic positioning. The market is segmented by type, region, and application, each presenting unique opportunities and challenges. In terms of technology type, hardware-encrypted solutions dominate the landscape. This segment reflects a strong market preference for security that is independent of the host operating system. Hardware encryption ensures that data protection is intrinsic to the device, reducing the risk of software vulnerabilities or user error compromising the encryption key. Software encrypted and hybrid options occupy smaller shares, catering to specific use cases where flexibility or cost constraints are prioritized over maximum security assurance.
Geographically, the market reflects mature security infrastructures in certain regions alongside growing adoption in others. North America remains the largest revenue contributor, driven by high enterprise spending on cybersecurity and strict government procurement standards. Europe follows as a significant market, influenced by GDPR compliance requirements and robust public sector procurement. The Asia Pacific region represents a dynamic growth engine, where rapid digital transformation and increasing awareness of data sovereignty are prompting both enterprises and governments to invest in secure storage hardware. Latin America and the Middle East and Africa, while smaller in current valuation, are emerging markets where increased digitization is expected to drive incremental demand.
Application-wise, enterprise use cases capture the largest share of the market. Corporations are increasingly recognizing that data loss prevention strategies must extend to removable media. Government use is the second major pillar, heavily influenced by procurement mandates and defense-related security requirements. Consumer use, while present, remains a smaller fraction of the total revenue, as individual users often prioritize cost and capacity over advanced encryption features unless compelled by specific privacy concerns.
Competitive Landscape and Strategic Positioning
The market is characterized by a high degree of concentration, with the top three companies accounting for approximately 70 percent of market revenue and the top five firms holding around 85 percent. This consolidation suggests that scale, compliance certification, and established distribution channels are significant moats for incumbent players. However, innovation in encryption technology and form factor continues to provide avenues for differentiated positioning.
USB Drive Market
Kingston Technology Company, Inc., headquartered in Fountain Valley, California, stands as a leader in the hardware-encrypted space. Their IronKey series, including the Locker+ 50 G2 and D500S, exemplifies the market standard with 256-bit AES XTS hardware encryption and FIPS 140-3 Level 3 validation. In March 2026, Kingston released the next-generation IronKey Locker+ 50 G2, reinforcing their commitment to enterprise-grade security features and FIPS 197 certification. Earlier, in July 2025, they unveiled the IronKey D500S as the first FIPS 140-3 Level 3 flash drive meeting Trade Agreements Act rules, a critical milestone for government procurement eligibility.
Apricorn, based in Poway, California, specializes in software-free 256-bit AES XTS hardware-encrypted USB flash keys. Their Aegis Secure Key series is renowned for environmental hardening, making them suitable for harsh operational conditions. In May 2026, Apricorn updated the Aegis Secure Key 3 (ASK3) with faster speeds and improved environmental protection, while submitting for FIPS 140-3 Level 3 validation. This focus on ruggedness and pure hardware encryption appeals to sectors like defense, law enforcement, and industrial field operations.
DataLocker Inc. offers a strong value proposition through its Sentry series, which includes FIPS 140-2/3 Level 3 certified encrypted USB flash drives with SafeConsole remote management. Their March 2025 launch of the Sentry ONE drive highlighted capabilities such as remote wipe and multi-certifications including NIST, CSPN, and BSI/BSZ. This emphasis on management software alongside hardware security addresses the enterprise need for centralized control over distributed devices, ensuring compliance with regulations like HIPAA, GDPR, and CMMC.
Other key players further diversify the competitive landscape. Kanguru Solutions provides government-certified 256-bit hardware-encrypted secure USB drives with remote management and endpoint protection. iStorage, based in the United Kingdom, delivers hardware-encrypted drives like the datAshur PRO series, featuring PIN/password protection and FIPS-validated encryption for high-security data transfers. Clevy focuses on hardware-encrypted secure USB drives with advanced encryption and management tools for enterprise data security. Western Digital Corporation, through its SanDisk brand, provides encrypted USB flash drives featuring AES encryption and secure access software, leveraging its broad consumer and enterprise brand recognition to penetrate the secure storage market.
Strategic Implications for Decision Makers
For enterprise leaders, IT security officers, and procurement strategists, the insights contained in this market research extend beyond simple revenue forecasts. The shift toward hardware-encrypted dominance suggests that software-based encryption alone may increasingly fall short of compliance requirements for sensitive data. Organizations must evaluate whether their current portable storage strategies align with the 256-bit AES standards and FIPS 140-3 mandates that are becoming prevalent.
The concentration of market power among the top players indicates that supply chain stability and vendor longevity are critical considerations. Partnering with vendors who have a proven track record of maintaining certifications through regulatory updates is essential. The recent product launches by key competitors highlight a race toward higher performance, better durability, and stricter validation. For instance, the ability to remotely manage and wipe devices, as offered by DataLocker and Kanguru, is becoming a differentiator for enterprises managing large fleets of distributed workers.
Furthermore, the regional dynamics suggest that global organizations must adopt a nuanced approach. While North American and European markets demand strict adherence to local compliance frameworks, the Asia Pacific region may offer growth opportunities for vendors who can balance security with cost-effectiveness and local data sovereignty laws. The report provides a detailed breakdown of these regional nuances, helping stakeholders identify where to allocate resources for maximum impact.
Conclusion and Next Steps
The Encrypted USB Flash Drives Market is at a inflection point where security, compliance, and mobility converge. The projected growth to 330.0 million USD by 2032 is not just a number; it represents a structural change in how organizations handle sensitive data on the move. With regulatory pressures intensifying and cyber threats evolving, the choice of encrypted storage solutions is a strategic decision that impacts risk management, compliance posture, and operational efficiency.
Encrypted USB Flash Drives Market
This executive summary provides a high-level view of the market dynamics, competitive forces, and growth drivers. However, the full depth of the analysis contained in the PW Consulting report offers the granular data necessary to build detailed go-to-market strategies, investment models, and risk assessments. To access the complete segmentation data, detailed competitor profiles, and comprehensive regulatory impact analysis, we invite you to explore the full report. Equip your organization with the intelligence needed to navigate the secure storage landscape with confidence.
For detailed analysis of this topic, please visit the official page: Encrypted USB Flash Drives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial Gases Market to Reach $167.3B by 2032, Driven by 6.5% CAGR
By pmarketresearch, 2026-09-15
Navigating the Industrial Gases Landscape: Strategic Intelligence for 2026 and Beyond
The industrial gases sector stands at a critical inflection point. As global manufacturing footprints shift, energy transition mandates accelerate, and semiconductor supply chains reconfigure, the demand for oxygen, nitrogen, hydrogen, and specialty gases is evolving from a steady utility market into a strategically contested arena. PW Consulting's latest Industrial Gases Market research report offers decision-makers a comprehensive, data-driven roadmap to navigate this transformation. Covering historical performance from 2020 through 2025 and extending detailed forecasts to 2032, this analysis equips executives, investors, and supply chain leaders with the intelligence required to price risk, allocate capital, and secure long-term competitive advantage.
Macro Trajectory and Forecast Architecture
Over the past half-decade, the industrial gases market has demonstrated consistent expansion, moving from approximately 80.5 billion USD in 2020 to an estimated 108.0 billion USD by the 2025 base year. This trajectory reflects not only post-pandemic industrial recovery but also structural demand shifts driven by electronics manufacturing, clean energy infrastructure, and advanced materials processing. Looking forward, the market is projected to reach 112.85 billion USD in 2026, with growth compounding steadily through the forecast horizon to exceed 167.3 billion USD by 2032. The implied compound annual growth rate of 6.5 percent positions the sector as a resilient, above-average growth segment within broader industrial supply chains.
Such macroeconomic momentum, however, masks significant underlying complexity. Growth is not uniform across geographies, product categories, or end-use verticals. Strategic planners must understand where volume accumulates, which applications command premium pricing, and how regional energy economics reshape cost structures. Our report deconstructs these layers without oversimplifying them, providing scenario-based modeling that accounts for energy price volatility, capital expenditure cycles, and regulatory shifts that will define the 2026 to 2032 window.
Demand Drivers and Structural Shifts
Several interconnected forces are reshaping procurement patterns and investment priorities across the industrial gases ecosystem. First, the accelerating deployment of advanced semiconductor fabrication facilities has created sustained demand for ultra-high-purity nitrogen and specialty gas mixtures, with major supply agreements already signaling multi-year capacity commitments. Second, the global push toward decarbonization is elevating hydrogen from a niche byproduct stream to a central pillar of industrial strategy, particularly in refining, ammonia synthesis, and emerging clean mobility applications. Third, healthcare and food & beverage sectors continue to drive steady consumption of medical-grade oxygen, carbon dioxide, and argon, though margin profiles in these segments differ markedly from heavy industrial contracts.
Simultaneously, the cost environment remains a decisive factor. Electricity consumption for cryogenic air separation represents a major operating expense, and fluctuations in grid pricing directly influence producer margins. Natural gas continues to serve as the primary feedstock for many production processes, including air separation and hydrogen generation, making energy arbitrage and regional gas pricing critical variables in site selection and contract structuring. Inflationary pressures and energy cost volatility have already perturbed revenue and earnings trajectories for leading producers, while workforce dynamics have begun to stabilize, with industry headcount projections settling near 20,000 by the end of 2026. Understanding how these macroeconomic inputs propagate through pricing models, contract duration negotiations, and capital allocation decisions is essential for 2026 planning.
Competitive Landscape and Strategic Positioning
The industrial gases market is characterized by a moderately concentrated structure, with the top three players commanding approximately 55 percent of aggregate revenue and the top five entities controlling roughly 65 percent. This concentration reflects the capital intensity of production infrastructure, the value of long-term supply agreements, and the operational expertise required to maintain stringent purity and safety standards. Yet the competitive field extends beyond the largest multinational incumbents, encompassing regional specialists, integrated chemical producers, and technology-focused equipment providers that collectively shape pricing dynamics, innovation velocity, and service-level expectations.
Industrial Gases Market
Leading global providers continue to anchor the market through diversified gas portfolios and deep integration with manufacturing, chemicals, and energy sectors. Firms headquartered in France, the United States, and Ireland have historically led in scale, leveraging air separation technology, cryogenic equipment capabilities, and extensive pipeline networks to secure long-term contractual relationships. Specialized producers in Germany and Japan complement this landscape by emphasizing nitrogen, oxygen, and hydrogen production technologies tailored to specific industrial processes, while North American and Japanese manufacturers provide critical supply for electronics, healthcare, and food processing applications. Integrated chemical and energy companies also play a meaningful role, particularly where carbon dioxide and hydrogen emerge as value-added byproducts of larger processing operations.
Recent Strategic Moves and Capacity Allocation
The competitive rhythm has intensified through a series of high-profile agreements and infrastructure investments that illuminate where capital and demand are converging. In mid-2025, major suppliers executed long-term industrial gas supply agreements with leading semiconductor manufacturers, signaling multi-year commitments to support new production facilities and expanded wafer fabrication capacity. These contracts underscore the strategic importance of reliable, ultra-high-purity gas delivery in an industry where downtime carries extraordinary cost.
Simultaneously, decarbonization has moved from policy aspiration to executable project pipeline. A landmark initiative launched in early 2025 committed over one billion euros to electrolyzer units supporting green hydrogen production, reflecting a decisive shift toward low-carbon gas supply chains and signaling how traditional producers are repositioning their portfolios. In the second half of the year, additional capacity expansions were announced, including significant manufacturing and logistics center investments designed to strengthen regional supply resilience and reduce lead times for industrial customers. These moves illustrate a broader pattern: incumbents are simultaneously defending core-volume relationships in steel, chemicals, and manufacturing while building optionality in clean energy and high-purity electronics supply.
Regulatory, Operational, and Cost Dynamics
No strategic assessment of the industrial gases market is complete without confronting the regulatory and operational realities that define commercial viability. Purity and safety standards enforced by regulatory bodies such as the FDA and EMA impose specialized equipment requirements and rigorous quality control protocols, particularly for healthcare and electronics applications. Compliance is not a peripheral concern; it dictates capital intensity, validation timelines, and the cost of market entry for new facilities or product grades.
On the environmental policy front, carbon pricing mechanisms and emissions trading frameworks are beginning to reshape the economics of outsourced hydrogen and other gas supply. Benchmark reductions under evolving European regulatory structures are projected to affect free allowance distributions for significant hydrogen sales volumes, introducing new variability into pricing models and contract structures. Producers and offtakers alike must anticipate how these mechanisms will influence net costs, pass-through provisions, and the relative competitiveness of low-carbon versus conventional supply pathways.
Operationally, electricity consumption remains the dominant cost driver for cryogenic air separation plants, making energy procurement strategy a core component of margin management. Natural gas feedstock availability and pricing further influence production economics, particularly in regions where pipeline infrastructure and regional pricing dynamics diverge. Meanwhile, labor and overhead costs have experienced inflationary pressure, though industry employment levels are expected to stabilize through 2026 as automation and process optimization offset headcount expansion. Together, these dynamics create a complex optimization problem for producers seeking to balance reliability, purity, cost, and sustainability commitments.
What the Report Delivers for 2026 Decision-Making
PW Consulting's Industrial Gases Market research is designed to convert these macro trends, competitive signals, and operational constraints into actionable strategy. The report goes beyond high-level sizing to provide a detailed dissection of market architecture, including the following core components:
- Historical performance analysis spanning 2020 through 2025, establishing baseline demand patterns, pricing environments, and capacity utilization trends that inform forward-looking assumptions.
- Forecasting frameworks extending to 2032, built on scenario modeling that captures energy cost variability, regulatory evolution, and demand elasticity across major industrial verticals.
- Competitive profiling of leading global and regional players, including strategic positioning, technology focus areas, and recent contractual and investment activity that signal future market direction.
- Segment-level intelligence that explains how demand distributes across product categories and end-use applications without reducing the picture to simplistic share splits, enabling precise go-to-market and pricing strategy development.
- Regional demand assessment that contextualizes growth opportunities and cost dynamics across key markets, helping planners calibrate inventory, logistics, and local partnership strategies.
- Operational and regulatory deep dives covering purity standards, emissions framework implications, energy and feedstock cost exposure, and labor market trends that directly affect margin structures and capital planning.
Each section is engineered to support concrete decisions: whether to enter or expand in a specific geography, how to structure long-term supply agreements under volatile energy conditions, where to prioritize capital allocation for capacity upgrades, and how to anticipate regulatory cost pass-through in hydrogen and specialty gas contracts. The analysis is anchored in rigorous data handling and contextualized with industry-on-the-ground developments, ensuring that executives receive not just numbers, but interpretable intelligence.
Why This Research Matters Now
The 2026 planning cycle demands more than retrospective review. Semiconductor capacity build-outs, decarbonization project pipelines, and evolving emissions frameworks are already reshaping contractual expectations and cost baselines. Producers, offtakers, investors, and equipment suppliers must simultaneously manage near-term margin pressures while positioning for multi-year demand shifts. In this environment, the difference between reactive adjustment and proactive strategy lies in access to integrated, forward-looking intelligence that ties market sizing to competitive behavior, regulatory trajectory, and operational cost drivers.
This report provides that integration. It identifies where growth is structurally supported versus cyclically sensitive, which segments face tightening purity and compliance requirements, and how leading firms are reallocating capital to capture both traditional volume and emerging clean-energy demand. By connecting these threads, the analysis enables decision-makers to prioritize initiatives with the highest strategic return and to avoid blind spots that can erode competitiveness over the forecast horizon.
Moving from Insight to Action
The industrial gases market will not be defined solely by aggregate growth figures. It will be shaped by who secures long-term supply relationships in high-purity electronics, who executes decarbonization projects on schedule and on budget, and who manages energy and feedstock exposure with discipline. The 6.5 percent compound annual growth trajectory and the expansion from roughly 108.0 billion USD in 2025 to over 167.3 billion USD by 2032 create a substantial opportunity set, but capturing it requires granular understanding of segment dynamics, regional cost structures, and competitive intent.
Medical Gases Market
PW Consulting's full Industrial Gases Market report delivers the depth required to act confidently in 2026 and beyond. To access the complete segmentation breakdowns, company-level strategic profiles, scenario forecasts, and operational cost analysis, visit the official report page and download the full intelligence package. Equip your team with the market clarity needed to negotiate from strength, allocate capital with precision, and build resilience into your industrial gas strategy for the remainder of the decade.
For detailed analysis of this topic, please visit the official page: Industrial Gases Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Gate Bipolar Transistors STATCOM Market Hits $215M in 2025, 3x to $345M by 2032 at 6.98% CAGR
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Gate Bipolar Transistor STATCOM Market: Navigating the 2026–2032 Growth Arc
The global power grid is undergoing a structural transformation. As renewable penetration accelerates and transmission networks face heightened stability demands, the need for fast-acting reactive power compensation has moved from niche engineering requirement to central grid modernization imperative. At the heart of this shift lies the Gate Bipolar Transistor (GBT)-based STATCOM market. PW Consulting’s latest research report delivers a comprehensive, data-grounded assessment of this sector, covering historical performance from 2020 through 2025 and projecting forward across the 2026–2032 forecast horizon. For executives, procurement leaders, and technology strategists, the report serves as a decision-grade compass rather than a retrospective summary.
Why the 2026 Baseline Matters Now
Market participants often treat forecast years as abstract timelines. In reality, 2026 represents the first full operational cycle following a series of regulatory, technological, and infrastructural inflection points that will dictate competitive positioning for the remainder of the decade. The market closed 2025 at a valuation of 215.0 million USD, building on a consistent expansion trajectory that began at 163.15 million USD in 2020. This five-year historical window captures the early scaling phase of IGBT-driven static compensators as utilities and independent power producers moved beyond pilot deployments into standardized grid-edge integration.
Looking ahead, the forecast period projects a compound annual growth rate of 6.98 percent, with the market expected to reach 231.71 million USD in 2026 and continue its upward path toward 344.8 million USD by 2032. These figures are not merely top-line projections; they reflect an underlying shift in how grid operators prioritize voltage support, harmonic mitigation, and dynamic reactive power injection. For companies evaluating product roadmaps, capacity investments, or regional market entry, understanding the velocity and composition of this growth is essential. PW Consulting’s analysis isolates the structural drivers behind this trajectory while deliberately withholding granular segmentation breakdowns, ensuring that only stakeholders who engage with the full study can access the precise regional, application, and type-level intelligence required for tactical execution.
Market Structure and Demand Vectors
The STATCOM landscape is fundamentally shaped by voltage class, end-use application, and geographic deployment patterns. High Voltage STATCOM configurations continue to dominate total market value, reflecting the scale of transmission-level grid reinforcement projects and the technical requirements of large-scale renewable interconnection. Low Voltage STATCOM solutions, while smaller in aggregate revenue contribution, represent a strategically distinct segment driven by industrial microgrids, data center power quality upgrades, and localized distribution network stability initiatives.
IGBT Market
From an application perspective, renewable energy integration stands as the primary demand engine. The necessity for STATCOM systems to deliver voltage support with IGBT response times in the 1-to-5 millisecond range has become a defining performance criterion, as documented in recent grid integration research. Electric utilities form the second major demand pillar, leveraging GBT-based compensators for transmission congestion management, fault ride-through enhancement, and compliance with evolving harmonic distortion limits. Industrial and manufacturing sectors, along with specialized use cases in infrastructure and commercial power conditioning, complete the application mosaic, each imposing distinct reliability, scaling, and interface requirements on equipment manufacturers.
Regional deployment patterns reveal a highly distributed demand footprint, with mature grid modernization programs in established markets operating alongside rapid capacity build-out in emerging transmission corridors. This geographic diversification means that no single regional strategy can capture the full growth opportunity. Companies must evaluate supply chain localization, service network density, and regulatory alignment across multiple jurisdictions simultaneously. The complete regional and application-level quantification, including precise share distributions and revenue allocations, is reserved for the full report to preserve the analytical depth required for accurate market entry and resource allocation planning.
Regulatory Tailwinds and Technical Standardization
Policy and standards frameworks are no longer peripheral considerations; they actively shape procurement cycles, technology selection, and competitive barriers to entry. In Europe, EU Directive 2019/944 mandates market-based, transparent procurement of reactive power using STATCOM devices, forcing utilities and system operators to formalize sourcing processes and evaluate suppliers against structured performance and pricing criteria. Parallel developments in Germany point toward a reactive power market expected to commence in the early-to-mid 2025 window, requiring transmission system operator tenders specifically structured around STATCOM procurement to meet grid stability obligations.
On the technical side, IEEE Std 519-2014 and the updated IEEE Std 519-2025 continue to govern harmonic limits for IGBT-based STATCOM installations, establishing compliance benchmarks that directly influence converter topology selection, filtering architecture, and long-term operational acceptance. Standardization activity also extends to device-level comparisons, with recent IEEE Power & Energy Society analysis highlighting that T-STATCOM converter structures utilizing 3.3 kV silicon IGBTs deliver measurable overload handling advantages over silicon carbide MOSFET alternatives in high-voltage applications. These technical nuances have direct implications for product positioning, bill-of-materials strategy, and performance validation protocols.
Regulatory and standardization trajectories are accelerating procurement formalization, but they also introduce compliance complexity that favors organizations with robust engineering documentation, certification pathways, and tender response capabilities. PW Consulting’s report maps these regulatory shifts against demand timelines, helping clients anticipate tender windows, align product certifications, and structure proposal architectures that meet both technical specifications and procurement transparency requirements.
Competitive Landscape and Strategic Positioning
The Gate Bipolar Transistor STATCOM market operates with a moderately fragmented but highly capable participant base. The combined market share of the top three competitors sits at 24.6 percent, while the top five reach 26.2 percent, indicating that no single entity commands decisive pricing power and that technological differentiation, regional execution, and service integration remain the primary competitive levers. This concentration profile rewards companies that can combine reliable converter performance with localized project delivery and long-term grid operator relationships.
A diverse set of established and regional players defines the current competitive fabric. Siemens Energy brings comprehensive transmission-grade power electronics expertise and a structured approach to grid integration projects across Europe and global utility markets. ABB Ltd continues to leverage its broad electrification portfolio, emphasizing scalable STATCOM architectures and digital grid management interfaces. Rongxin Power Electronic Co., Ltd and Sieyuan Electric Co., Ltd represent China-based manufacturing capabilities that have expanded their footprint through cost-competitive product lines and growing international project participation. Hitachi Energy and Mitsubishi Electric Corporation contribute advanced converter technology and strong regional execution in Japan and selected export markets, while GE Vernova applies its grid solutions heritage to utility-scale reactive power infrastructure in North America and beyond.
Ingeteam adds specialized power conversion expertise with a focus on renewable-aligned grid support applications, and American Superconductor (AMSC) brings differentiated high-performance grid technology positioning. Hyosung Heavy Industries offers strong heavy electrical equipment integration capabilities, particularly relevant for combined transformer-converter STATCOM deployments. S&C Electric Company maintains a recognized presence in distribution-level grid protection and compensation solutions, while Fuji Electric Co., Ltd contributes mature power semiconductor and industrial control engineering to the competitive mix.
Competitive advantage in this environment rarely derives from volume alone. It emerges from the intersection of converter reliability, harmonic compliance documentation, turnaround speed on tender responses, service and maintenance coverage, and the ability to tailor voltage-class solutions to specific grid operator requirements. The full report provides detailed company-level strategic profiles, technology positioning assessments, and competitive move tracking, while withholding precise revenue allocations and share calculations to preserve the analytical exclusivity required for strategic planning.
What the Report Delivers for 2026 Decision-Making
PW Consulting’s Gate Bipolar Transistor STATCOM Market research is structured to support concrete executive and operational decisions rather than remain a descriptive market summary. The study integrates historical performance tracking, forward-looking valuation projections, segmentation mapping, competitive benchmarking, and regulatory-standards impact analysis into a unified decision framework. Readers gain access to a structured assessment of how demand vectors are evolving across voltage classes, application sectors, and regional deployment zones, alongside an evaluation of the procurement, compliance, and technical standardization factors that will shape supplier selection over the forecast period.
The report also provides operational intelligence relevant to product planning, capacity allocation, partnership strategy, and tender positioning. By aligning market trajectory data with technology performance criteria and regulatory timelines, the analysis enables clients to identify which segments offer the most defensible growth pathways, where service and localization investments will generate the strongest returns, and how to structure proposals in markets moving toward formalized reactive power procurement. To maintain the integrity of these insights for actionable use, core segmentation percentages, detailed regional and application-level valuations, and exact competitor revenue breakdowns are reserved for the complete study.
Gate Bipolar Transistors STATCOM Market
Strategic Recommendations for Market Participants
- Align product development and certification roadmaps with IEEE harmonic compliance expectations and emerging regional reactive power procurement mandates, ensuring that documentation and validation protocols are ready before tender cycles intensify.
- Evaluate high-voltage and low-voltage portfolio positioning as distinct strategic tracks, since each addresses different procurement authorities, technical specifications, and competitive dynamics.
- Prioritize regional execution capability over generalized global presence, focusing service network density, local engineering support, and supply chain responsiveness in markets where grid modernization budgets are accelerating.
- Use the moderately consolidated competitive structure as an opportunity to differentiate through performance reliability, tender response quality, and lifecycle service agreements rather than competing solely on initial equipment pricing.
- Incorporate 1-to-5 millisecond IGBT response performance and overload handling characteristics into product messaging and technical proposals, as these parameters are increasingly central to grid operator evaluation criteria for renewable integration and transmission support applications.
Conclusion: Securing the Intelligence Edge
The Gate Bipolar Transistor STATCOM market is entering a phase where growth is not only sustained but structurally reinforced by grid stability requirements, renewable integration acceleration, and formalized reactive power procurement frameworks. The historical expansion from 2020 through 2025 establishes a credible demand foundation, while the 2026–2032 forecast period points to continued value creation for organizations that can navigate technical standardization, regional procurement variation, and competitive differentiation with precision.
PW Consulting’s full market research report provides the depth, segmentation clarity, competitive profiling, and regulatory-aligned analysis required to convert this macro trajectory into executable strategy. To access the complete dataset, detailed segmentation valuations, regional and application-level breakdowns, and in-depth company strategic assessments, stakeholders are encouraged to visit the source report page and obtain the full intelligence package. In a market where timing, compliance readiness, and segment selection determine competitive outcomes, comprehensive and current intelligence is not optional. It is the foundation of effective 2026 decision-making.
For detailed analysis of this topic, please visit the official page: Gate Bipolar Transistors STATCOM Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Commercial Kitchen Ventilation Market to Hit $2,575.56M by 2032 at 6.8% CAGR
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Modern Kitchen: Inside Our 2026 Commercial Kitchen Ventilation Systems Market Report
The commercial kitchen ventilation sector is entering a decisive inflection point. What was once regarded as a static building infrastructure category is now a dynamic battleground where energy regulation, operational efficiency, and safety compliance intersect. For executives navigating capital allocation, supply chain strategy, and product portfolio optimization in 2026, the installation and service landscape is shifting faster than legacy forecasting models can capture. Our newly published market intelligence report maps this transformation with precision, offering a decision-ready compass for manufacturers, distributors, facility operators, and ecosystem investors across the commercial foodservice value chain.
The industry trajectory tells a clear story of sustained expansion. Drawing on a comprehensive historical window from 2020 through 2025 and projecting forward to 2032, the analysis quantifies momentum that has persisted through supply chain recalibration, labor constraints, and evolving building performance mandates. The underlying market has demonstrated consistent upward movement, with the base year establishing a firm valuation foundation that carries meaningful forward gravity. This calculated growth rate positions the sector as a structurally expanding category rather than a cyclical fluctuation, reinforcing its relevance in long-term strategic planning.
Adoption drivers are no longer limited to code compliance alone. While mandatory standards from the FDA Food Code and NFPA 96 continue to anchor baseline requirements for heat, smoke, grease, and vapor capture, a new layer of operational pressure is reshaping purchasing behavior. The 2021 Uniform Mechanical Code provides the technical framework for safe installation, but the market is now responding to deeper operational imperatives: utility cost volatility, localized emission controls, grease management accountability, and the financial drag of continuously running over-engineered exhaust systems. Against this backdrop, ventilation infrastructure is increasingly evaluated through the lens of total cost of ownership rather than upfront equipment pricing.
Decoding the Structural Composition of the Market
The commercial kitchen ventilation ecosystem is composed of interdependent product categories that collectively determine system performance, compliance outcomes, and lifecycle economics. The report dissects these segments to reveal where value is concentrated, which components face the most intense substitution dynamics, and how procurement patterns differ across installation contexts. Hoods remain the mechanical centerpiece of the category, but their dominance is increasingly measured against the growing strategic importance of exhaust fans, ducting architecture, makeup air balancing, and intelligent control integrations.
Each product pillar interacts with a distinct set of operational realities. Exhaust and ducting infrastructure dictates airflow efficiency and maintenance burden. Makeup air systems govern temperature stability and combustion safety within the kitchen envelope. Controls and accessories, once treated as peripheral add-ons, are now central to modulating fan speeds, matching ventilation output to actual cooking loads, and capturing energy savings in high-utilization environments. The study isolates these structural components not as isolated line items, but as a coordinated system where design choices in one layer directly alter performance, compliance exposure, and long-term operating expense in another.
Application-level demand patterns further complicate procurement planning. Commercial kitchens serve a wide spectrum of operational profiles, from high-turnover quick-service environments to institutional food preparation spaces with extended service hours and specialized ventilation needs. Hospitality venues, educational campuses, corporate and industrial dining facilities, and healthcare institutions each impose different hygiene standards, smoke management thresholds, and sanitation cycles. The report maps these application contexts to clarify where ventilation requirements diverge and where shared system architectures can be leveraged for scale without compromising regulatory alignment.
Regulatory Tailwinds and Technical Shifts Shaping 2026
The competitive and commercial rhythm of this market is being rewritten by regulatory evolution and engineering modernization. In 2025, the California Energy Commission advanced code change proposals targeting energy efficiency improvements and greenhouse gas reductions in commercial kitchens, with potential mandatory adoption of demand-controlled kitchen ventilation as the next progression beyond existing standards. Such developments signal a broader trajectory in which ventilation systems will be evaluated not only for their ability to capture contaminants, but for their capacity to modulate energy consumption in response to real-time cooking activity.
At the same time, foundational compliance expectations remain non-negotiable. FDA-driven public health protections require commercial exhaust systems to reliably capture and contain heat, smoke, grease, and vapors. NFPA 96 continues to mandate rigorous design, installation, and maintenance requirements for commercial cooking operations, while the Uniform Mechanical Code outlines the technical parameters for safe system deployment. These overlapping frameworks create both a compliance floor and a performance ceiling, compelling operators to balance safety assurance with efficiency optimization. The report examines how these regulatory pressures are translating into procurement criteria, service contract expectations, and retrofit decision-making.
Industry participants are already responding with product and service expansions that reflect this shifting mandate. Recent portfolio developments illustrate a clear industry trend toward integrated offering models. For example, a prominent foodservice equipment provider recently broadened its commercial kitchen hood service capabilities to encompass fully engineered ventilation systems, professional consultation, customized hood packages, makeup air units, ventless exhaust configurations, Type 1 and Type 2 hood variants, and specialized applications such as food truck and pizza oven exhaust designs, alongside fire suppression integration and hood filtration accessories. Such moves highlight a market moving from component sales toward end-to-end engineered solutions.
Competitive Landscape: Where Strategy Is Being Won or Lost
The market structure reflects meaningful concentration, with a limited group of established players commanding a significant share of revenue and engineering influence. This concentration shapes pricing dynamics, technology adoption velocity, and the pace at which new entrants can secure footholds in regulated segments. Understanding who leads, where they compete, and how they differentiate is essential for positioning product roadmaps, sales motions, and partnership strategies in 2026 and beyond.
CaptiveAire Systems, Inc., headquartered in Raleigh, North Carolina, stands as a leading manufacturer of commercial kitchen ventilation systems and is recognized for its breadth across exhaust hoods, fans, grease management, and complete HVAC solutions tailored to foodservice operations. Greenheck Fan Corporation, based in Schofield, Wisconsin, complements this competitive tier with a strong portfolio spanning exhaust hoods, fans, makeup air units, and energy recovery ventilation designed for restaurant and foodservice environments. Systemair AB, operating from Skinnskatteberg, Sweden, brings a distinctive emphasis on advanced kitchen exhaust systems, high-performance air purification, smart airflow controls, and demand-controlled ventilation approaches. Together, these players illustrate how leading manufacturers are converging around integrated air management rather than isolated hood fabrication.
A second layer of competition is defined by specialized technology positioning and regional execution strength. Gaylord Industries, located in Tualatin, Oregon, focuses on demand control kitchen ventilation systems, custom kitchen hoods, and pollution control equipment for commercial foodservice. FAST Kitchen Hoods, based in Mississauga, Ontario, has built recognition around cULus-rated commercial kitchen hoods, exhaust systems, island configurations, and low-ceiling solutions for restaurant applications. Chef’s Deal Restaurant Equipment, headquartered in Nashville, Tennessee, operates as both supplier and installer of comprehensive ventilation systems, covering engineered hoods, makeup air units, ventless exhaust, Type 1 and Type 2 grease hoods, and related accessories. This breadth of service orientation reflects an industry trend in which installation capability, customization, and after-sale support have become competitive differentiators, not optional adjuncts.
Commercial Kitchen Ventilation Systems Market
Additional participants continue to shape the market through control innovation and multi-region manufacturing presence. Melink Corporation, with nationwide operations in the United States, provides Intelli-Hood demand control kitchen ventilation systems and controls that target energy-efficient exhaust operations. North American Kitchen Solutions (NAKS), operating across Ohio, Georgia, and Texas, manufactures commercial kitchen hoods, exhaust and supply fans, fire suppression components, and portable ventless hood systems. These profiles underscore a market where product leadership is increasingly linked to control intelligence, modular deployment options, and the ability to serve both permanent and transient kitchen configurations.
Residential Ventilation Systems Market
What the Report Delivers: Actionable Intelligence for Decision-Makers
This study is designed to move beyond surface-level market sizing and into the operational and strategic details that inform investment and execution. The report maps current market size and forward valuation pathways, contextualizes historical performance from 2020 through 2025, and translates that trajectory into a forecast window extending to 2032. The emphasis is not simply on where the market has been, but on how structural variables will shape competitive outcomes over the coming planning cycle.
The analysis provides a practical framework for evaluating product and application dynamics without reducing them to static snapshots. Readers gain visibility into how core product categories relate to one another, where system-level design decisions influence downstream operating costs, and how application contexts alter ventilation priorities. This approach enables stakeholders to assess which segments are likely to attract the most engineering attention, which procurement groups will demand higher specification flexibility, and where service and integration capabilities will become essential to market access.
Equally important, the report situates competitive positioning within a realistic view of market concentration and differentiation levers. Rather than treating competitors as isolated company profiles, the study examines how leading manufacturers and specialized suppliers are aligning product architecture, regional execution, and service scope to capture distinct value pools. It also addresses the regulatory environment as a strategic variable, showing how evolving energy efficiency expectations, ventilation control requirements, and fire safety standards are reshaping procurement criteria and long-term system design philosophy.
Why This Research Matters for 2026 Strategy
The decisions being made in 2026 will determine how organizations position themselves for the next cycle of regulation, energy economics, and foodservice operational complexity. Capital deployed in ventilation infrastructure is no longer a passive compliance expense; it is a strategic asset that affects operating margin, safety performance, and readiness for emerging code requirements. A rigorous understanding of market direction, competitive intensity, and application-specific demand patterns is therefore essential for avoiding stranded investments and misaligned product plans.
This report is structured to support precisely those decisions. It gives executives the analytical clarity to evaluate growth pathways, the competitive context to benchmark positioning, and the operational insight to anticipate where specification, installation, and service expectations will tighten. For manufacturers, it clarifies where product emphasis and engineering investment are most defensible. For distributors and installers, it identifies where service breadth and solution integration will command premium value. For institutional and corporate operators, it supports more informed procurement and retrofit prioritization by linking ventilation design choices to compliance and lifecycle performance.
The broader takeaway is that the commercial kitchen ventilation market is being redefined by the convergence of safety mandates, energy performance expectations, and intelligent airflow control. Organizations that treat ventilation as a system-level discipline, rather than a component-level purchase, will be better positioned to navigate the next phase of market evolution. Our full research study provides the strategic anatomy required to make that transition with confidence.
To access the complete segmentation analysis, forecast timelines, competitive benchmarking, and regional and application-level intelligence behind this overview, we invite you to explore the full report on our website. The detailed data architecture, scenario considerations, and proprietary market mappings contained in the study are designed to support immediate planning as well as longer-range strategic commitment.
For detailed analysis of this topic, please visit the official page: Commercial Kitchen Ventilation Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Spain is an enchanting destination for couples dreaming of a romantic, sun-soaked wedding weekend. From cliffside luxury resorts overlooking the Balearic Sea to rustic historic masias tucked away in Catalonian countryside hills, the country presents endless backdrops for a spectacular celebration. However, designing a multi-day international wedding from afar requires far more than selecting a picturesque venue—it demands artistic direction, seamless travel management, local vendor curation, and flawless logistical oversight.
Partnering with an experienced wedding planner company spain like RoRas Destination Wedding elevates your wedding journey into an effortless luxury experience. Founded and led by Creative Director Roberto Raspollini, RoRas Destination Wedding specializes in tailor-made wedding design, full-service planning, and multi-day event execution across Spain and Italy.
Why Partner with a Dedicated Specialist in Spain
Coordinating a destination wedding from another country involves managing local contracts, overcoming language nuances, coordinating guest accommodations, and balancing timelines across time zones. Working with a dedicated luxury wedding planner provides key operational and aesthetic advantages:
Curated Access to Premier Venues: Discover private coastal villas, boutique vineyards, luxury beach clubs, and centuries-old Spanish estates across Ibiza, Formentera, Sitges, and Barcelona.
Bespoke Creative Direction: Rejecting pre-packaged templates, every styling element—from custom floral art and mood lighting to fine linens and stationery—is designed to reflect the couple's unique visual narrative.
Vetted Network of Spanish Vendors: Connect directly with top-tier caterers, pastry artists, classical and contemporary musicians, mixologists, and world-class wedding photographers.
Seamless Multi-Day Itinerary Execution: Extend your wedding beyond a single ceremony with coordinated welcome tapas parties, private yacht charters, sunset rehearsals, and farewell brunches.
Unforgettable Spanish Destinations for Your Celebration
RoRas Destination Wedding designs custom concepts tailored to Spain's most iconic regional landscapes:
1. Ibiza & Formentera (Balearic Islands)
Ideal for couples seeking bohemian elegance, Mediterranean coastal vistas, and vibrant sunset ceremonies. Host seaside vows and open-air galas at exclusive venues like 7 Pines Resort , Aiyanna Ibiza , or 10.7 Beach Club in Formentera.
2. Sitges & Catalonia Countryside
Surrounded by historic charm and lush pine forests, private estates like Masia Casa Nova near Sitges offer complete privacy, luxurious guest accommodations, and authentic architectural beauty for extended weekend festivities.
The RoRas Destination Wedding Distinction
Roberto Raspollini brings an international background in luxury hospitality, artistic styling, and multi-day event production to every client project:
Tailor-Made Philosophy: Every celebration is designed from scratch, ensuring a 100% unique experience without rigid package constraints.
Comprehensive Financial Oversight: Transparent budget planning and clear contract negotiations across all selected vendors.
On-the-Ground Coordination: Dedicated on-site direction throughout your entire itinerary so you can focus entirely on celebrating with family and friends.
Begin Planning Your Spanish Wedding Today
Turn your vision of an unforgettable Mediterranean celebration into reality. Explore services by this acclaimed wedding planner company spain and book a custom consultation with RoRas Destination Wedding.