

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Denim Market to Hit $252M by 2032, Growing at 5.8% CAGR

Strategic Intelligence for the Denim Jeans Market: Navigating Growth, Compliance, and Competitive Shifts in 2026
The global denim jeans market stands at a pivotal inflection point as it moves through the mid-2020s. What was once viewed as a stable segment of the broader apparel industry is now shaped by intersecting forces: shifting consumer expectations around sustainability and fit, evolving trade and compliance frameworks, and a competitive landscape that rewards both scale and specificity. For executives, category leaders, and supply chain decision-makers, the task ahead is no longer simply to track volume. It is to understand where value is being created, which structural risks are becoming structural costs, and how to position portfolios for the forecast period through 2032.
The market research introduced in this report is designed to convert those complexities into decision-ready intelligence. It provides a structured lens on revenue trajectories, segmentation behavior, competitive positioning, and the operational realities that will shape profitability in the years ahead.
A Market Reshaped by Scale, Momentum, and Reallocation
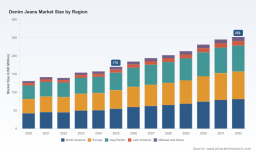
Denim jeans continue to occupy a distinctive place in global wardrobes, but their commercial dynamics are being rewritten. Over the historical window from 2020 to 2025, the market absorbed significant volatility in demand patterns, sourcing priorities, and inflationary pressure on input costs. That period set the stage for a clearer growth trajectory in the forecast years. The overall market size is projected to rise from approximately 170.0 million USD in 2025 to 184.58 million USD in 2026, with continued expansion thereafter. By 2032, revenue is expected to reach 252.0 million USD, implying a forecast CAGR of 5.8 percent across the 2026 to 2032 period.
These figures are more than top-line markers. They reflect a market in which growth is being distributed unevenly across categories, regions, and business models. Total market size alone does not tell leaders where to invest, how to price, or which sourcing strategies will hold up under regulatory scrutiny. That is why the study goes beyond aggregate numbers and examines the structural drivers underneath them.
Several contextual forces are already reshaping how participants plan for 2026 and beyond. Input cost expectations remain a central concern, with cotton projected to reach up to 1.75 USD per kilogram in 2026, a 2.9 percent increase from prior forecasts, against a backdrop of global cotton production contraction of up to 2 percent during the 2025 to 2026 season. Trade policy uncertainty is equally significant. Tariff exposure on denim jeans imports from Vietnam and Turkey could face potential baseline rates of 46 percent and 10 percent respectively following 2025 policy changes and any 90-day pauses. At the same time, regulatory actions are sharpening the focus on supply chain integrity, as seen in the November 2025 U.S. Customs and Border Protection Withhold Release Order against Firemount Group Ltd. for garments, textiles, and apparel manufactured in Mauritius due to indicators of forced labor. These developments do not merely create headline risk; they change the cost of doing business and the criteria by which sourcing decisions are evaluated.
Why This Research Matters for 2026 Decision-Making
The strategic value of this study lies in its suitability for real operating decisions. It is not a retrospective summary of market size; it is a forward-looking framework for executives who must allocate capital, adjust assortments, renegotiate sourcing terms, and prepare for policy-driven disruption. The report is built to support three core decision domains: portfolio strategy, supply chain resilience, and competitive positioning.
In portfolio strategy, the research helps leaders interpret where demand is concentrated and how different product types and use cases contribute to overall market behavior. Rather than presenting narrow percentage splits that can be misread in isolation, the analysis frames segmentation in terms of relative importance, demand logic, and strategic implications. That approach allows teams to evaluate category priorities with more context than a single static table can provide.
In supply chain planning, the study connects market structure to operational risk. Sourcing diversification, factory concentration, transparency expectations, and compliance due diligence all influence margin stability. The inclusion of recent regulatory and trade developments gives decision-makers a practical basis for scenario planning, particularly where sourcing footprints span multiple jurisdictions.
In competitive positioning, the report examines how major participants differentiate themselves through product architecture, sourcing models, sustainability claims, and distribution strength. The objective is to show not just who is active in the market, but how each player's strategy affects their exposure to pricing pressure, demand volatility, and regulatory change.
What the Report Covers: Content Designed for Execution
The study is organized to move from market structure to actionable implications. It combines quantitative framing with qualitative interpretation, so that readers can understand both the direction of travel and the operational consequences. The content is intended to help teams translate market signals into prioritized actions.
Key components of the report include:
- A comprehensive market overview that situates historical performance within the forecast period, highlighting the base year reference point of 2025 and the forward trajectory through 2032.
- Segmentation analysis that explores how product types, end-use applications, and regional dynamics contribute to overall market behavior, without reducing the market to oversimplified share figures.
- Competitive profiling of leading participants, with attention to sourcing footprints, product emphasis, transparency practices, and strategic differentiation.
- Industry context covering regulatory actions, raw material cost expectations, trade policy exposure, and event-driven innovation signals that are likely to influence planning assumptions.
- Practical interpretation for corporate strategy, including where concentration, compliance, and cost pressures are most likely to shape margin outcomes.
The report also integrates recent developments that illustrate how quickly market conditions can shift. In August 2026, Denim Show returned to Pragati Maidan in New Delhi, India, creating a platform for denim brands to launch new products and explore innovation trends. In September 2025, Candiani Denim extended its product lines with the launch of a new made-in-Italy denim capsule collection with customizable Millesimo fits through Alberto Candiani x Velasca. In November 2025, Levi Strauss & Co. expanded availability of its Blue Tab premium line, featuring Japanese selvedge-inspired heavier denim jeans, to more stores for fall 2026. These examples are not isolated announcements; they reflect broader patterns in premiumization, regional sourcing identity, and product innovation that matter for assortment planning and brand positioning.
Competitive Landscape: Differentiation Under Pressure
The denim jeans market is not highly concentrated in the traditional sense. Reported concentration indicators point to a CR3 of 14.0 percent and a CR5 of 16.0 percent, suggesting that no small group of firms dominates total market revenue. That fragmentation creates both opportunity and risk. It allows new product concepts and specialized sourcing models to gain traction, but it also raises the importance of brand strength, distribution reach, and compliance credibility.
Among the most visible participants, Levi Strauss & Co. remains closely associated with the category through its Levi's franchise and global sourcing footprint. Its profile reflects a model built on design, marketing, and broad contract manufacturing across more than 32 countries, reinforced by supply chain transparency tools such as an interactive supplier map. For competitors and partners, this combination of brand equity and visibility is strategically significant because it links consumer trust to operational disclosure.
Gap Inc. operates through its Gap and Old Navy brands, with sourcing diversification that includes Vietnam and Bangladesh for denim and woven bottoms. This broader manufacturing base illustrates a practical response to cost, capacity, and risk management considerations, but it also means that tariff exposure and compliance oversight must be managed carefully across multiple production ecosystems.
H&M Group continues to rely on a large outsourced manufacturing network, with supplier lists spanning many tier-1 factories, primarily in Asia, and updated on a quarterly basis. The scale of this sourcing architecture underscores the importance of supplier governance, audit cadence, and the ability to respond when regulatory or reputational expectations change.
MUD Jeans represents a different strategic direction, emphasizing premium circular denim produced from post-consumer recycled jeans and lower-impact production for men and women. Its positioning highlights a growing market appetite for sustainability-led differentiation, while also illustrating the operational complexity of recycled-material sourcing and product traceability.
Candiani Denim operates at the fabric and product level with a focus on high-end denim, regenerative cotton, post-consumer recycled denim, and biodegradable stretch jeans. Its supplier relationships with fashion brands show how upstream innovation can shape downstream product claims and premium positioning. The September 2025 capsule collaboration with Alberto Candiani x Velasca, introducing customizable Millesimo fits, is a useful reminder that product-level innovation can be as important as volume expansion in competitive markets.
Firemount Group Ltd. illustrates the vertically integrated manufacturing model, with production in Mauritius and documented supply chain details. However, the November 2025 Withhold Release Order from U.S. Customs and Border Protection demonstrates how quickly a sourcing model can become a strategic liability if labor compliance concerns arise. This case is particularly important because it shows that even vertically integrated structures do not automatically insulate a company from regulatory exposure when forced labor indicators are identified.
Denim and Beyond LLC rounds out the competitive picture as an importer and provider of denim jeans, including lines associated with Levi Strauss and Banana Republic, handling U.S. distribution and import logistics. Its role reflects the importance of intermediary distribution, import execution, and category specialization within a fragmented market.
Taken together, these profiles show that competitive advantage in denim jeans increasingly depends on more than cost efficiency. Brand trust, product differentiation, transparency, compliance readiness, and sourcing flexibility all influence which firms can sustain margin and share as the market evolves.
Operational Realities: Cost, Compliance, and Trade Exposure
For 2026 planning, three overlapping pressures deserve particular attention: raw material cost, trade policy, and compliance enforcement. Each can independently affect margin, but together they can reshape sourcing economics and product pricing strategies.
Denim Market
On raw materials, cotton cost expectations are moving higher, with a projected price of up to 1.75 USD per kilogram in 2026 and a 2.9 percent increase from earlier forecasts. This sits against a global production contraction of up to 2 percent during the 2025 to 2026 season. For denim manufacturers and brands, that combination can translate into tighter input availability, more volatile purchase timing, and greater pressure on fabric negotiation strategies. Companies that depend heavily on conventional cotton may need to evaluate hedging approaches, alternative fiber blends, or supplier relationships that provide more stable access.
On trade policy, the potential for elevated baseline tariffs on imports from key sourcing countries creates uncertainty for cost modeling. Tariff exposure on denim jeans imports from Vietnam and Turkey could reach potential baseline rates of 46 percent and 10 percent respectively, depending on 2025 policy changes and any 90-day pauses. Even when pauses or negotiations modify the final outcome, the mere presence of such risk forces companies to rethink lead times, country mix, inventory positioning, and scenario-based pricing.
On compliance, the November 2025 Withhold Release Order directed at Firemount Group Ltd. is a clear signal that enforcement can interrupt supply and damage supplier credibility. The order directed detention of garments, textiles, and apparel manufactured in Mauritius due to indicators of forced labor. For brands and distributors, this reinforces the need for robust supplier due diligence, traceability, and rapid response capabilities when regulatory actions occur. It also illustrates why transparency tools and documented supply chain details are increasingly part of competitive positioning rather than optional ESG narrative.
These dynamics are not abstract. They affect cost-to-serve, product availability, launch timing, and the credibility of sustainability and sourcing claims. The study incorporates these factors so that decision-makers can assess them as part of integrated strategy rather than as isolated external events.
Implications for Strategic Planning
The most effective use of this research is to connect market structure with operational choices. The data points to a market that is growing, but not uniformly, and not without cost and risk. Participants that succeed in 2026 and beyond are likely to be those that can balance several priorities at once: protect margin against input and trade pressures, differentiate through product and sustainability credibility, and maintain sourcing flexibility without weakening compliance standards.
That balance requires granular understanding. It is not enough to know that the market is expanding from 170.0 million USD in 2025 toward 252.0 million USD in 2032. Leaders also need to understand how segmentation behavior, competitive models, and regulatory exposure interact in practice. The report is designed to provide that connecting tissue, helping teams move from awareness to action.
Denim Jeans Market
Get the Full Intelligence
This overview reveals the strategic shape of the denim jeans market and why it matters for 2026 decision-making, but the full study contains the deeper analysis, segmentation logic, competitive detail, and operational interpretation needed for execution. The complete report provides the structured market framework, participant profiles, and context-driven implications that support sourcing strategy, category planning, risk management, and investment prioritization.
To access the full market research and the detailed intelligence behind these insights, visit the PW Consulting report page and obtain the complete Denim Jeans Market study.
For detailed analysis of this topic, please visit the official page: Denim Jeans Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com