

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Gate Bipolar Transistors STATCOM Market Hits $215M in 2025, 3x to $345M by 2032 at 6.98% CAGR

Strategic Intelligence for the Gate Bipolar Transistor STATCOM Market: Navigating the 2026–2032 Growth Arc
The global power grid is undergoing a structural transformation. As renewable penetration accelerates and transmission networks face heightened stability demands, the need for fast-acting reactive power compensation has moved from niche engineering requirement to central grid modernization imperative. At the heart of this shift lies the Gate Bipolar Transistor (GBT)-based STATCOM market. PW Consulting’s latest research report delivers a comprehensive, data-grounded assessment of this sector, covering historical performance from 2020 through 2025 and projecting forward across the 2026–2032 forecast horizon. For executives, procurement leaders, and technology strategists, the report serves as a decision-grade compass rather than a retrospective summary.
Why the 2026 Baseline Matters Now
Market participants often treat forecast years as abstract timelines. In reality, 2026 represents the first full operational cycle following a series of regulatory, technological, and infrastructural inflection points that will dictate competitive positioning for the remainder of the decade. The market closed 2025 at a valuation of 215.0 million USD, building on a consistent expansion trajectory that began at 163.15 million USD in 2020. This five-year historical window captures the early scaling phase of IGBT-driven static compensators as utilities and independent power producers moved beyond pilot deployments into standardized grid-edge integration.
Looking ahead, the forecast period projects a compound annual growth rate of 6.98 percent, with the market expected to reach 231.71 million USD in 2026 and continue its upward path toward 344.8 million USD by 2032. These figures are not merely top-line projections; they reflect an underlying shift in how grid operators prioritize voltage support, harmonic mitigation, and dynamic reactive power injection. For companies evaluating product roadmaps, capacity investments, or regional market entry, understanding the velocity and composition of this growth is essential. PW Consulting’s analysis isolates the structural drivers behind this trajectory while deliberately withholding granular segmentation breakdowns, ensuring that only stakeholders who engage with the full study can access the precise regional, application, and type-level intelligence required for tactical execution.
Market Structure and Demand Vectors
The STATCOM landscape is fundamentally shaped by voltage class, end-use application, and geographic deployment patterns. High Voltage STATCOM configurations continue to dominate total market value, reflecting the scale of transmission-level grid reinforcement projects and the technical requirements of large-scale renewable interconnection. Low Voltage STATCOM solutions, while smaller in aggregate revenue contribution, represent a strategically distinct segment driven by industrial microgrids, data center power quality upgrades, and localized distribution network stability initiatives.
IGBT Market
From an application perspective, renewable energy integration stands as the primary demand engine. The necessity for STATCOM systems to deliver voltage support with IGBT response times in the 1-to-5 millisecond range has become a defining performance criterion, as documented in recent grid integration research. Electric utilities form the second major demand pillar, leveraging GBT-based compensators for transmission congestion management, fault ride-through enhancement, and compliance with evolving harmonic distortion limits. Industrial and manufacturing sectors, along with specialized use cases in infrastructure and commercial power conditioning, complete the application mosaic, each imposing distinct reliability, scaling, and interface requirements on equipment manufacturers.
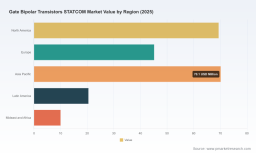
Regional deployment patterns reveal a highly distributed demand footprint, with mature grid modernization programs in established markets operating alongside rapid capacity build-out in emerging transmission corridors. This geographic diversification means that no single regional strategy can capture the full growth opportunity. Companies must evaluate supply chain localization, service network density, and regulatory alignment across multiple jurisdictions simultaneously. The complete regional and application-level quantification, including precise share distributions and revenue allocations, is reserved for the full report to preserve the analytical depth required for accurate market entry and resource allocation planning.
Regulatory Tailwinds and Technical Standardization
Policy and standards frameworks are no longer peripheral considerations; they actively shape procurement cycles, technology selection, and competitive barriers to entry. In Europe, EU Directive 2019/944 mandates market-based, transparent procurement of reactive power using STATCOM devices, forcing utilities and system operators to formalize sourcing processes and evaluate suppliers against structured performance and pricing criteria. Parallel developments in Germany point toward a reactive power market expected to commence in the early-to-mid 2025 window, requiring transmission system operator tenders specifically structured around STATCOM procurement to meet grid stability obligations.
On the technical side, IEEE Std 519-2014 and the updated IEEE Std 519-2025 continue to govern harmonic limits for IGBT-based STATCOM installations, establishing compliance benchmarks that directly influence converter topology selection, filtering architecture, and long-term operational acceptance. Standardization activity also extends to device-level comparisons, with recent IEEE Power & Energy Society analysis highlighting that T-STATCOM converter structures utilizing 3.3 kV silicon IGBTs deliver measurable overload handling advantages over silicon carbide MOSFET alternatives in high-voltage applications. These technical nuances have direct implications for product positioning, bill-of-materials strategy, and performance validation protocols.
Regulatory and standardization trajectories are accelerating procurement formalization, but they also introduce compliance complexity that favors organizations with robust engineering documentation, certification pathways, and tender response capabilities. PW Consulting’s report maps these regulatory shifts against demand timelines, helping clients anticipate tender windows, align product certifications, and structure proposal architectures that meet both technical specifications and procurement transparency requirements.
Competitive Landscape and Strategic Positioning
The Gate Bipolar Transistor STATCOM market operates with a moderately fragmented but highly capable participant base. The combined market share of the top three competitors sits at 24.6 percent, while the top five reach 26.2 percent, indicating that no single entity commands decisive pricing power and that technological differentiation, regional execution, and service integration remain the primary competitive levers. This concentration profile rewards companies that can combine reliable converter performance with localized project delivery and long-term grid operator relationships.
A diverse set of established and regional players defines the current competitive fabric. Siemens Energy brings comprehensive transmission-grade power electronics expertise and a structured approach to grid integration projects across Europe and global utility markets. ABB Ltd continues to leverage its broad electrification portfolio, emphasizing scalable STATCOM architectures and digital grid management interfaces. Rongxin Power Electronic Co., Ltd and Sieyuan Electric Co., Ltd represent China-based manufacturing capabilities that have expanded their footprint through cost-competitive product lines and growing international project participation. Hitachi Energy and Mitsubishi Electric Corporation contribute advanced converter technology and strong regional execution in Japan and selected export markets, while GE Vernova applies its grid solutions heritage to utility-scale reactive power infrastructure in North America and beyond.
Ingeteam adds specialized power conversion expertise with a focus on renewable-aligned grid support applications, and American Superconductor (AMSC) brings differentiated high-performance grid technology positioning. Hyosung Heavy Industries offers strong heavy electrical equipment integration capabilities, particularly relevant for combined transformer-converter STATCOM deployments. S&C Electric Company maintains a recognized presence in distribution-level grid protection and compensation solutions, while Fuji Electric Co., Ltd contributes mature power semiconductor and industrial control engineering to the competitive mix.
Competitive advantage in this environment rarely derives from volume alone. It emerges from the intersection of converter reliability, harmonic compliance documentation, turnaround speed on tender responses, service and maintenance coverage, and the ability to tailor voltage-class solutions to specific grid operator requirements. The full report provides detailed company-level strategic profiles, technology positioning assessments, and competitive move tracking, while withholding precise revenue allocations and share calculations to preserve the analytical exclusivity required for strategic planning.
What the Report Delivers for 2026 Decision-Making
PW Consulting’s Gate Bipolar Transistor STATCOM Market research is structured to support concrete executive and operational decisions rather than remain a descriptive market summary. The study integrates historical performance tracking, forward-looking valuation projections, segmentation mapping, competitive benchmarking, and regulatory-standards impact analysis into a unified decision framework. Readers gain access to a structured assessment of how demand vectors are evolving across voltage classes, application sectors, and regional deployment zones, alongside an evaluation of the procurement, compliance, and technical standardization factors that will shape supplier selection over the forecast period.
The report also provides operational intelligence relevant to product planning, capacity allocation, partnership strategy, and tender positioning. By aligning market trajectory data with technology performance criteria and regulatory timelines, the analysis enables clients to identify which segments offer the most defensible growth pathways, where service and localization investments will generate the strongest returns, and how to structure proposals in markets moving toward formalized reactive power procurement. To maintain the integrity of these insights for actionable use, core segmentation percentages, detailed regional and application-level valuations, and exact competitor revenue breakdowns are reserved for the complete study.
Gate Bipolar Transistors STATCOM Market
Strategic Recommendations for Market Participants
- Align product development and certification roadmaps with IEEE harmonic compliance expectations and emerging regional reactive power procurement mandates, ensuring that documentation and validation protocols are ready before tender cycles intensify.
- Evaluate high-voltage and low-voltage portfolio positioning as distinct strategic tracks, since each addresses different procurement authorities, technical specifications, and competitive dynamics.
- Prioritize regional execution capability over generalized global presence, focusing service network density, local engineering support, and supply chain responsiveness in markets where grid modernization budgets are accelerating.
- Use the moderately consolidated competitive structure as an opportunity to differentiate through performance reliability, tender response quality, and lifecycle service agreements rather than competing solely on initial equipment pricing.
- Incorporate 1-to-5 millisecond IGBT response performance and overload handling characteristics into product messaging and technical proposals, as these parameters are increasingly central to grid operator evaluation criteria for renewable integration and transmission support applications.
Conclusion: Securing the Intelligence Edge
The Gate Bipolar Transistor STATCOM market is entering a phase where growth is not only sustained but structurally reinforced by grid stability requirements, renewable integration acceleration, and formalized reactive power procurement frameworks. The historical expansion from 2020 through 2025 establishes a credible demand foundation, while the 2026–2032 forecast period points to continued value creation for organizations that can navigate technical standardization, regional procurement variation, and competitive differentiation with precision.
PW Consulting’s full market research report provides the depth, segmentation clarity, competitive profiling, and regulatory-aligned analysis required to convert this macro trajectory into executable strategy. To access the complete dataset, detailed segmentation valuations, regional and application-level breakdowns, and in-depth company strategic assessments, stakeholders are encouraged to visit the source report page and obtain the full intelligence package. In a market where timing, compliance readiness, and segment selection determine competitive outcomes, comprehensive and current intelligence is not optional. It is the foundation of effective 2026 decision-making.
For detailed analysis of this topic, please visit the official page: Gate Bipolar Transistors STATCOM Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com