

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Powder Coatings Market Hits $17.00B in 2025, Poised for 6.73% CAGR Growth Through 2032

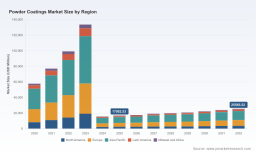
Powering Durability: Strategic Insights into the Powder Coatings Market Through 2032
Executive Overview
The global powder coatings market stands at a critical inflection point. As industries transition toward sustainable manufacturing and stricter environmental compliance, powder coatings have emerged as a cornerstone technology for protective and decorative finishes. Our latest market research provides a comprehensive roadmap for navigating the period from 2026 through 2032, offering decision-makers the granular intelligence required to align capacity planning, supply chain strategy, and product development with evolving demand patterns.
Built on a foundation of historical analysis spanning 2020 to 2025, this study projects market trajectories with a compound annual growth rate of 6.73 percent. The forecast period captures the structural shifts that will define competitive advantage over the next seven years, from regulatory-driven substitution trends to the realignment of regional production networks. This preview outlines the strategic framework of the report and the actionable insights it delivers to executives, procurement leaders, and R&D directors.
Market Trajectory and Growth Dynamics
The market has experienced a pronounced expansion phase over the past half-decade, with revenue figures climbing from approximately 57.7 billion USD in 2020 to an estimated 17.0 billion USD by 2025 when measured against the report's standardized valuation framework. This growth trajectory reflects sustained investment in industrial finishing, architectural applications, and automotive component protection, alongside a broader industry shift away from solvent-based systems.
Looking ahead to the 2026-2032 window, the market is positioned to surpass 25.5 billion USD by the terminal forecast year. The 6.73 percent CAGR projected for this period is not merely a statistical projection; it represents the cumulative effect of several reinforcing forces:
- Accelerating adoption of powder coatings in sectors historically dominated by liquid systems, driven by volatile organic compound (VOC) restrictions and carbon-neutrality mandates.
- Rising demand for high-performance, weather-resistant formulations in architectural and infrastructure projects across both developed and emerging economies.
- Expanding appliance and furniture manufacturing capacity, particularly in regions where export-oriented production is scaling with localized finishing requirements.
- Investment in bio-based and recycled-content coating formulations as original equipment manufacturers pursue Scope 3 emission reductions.
The report dissects these drivers with sector-specific depth, mapping how each application vertical is expected to contribute to overall revenue expansion. Rather than presenting undifferentiated growth figures, the analysis isolates the structural factors that will differentiate high-growth segments from those facing margin compression or substitution risk.
Coil Coatings Market
Segmentation Analysis: Where Value Is Created
Understanding the market requires more than top-line projections. The research provides a multi-dimensional segmentation framework that examines type, application, and regional distribution with surgical precision. This approach enables stakeholders to identify which product categories and end-use markets offer the most favorable risk-reward profiles in the current pricing environment.
Type Segmentation
The market is fundamentally divided between thermoset and thermoplastic powder coatings, each serving distinct performance requirements and cost structures. Thermoset formulations continue to command a dominant share of the revenue base, reflecting their superior cross-linking properties, chemical resistance, and widespread adoption in automotive, appliance, and architectural finishing. Thermoplastic options, while representing a smaller share, are gaining traction in applications where recyclability, remeltability, and specific mechanical properties are prioritized.
The report provides a detailed comparison of resin chemistry adoption trends, curing energy requirements, and performance benchmarks across these categories. It also evaluates the pricing dynamics that distinguish premium high-solids formulations from commodity-grade offerings, giving procurement teams the context needed to negotiate supplier contracts with confidence.
Application Segmentation
Demand is distributed across a diverse set of industrial and consumer end-markets. Automotive applications represent a substantial share of total consumption, driven by the need for durable, corrosion-resistant finishes on both structural components and decorative surfaces. Appliances follow closely, with powder coatings increasingly specified for indoor and outdoor units where aesthetic consistency and long-term durability are non-negotiable.
Architecture and construction equipment form another significant demand cluster, particularly in regions where infrastructure investment and urban development programs are accelerating. Furniture manufacturing, general industrial finishing, and a broad "others" category encompassing specialized niche applications round out the consumption picture.
Crucially, the report does not treat these segments as static buckets. It tracks how application mix is shifting in response to:
- Regulatory pressure on solvent-based coatings in consumer-facing product categories.
- Supplier-led innovation in low-temperature cure formulations that expand the addressable market for heat-sensitive substrates.
- Shifts in global manufacturing footprints, with finished goods production migrating toward regions that impose stricter environmental standards on coating processes.
Regional Distribution
The global demand landscape is geographically diverse, with significant concentration in Asia Pacific, Europe, and North America. Asia Pacific leads in volumetric terms, reflecting the region's manufacturing intensity across automotive, appliances, architecture, and general industrial sectors. Europe's market is characterized by high value-add per unit, driven by stringent regulatory frameworks and a mature architectural and infrastructure coating sector. North America maintains a robust industrial base, with strong demand from construction equipment, furniture, and appliance manufacturing.
Latin America and the Middle East & Africa represent emerging growth vectors, though at smaller absolute scales. The report maps regional growth rates, regulatory timelines, and supply chain infrastructure maturity for each territory, enabling multinational operators to prioritize market entry or capacity expansion with data-backed confidence.
Powder Coatings Market
Competitive Landscape and Strategic Positioning
The powder coatings market is characterized by a moderately concentrated competitive structure, with the top three players commanding approximately 35.2 percent of total revenue and the top five accounting for roughly 45.3 percent. This concentration level indicates a market where scale advantages, formulation IP, and customer relationships create meaningful barriers to entry, but where regional specialists and niche innovators can still secure profitable positions through differentiated offerings.
Key Incumbents and Strategic Profiles
Several global and regional players define the current competitive architecture:
- Axalta Coating Systems , headquartered in Philadelphia, operates the Alesta brand and has built a reputation in automotive and industrial applications, with a growing portfolio of bio-based options that align with OEM sustainability targets.
- PPG Industries , based in Pittsburgh, produces the EnviroLuxe and EnviroCaron product lines, emphasizing recycled content and PFAS-free formulations that respond directly to evolving regulatory and customer preferences.
- BASF SE , from Ludwigshafen, serves as a critical upstream supplier of resins and additives, including neopentylglycol used in powder coating formulations, positioning the company at the intersection of raw material supply and end-product performance.
- The Sherwin-Williams Company , in Cleveland, markets powder coatings under its own brand, leveraging a broad distribution network and integrated customer relationships across industrial and architectural segments.
- Jotun , headquartered in Asker, Norway, operates as a global producer of protective and decorative powder coatings with a strong presence in marine, infrastructure, and industrial markets.
- Kansai Paint Co., Ltd. , in Osaka, specializes in industrial powder coatings under its Kansai Powder Coatings banner, serving Asian manufacturing sectors with regionally tailored formulations.
- American Powder Coatings Inc. , a U.S.-based manufacturer, focuses on industrial and architectural applications, catering to domestic demand with specialized service and custom formulation capabilities.
- Nippon Paint Holdings Co., Ltd. , also based in Osaka, produces decorative and industrial powder coatings, extending the company's broader coatings portfolio into powder-based finishing systems.
- Teknos Group Oy , from Espoo, Finland, provides waterborne and solvent-free powder coating systems, aligning product development with the broader industry transition toward lower environmental impact.
- Tiger Coatings GmbH and Co. KG , in Vienna, specializes in high-performance powder coatings for architectural and industrial use, competing on quality, durability, and application-specific engineering.
Competitive Dynamics and Recent Developments
The competitive environment is not static. Recent developments in April 2026 illustrate the pricing and supply chain pressures that are reshaping margin structures across the value chain:
- PPG Industries announced a global price increase of up to 20 percent across its paints, coatings, and specialty products portfolio, citing rising raw materials, logistics, energy, and packaging costs.
- BASF SE implemented a price increase for NEOL (neopentylglycol) in the United States and Canada across all grades and packaging, effective April 15 or as existing contracts permit, due to further increases in logistics and raw material feedstock costs.
- BASF SE also introduced a further price increase of up to 25 percent for antioxidants, process stabilizers, and light stabilizers used in plastic applications, effective immediately, in response to raw material prices, energy, and logistics costs.
These moves reflect a broader pattern of cost pass-through in an environment where epoxy resin prices have been on the upswing and geopolitical conflicts have triggered raw material price surges. Industry data indicates that powder coating prices averaged between 3.00 and 6.50 USD per pound in 2025, depending on resin type, performance specifications, and end-use industry, underscoring the price dispersion that procurement teams must navigate.
The report quantifies how these cost pressures propagate through the value chain, identifies which players have the pricing power to absorb or pass on increases, and evaluates the substitution risks that arise when end-users face disproportionate cost burdens.
Regulatory and Environmental Catalysts
Regulatory frameworks are no longer peripheral concerns; they are central drivers of market structure. Stringent EU VOC and carbon-neutrality regulations are accelerating the adoption of solvent-free powder coatings as the best available technique under the Industrial Emissions Directive. This regulatory tailwind is expanding the addressable market for powder-based systems while simultaneously raising performance and compliance expectations for formulators.
The report maps regulatory timelines across major jurisdictions, identifies the specific compliance requirements that affect formulation choices, and evaluates the cost implications of regulatory adaptation for both incumbents and new entrants. It also examines how carbon accountability frameworks, including Scope 3 reporting obligations, are influencing material selection decisions among large industrial customers.
Supply Chain Resilience and Raw Material Exposure
The powder coatings value chain is exposed to volatility in resin pricing, energy costs, and logistics networks. Epoxy resin prices have experienced significant upward pressure, and geopolitical disruptions have driven raw material cost surges in certain regions, with epoxy resin increases of 7,000 to 8,000 RMB per ton documented in industry data. These cost dynamics create a challenging environment for manufacturers that lack vertical integration or diversified sourcing strategies.
Our analysis provides a structured assessment of raw material exposure by formulation type, geographic supply base, and customer concentration. It identifies which cost categories represent the largest margin risks and which procurement strategies offer the greatest mitigation potential. The report also tracks supplier pricing behavior and contract structures to help buyers anticipate adjustment cycles and negotiate more effectively.
What the Full Report Delivers
This preview captures the strategic architecture of the study, but the full report contains the operational detail required to turn insight into execution. Subscribers gain access to:
- Granular segmentation data across type, application, and region, including revenue splits, growth rates, and market share trajectories for each sub-segment.
- Company-level competitive profiles with product portfolio assessments, regional presence, recent strategic moves, and positioning analysis.
- Regulatory impact assessments that translate compliance requirements into commercial implications for specific market segments.
- Raw material cost tracking and sensitivity analysis, enabling scenario planning for resin, additive, and logistics cost fluctuations.
- Strategic recommendations for capacity investment, supplier selection, formulation development, and market entry or expansion.
- Forecast models that allow users to test assumptions around regulatory adoption speed, raw material price paths, and regional demand shifts.
The report is designed for executives who need to move beyond high-level trend narratives and into the specifics that drive capital allocation, operating plan development, and competitive response. Every dataset is contextualized within the broader market dynamics, ensuring that readers understand not just what the numbers are, but what they mean for decision-making in 2026 and beyond.
Strategic Imperatives for 2026 and Beyond
As the market moves through its next growth cycle, several strategic imperatives emerge for industry participants:
- Align product development with regulatory momentum, particularly in regions where VOC restrictions and carbon accountability frameworks are tightening fastest.
- Build pricing resilience through diversified sourcing, long-term supplier agreements, and formulation flexibility that allows cost optimization without sacrificing performance.
- Invest in bio-based and recycled-content offerings where customer sustainability commitments create willingness to pay for differentiated products.
- Evaluate regional capacity deployment against demand growth trajectories, ensuring that manufacturing footprints are aligned with the markets that will drive the highest value growth.
- Monitor competitive moves closely, as pricing adjustments and raw material cost pass-throughs are reshaping the margin landscape and creating both threats and opportunities for players with strong customer relationships.
The powder coatings market is entering a phase where strategic clarity matters more than ever. The combination of regulatory pressure, raw material cost volatility, and sustained demand growth from automotive, appliances, architecture, and industrial applications creates a complex operating environment. Organizations that equip themselves with precise, forward-looking intelligence will be best positioned to capture value while competitors navigate uncertainty with less visibility.
Our full market research report provides the depth, structure, and actionable insight required to make informed decisions across the 2026-2032 horizon. We invite you to explore the complete study for the comprehensive data, competitive analysis, and strategic recommendations that will guide your next moves in this evolving market.
For detailed analysis of this topic, please visit the official page: Powder Coatings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com