

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Industrial Gases Market to Reach $167.3B by 2032, Driven by 6.5% CAGR

Navigating the Industrial Gases Landscape: Strategic Intelligence for 2026 and Beyond
The industrial gases sector stands at a critical inflection point. As global manufacturing footprints shift, energy transition mandates accelerate, and semiconductor supply chains reconfigure, the demand for oxygen, nitrogen, hydrogen, and specialty gases is evolving from a steady utility market into a strategically contested arena. PW Consulting's latest Industrial Gases Market research report offers decision-makers a comprehensive, data-driven roadmap to navigate this transformation. Covering historical performance from 2020 through 2025 and extending detailed forecasts to 2032, this analysis equips executives, investors, and supply chain leaders with the intelligence required to price risk, allocate capital, and secure long-term competitive advantage.
Macro Trajectory and Forecast Architecture
Over the past half-decade, the industrial gases market has demonstrated consistent expansion, moving from approximately 80.5 billion USD in 2020 to an estimated 108.0 billion USD by the 2025 base year. This trajectory reflects not only post-pandemic industrial recovery but also structural demand shifts driven by electronics manufacturing, clean energy infrastructure, and advanced materials processing. Looking forward, the market is projected to reach 112.85 billion USD in 2026, with growth compounding steadily through the forecast horizon to exceed 167.3 billion USD by 2032. The implied compound annual growth rate of 6.5 percent positions the sector as a resilient, above-average growth segment within broader industrial supply chains.
Such macroeconomic momentum, however, masks significant underlying complexity. Growth is not uniform across geographies, product categories, or end-use verticals. Strategic planners must understand where volume accumulates, which applications command premium pricing, and how regional energy economics reshape cost structures. Our report deconstructs these layers without oversimplifying them, providing scenario-based modeling that accounts for energy price volatility, capital expenditure cycles, and regulatory shifts that will define the 2026 to 2032 window.
Demand Drivers and Structural Shifts
Several interconnected forces are reshaping procurement patterns and investment priorities across the industrial gases ecosystem. First, the accelerating deployment of advanced semiconductor fabrication facilities has created sustained demand for ultra-high-purity nitrogen and specialty gas mixtures, with major supply agreements already signaling multi-year capacity commitments. Second, the global push toward decarbonization is elevating hydrogen from a niche byproduct stream to a central pillar of industrial strategy, particularly in refining, ammonia synthesis, and emerging clean mobility applications. Third, healthcare and food & beverage sectors continue to drive steady consumption of medical-grade oxygen, carbon dioxide, and argon, though margin profiles in these segments differ markedly from heavy industrial contracts.
Simultaneously, the cost environment remains a decisive factor. Electricity consumption for cryogenic air separation represents a major operating expense, and fluctuations in grid pricing directly influence producer margins. Natural gas continues to serve as the primary feedstock for many production processes, including air separation and hydrogen generation, making energy arbitrage and regional gas pricing critical variables in site selection and contract structuring. Inflationary pressures and energy cost volatility have already perturbed revenue and earnings trajectories for leading producers, while workforce dynamics have begun to stabilize, with industry headcount projections settling near 20,000 by the end of 2026. Understanding how these macroeconomic inputs propagate through pricing models, contract duration negotiations, and capital allocation decisions is essential for 2026 planning.
Competitive Landscape and Strategic Positioning
The industrial gases market is characterized by a moderately concentrated structure, with the top three players commanding approximately 55 percent of aggregate revenue and the top five entities controlling roughly 65 percent. This concentration reflects the capital intensity of production infrastructure, the value of long-term supply agreements, and the operational expertise required to maintain stringent purity and safety standards. Yet the competitive field extends beyond the largest multinational incumbents, encompassing regional specialists, integrated chemical producers, and technology-focused equipment providers that collectively shape pricing dynamics, innovation velocity, and service-level expectations.
Industrial Gases Market
Leading global providers continue to anchor the market through diversified gas portfolios and deep integration with manufacturing, chemicals, and energy sectors. Firms headquartered in France, the United States, and Ireland have historically led in scale, leveraging air separation technology, cryogenic equipment capabilities, and extensive pipeline networks to secure long-term contractual relationships. Specialized producers in Germany and Japan complement this landscape by emphasizing nitrogen, oxygen, and hydrogen production technologies tailored to specific industrial processes, while North American and Japanese manufacturers provide critical supply for electronics, healthcare, and food processing applications. Integrated chemical and energy companies also play a meaningful role, particularly where carbon dioxide and hydrogen emerge as value-added byproducts of larger processing operations.
Recent Strategic Moves and Capacity Allocation
The competitive rhythm has intensified through a series of high-profile agreements and infrastructure investments that illuminate where capital and demand are converging. In mid-2025, major suppliers executed long-term industrial gas supply agreements with leading semiconductor manufacturers, signaling multi-year commitments to support new production facilities and expanded wafer fabrication capacity. These contracts underscore the strategic importance of reliable, ultra-high-purity gas delivery in an industry where downtime carries extraordinary cost.
Simultaneously, decarbonization has moved from policy aspiration to executable project pipeline. A landmark initiative launched in early 2025 committed over one billion euros to electrolyzer units supporting green hydrogen production, reflecting a decisive shift toward low-carbon gas supply chains and signaling how traditional producers are repositioning their portfolios. In the second half of the year, additional capacity expansions were announced, including significant manufacturing and logistics center investments designed to strengthen regional supply resilience and reduce lead times for industrial customers. These moves illustrate a broader pattern: incumbents are simultaneously defending core-volume relationships in steel, chemicals, and manufacturing while building optionality in clean energy and high-purity electronics supply.
Regulatory, Operational, and Cost Dynamics
No strategic assessment of the industrial gases market is complete without confronting the regulatory and operational realities that define commercial viability. Purity and safety standards enforced by regulatory bodies such as the FDA and EMA impose specialized equipment requirements and rigorous quality control protocols, particularly for healthcare and electronics applications. Compliance is not a peripheral concern; it dictates capital intensity, validation timelines, and the cost of market entry for new facilities or product grades.
On the environmental policy front, carbon pricing mechanisms and emissions trading frameworks are beginning to reshape the economics of outsourced hydrogen and other gas supply. Benchmark reductions under evolving European regulatory structures are projected to affect free allowance distributions for significant hydrogen sales volumes, introducing new variability into pricing models and contract structures. Producers and offtakers alike must anticipate how these mechanisms will influence net costs, pass-through provisions, and the relative competitiveness of low-carbon versus conventional supply pathways.
Operationally, electricity consumption remains the dominant cost driver for cryogenic air separation plants, making energy procurement strategy a core component of margin management. Natural gas feedstock availability and pricing further influence production economics, particularly in regions where pipeline infrastructure and regional pricing dynamics diverge. Meanwhile, labor and overhead costs have experienced inflationary pressure, though industry employment levels are expected to stabilize through 2026 as automation and process optimization offset headcount expansion. Together, these dynamics create a complex optimization problem for producers seeking to balance reliability, purity, cost, and sustainability commitments.
What the Report Delivers for 2026 Decision-Making
PW Consulting's Industrial Gases Market research is designed to convert these macro trends, competitive signals, and operational constraints into actionable strategy. The report goes beyond high-level sizing to provide a detailed dissection of market architecture, including the following core components:
- Historical performance analysis spanning 2020 through 2025, establishing baseline demand patterns, pricing environments, and capacity utilization trends that inform forward-looking assumptions.
- Forecasting frameworks extending to 2032, built on scenario modeling that captures energy cost variability, regulatory evolution, and demand elasticity across major industrial verticals.
- Competitive profiling of leading global and regional players, including strategic positioning, technology focus areas, and recent contractual and investment activity that signal future market direction.
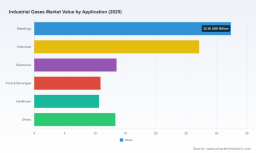
- Segment-level intelligence that explains how demand distributes across product categories and end-use applications without reducing the picture to simplistic share splits, enabling precise go-to-market and pricing strategy development.
- Regional demand assessment that contextualizes growth opportunities and cost dynamics across key markets, helping planners calibrate inventory, logistics, and local partnership strategies.
- Operational and regulatory deep dives covering purity standards, emissions framework implications, energy and feedstock cost exposure, and labor market trends that directly affect margin structures and capital planning.
Each section is engineered to support concrete decisions: whether to enter or expand in a specific geography, how to structure long-term supply agreements under volatile energy conditions, where to prioritize capital allocation for capacity upgrades, and how to anticipate regulatory cost pass-through in hydrogen and specialty gas contracts. The analysis is anchored in rigorous data handling and contextualized with industry-on-the-ground developments, ensuring that executives receive not just numbers, but interpretable intelligence.
Why This Research Matters Now
The 2026 planning cycle demands more than retrospective review. Semiconductor capacity build-outs, decarbonization project pipelines, and evolving emissions frameworks are already reshaping contractual expectations and cost baselines. Producers, offtakers, investors, and equipment suppliers must simultaneously manage near-term margin pressures while positioning for multi-year demand shifts. In this environment, the difference between reactive adjustment and proactive strategy lies in access to integrated, forward-looking intelligence that ties market sizing to competitive behavior, regulatory trajectory, and operational cost drivers.
This report provides that integration. It identifies where growth is structurally supported versus cyclically sensitive, which segments face tightening purity and compliance requirements, and how leading firms are reallocating capital to capture both traditional volume and emerging clean-energy demand. By connecting these threads, the analysis enables decision-makers to prioritize initiatives with the highest strategic return and to avoid blind spots that can erode competitiveness over the forecast horizon.
Moving from Insight to Action
The industrial gases market will not be defined solely by aggregate growth figures. It will be shaped by who secures long-term supply relationships in high-purity electronics, who executes decarbonization projects on schedule and on budget, and who manages energy and feedstock exposure with discipline. The 6.5 percent compound annual growth trajectory and the expansion from roughly 108.0 billion USD in 2025 to over 167.3 billion USD by 2032 create a substantial opportunity set, but capturing it requires granular understanding of segment dynamics, regional cost structures, and competitive intent.
Medical Gases Market
PW Consulting's full Industrial Gases Market report delivers the depth required to act confidently in 2026 and beyond. To access the complete segmentation breakdowns, company-level strategic profiles, scenario forecasts, and operational cost analysis, visit the official report page and download the full intelligence package. Equip your team with the market clarity needed to negotiate from strength, allocate capital with precision, and build resilience into your industrial gas strategy for the remainder of the decade.
For detailed analysis of this topic, please visit the official page: Industrial Gases Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com