

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Encrypted USB Market Hits $200M in 2025, Poised for 7.5% CAGR Growth Through 2032

Strategic Imperatives in the Encrypted USB Flash Drives Market: A 2026 Outlook
In an era where data breaches can cripple reputations and incur billions in fines, the humble USB flash drive has evolved from a simple storage accessory into a critical endpoint security asset. As organizations navigate the complex intersection of remote work, stringent regulatory compliance, and escalating cyber threats, the demand for secure removable media is no longer optional—it is a foundational requirement for operational resilience. PW Consulting has released a comprehensive market research report detailing the trajectory of the Encrypted USB Flash Drives Market, offering vital intelligence for stakeholders looking to secure their data infrastructure through 2032.
This market has demonstrated remarkable resilience and growth over the past half-decade. Historical analysis from 2020 to 2025 reveals a consistent upward trend, with the overall market valuation climbing from 120.0 million USD to a projected 200.0 million USD by the base year. This trajectory underscores a shifting paradigm where security is prioritized over convenience. Looking forward, the forecast period from 2026 to 2032 suggests that this momentum will not only continue but accelerate, driven by tighter government mandates and enterprise security protocols.
Market Trajectory and Growth Dynamics
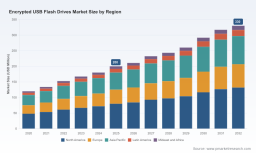
The financial outlook for this sector is robust. Starting from a valuation of 210.95 million USD in 2026, the market is expected to expand significantly, reaching 330.0 million USD by 2032. This growth is anchored by a compound annual growth rate (CAGR) of 7.5 percent over the forecast period. Such performance indicates that investment in encrypted storage solutions is becoming a standard line item in IT security budgets rather than a niche expenditure. The expansion is not merely a function of price increases but reflects a deepening penetration of secure storage solutions across diverse industry verticals.
Several key factors are fueling this expansion. First, the proliferation of remote and hybrid work models has decentralized data storage, increasing the risk surface associated with removable media. Employees moving between secure corporate networks and public spaces require portable storage that does not become a liability. Second, the regulatory landscape is hardening. Recent updates to state-level security standards, such as the Iowa Removable Storage Device Security Standard effective June 2025, mandate the use of 256-bit AES or stronger encryption for devices storing confidential data. Similarly, NIST SP 800-111 guidelines continue to require self-encrypting USB drives for federal agencies handling sensitive data on removable media.
Furthermore, the transition from FIPS 140-2 to FIPS 140-3 Level 3 validation represents a critical threshold for high-assurance government and defense applications. Cryptographic modules used in encrypted USB flash drives for these sectors must now meet stricter validation criteria, effectively creating a barrier to entry that favors established, compliant manufacturers. This regulatory pressure acts as a tailwind for the market, compelling organizations to upgrade their hardware to meet compliance standards, thereby driving volume and value.
Segmentation and Value Distribution
Understanding where value resides within the market is crucial for strategic positioning. The market is segmented by type, region, and application, each presenting unique opportunities and challenges. In terms of technology type, hardware-encrypted solutions dominate the landscape. This segment reflects a strong market preference for security that is independent of the host operating system. Hardware encryption ensures that data protection is intrinsic to the device, reducing the risk of software vulnerabilities or user error compromising the encryption key. Software encrypted and hybrid options occupy smaller shares, catering to specific use cases where flexibility or cost constraints are prioritized over maximum security assurance.
Geographically, the market reflects mature security infrastructures in certain regions alongside growing adoption in others. North America remains the largest revenue contributor, driven by high enterprise spending on cybersecurity and strict government procurement standards. Europe follows as a significant market, influenced by GDPR compliance requirements and robust public sector procurement. The Asia Pacific region represents a dynamic growth engine, where rapid digital transformation and increasing awareness of data sovereignty are prompting both enterprises and governments to invest in secure storage hardware. Latin America and the Middle East and Africa, while smaller in current valuation, are emerging markets where increased digitization is expected to drive incremental demand.
Application-wise, enterprise use cases capture the largest share of the market. Corporations are increasingly recognizing that data loss prevention strategies must extend to removable media. Government use is the second major pillar, heavily influenced by procurement mandates and defense-related security requirements. Consumer use, while present, remains a smaller fraction of the total revenue, as individual users often prioritize cost and capacity over advanced encryption features unless compelled by specific privacy concerns.
Competitive Landscape and Strategic Positioning
The market is characterized by a high degree of concentration, with the top three companies accounting for approximately 70 percent of market revenue and the top five firms holding around 85 percent. This consolidation suggests that scale, compliance certification, and established distribution channels are significant moats for incumbent players. However, innovation in encryption technology and form factor continues to provide avenues for differentiated positioning.
USB Drive Market
Kingston Technology Company, Inc., headquartered in Fountain Valley, California, stands as a leader in the hardware-encrypted space. Their IronKey series, including the Locker+ 50 G2 and D500S, exemplifies the market standard with 256-bit AES XTS hardware encryption and FIPS 140-3 Level 3 validation. In March 2026, Kingston released the next-generation IronKey Locker+ 50 G2, reinforcing their commitment to enterprise-grade security features and FIPS 197 certification. Earlier, in July 2025, they unveiled the IronKey D500S as the first FIPS 140-3 Level 3 flash drive meeting Trade Agreements Act rules, a critical milestone for government procurement eligibility.
Apricorn, based in Poway, California, specializes in software-free 256-bit AES XTS hardware-encrypted USB flash keys. Their Aegis Secure Key series is renowned for environmental hardening, making them suitable for harsh operational conditions. In May 2026, Apricorn updated the Aegis Secure Key 3 (ASK3) with faster speeds and improved environmental protection, while submitting for FIPS 140-3 Level 3 validation. This focus on ruggedness and pure hardware encryption appeals to sectors like defense, law enforcement, and industrial field operations.
DataLocker Inc. offers a strong value proposition through its Sentry series, which includes FIPS 140-2/3 Level 3 certified encrypted USB flash drives with SafeConsole remote management. Their March 2025 launch of the Sentry ONE drive highlighted capabilities such as remote wipe and multi-certifications including NIST, CSPN, and BSI/BSZ. This emphasis on management software alongside hardware security addresses the enterprise need for centralized control over distributed devices, ensuring compliance with regulations like HIPAA, GDPR, and CMMC.
Other key players further diversify the competitive landscape. Kanguru Solutions provides government-certified 256-bit hardware-encrypted secure USB drives with remote management and endpoint protection. iStorage, based in the United Kingdom, delivers hardware-encrypted drives like the datAshur PRO series, featuring PIN/password protection and FIPS-validated encryption for high-security data transfers. Clevy focuses on hardware-encrypted secure USB drives with advanced encryption and management tools for enterprise data security. Western Digital Corporation, through its SanDisk brand, provides encrypted USB flash drives featuring AES encryption and secure access software, leveraging its broad consumer and enterprise brand recognition to penetrate the secure storage market.
Strategic Implications for Decision Makers
For enterprise leaders, IT security officers, and procurement strategists, the insights contained in this market research extend beyond simple revenue forecasts. The shift toward hardware-encrypted dominance suggests that software-based encryption alone may increasingly fall short of compliance requirements for sensitive data. Organizations must evaluate whether their current portable storage strategies align with the 256-bit AES standards and FIPS 140-3 mandates that are becoming prevalent.
The concentration of market power among the top players indicates that supply chain stability and vendor longevity are critical considerations. Partnering with vendors who have a proven track record of maintaining certifications through regulatory updates is essential. The recent product launches by key competitors highlight a race toward higher performance, better durability, and stricter validation. For instance, the ability to remotely manage and wipe devices, as offered by DataLocker and Kanguru, is becoming a differentiator for enterprises managing large fleets of distributed workers.
Furthermore, the regional dynamics suggest that global organizations must adopt a nuanced approach. While North American and European markets demand strict adherence to local compliance frameworks, the Asia Pacific region may offer growth opportunities for vendors who can balance security with cost-effectiveness and local data sovereignty laws. The report provides a detailed breakdown of these regional nuances, helping stakeholders identify where to allocate resources for maximum impact.
Conclusion and Next Steps
The Encrypted USB Flash Drives Market is at a inflection point where security, compliance, and mobility converge. The projected growth to 330.0 million USD by 2032 is not just a number; it represents a structural change in how organizations handle sensitive data on the move. With regulatory pressures intensifying and cyber threats evolving, the choice of encrypted storage solutions is a strategic decision that impacts risk management, compliance posture, and operational efficiency.
Encrypted USB Flash Drives Market
This executive summary provides a high-level view of the market dynamics, competitive forces, and growth drivers. However, the full depth of the analysis contained in the PW Consulting report offers the granular data necessary to build detailed go-to-market strategies, investment models, and risk assessments. To access the complete segmentation data, detailed competitor profiles, and comprehensive regulatory impact analysis, we invite you to explore the full report. Equip your organization with the intelligence needed to navigate the secure storage landscape with confidence.
For detailed analysis of this topic, please visit the official page: Encrypted USB Flash Drives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com