

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Clinical Mass Spectrometry Market to Hit $2.36B by 2032 with 9.35% CAGR

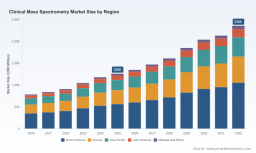
Unlocking Precision: A Strategic Roadmap for the Clinical Mass Spectrometry Market Through 2032
Executive Overview
The clinical mass spectrometry landscape is undergoing a fundamental transformation, driven by the convergence of regulatory simplification, assay automation, and an expanding menu of precision diagnostics. Between 2020 and 2025, the global market demonstrated robust momentum, rising from approximately 785 million USD to an estimated 1.26 billion USD. As we enter 2026, the sector is projected to reach roughly 1.347 billion USD, with sustained growth expected across the 2026–2032 forecast horizon under a compound annual growth rate of 9.35 percent. By 2032, revenue is positioned to exceed 2.36 billion USD, signaling a structural shift from niche, laboratory-intensive workflows toward routine, clinically integrated testing paradigms.
PW Consulting’s latest Clinical Mass Spectrometry Market research equips executive teams, product strategists, and commercial leaders with a decision-grade framework to navigate this inflection point. Rather than delivering static snapshots, this study translates macro-level momentum into actionable go-to-market intelligence, competitive positioning insights, and regulatory-readiness guidance tailored to 2026 planning cycles.
Why This Study Matters Now
Strategic planning in the clinical diagnostics space has never been more complex. Manufacturers, laboratory directors, and health-system procurement teams are simultaneously evaluating platform investments, reimbursement pathways, and multi-year commercialization roadmaps. Three forces are reshaping the decision environment:
- Regulatory and complexity reclassification. Recent classification updates are lowering operational barriers for mass spectrometry-based testing, enabling broader deployment outside highly specialized centers. This expansion changes adoption curves, service models, and competitive intensity.
- Assay menu expansion and automation. Vendors are accelerating integrated reagent-and-platform strategies that bundle analyzers with clinically meaningful test menus, shifting purchasing decisions from standalone instrumentation toward total solution value.
- Reimbursement and coding dynamics. Evolving procedure coding frameworks and payer-specific coverage variability are influencing laboratory budgeting and test selection, making reimbursement intelligence a direct driver of commercial success.
For decision-makers, the challenge is no longer simply recognizing that the market is expanding. The strategic imperative is understanding where value is consolidating, which workflow models are becoming standard, and how to align product, pricing, and partnership choices with the next phase of market maturation.
Market Trajectory and What It Reveals
The historical record from 2020 through 2025 reflects a market that has more than kept pace with advancing clinical demand and technology maturation. The progression from mid-2020 levels toward the 1.26 billion USD mark in 2025 demonstrates not only volume growth but also deepening adoption across institutional and commercial laboratory settings. Entering 2026, the forecast trajectory remains consistently upward, extending toward 2.36 billion USD by 2032.
Importantly, this growth is not uniform across all technology categories or clinical use cases. The study examines how specific platform architectures, application focus areas, and regional adoption patterns diverge in terms of maturity, pricing power, and competitive density. Rather than presenting high-level percentages in isolation, the full report maps these relationships to real-world purchasing behavior and service economics. Readers seeking exact regional or segment breakdowns will find those delineated within the complete analysis, but the core strategic message is clear: future winners will be defined by workflow integration, evidence generation, and regulatory alignment rather than instrument specs alone.
The market’s concentration profile further underscores the importance of positioning. With the top three players accounting for a majority share and the top five holding an even larger portion of total revenue, new entrants and expanding incumbents must avoid head-to-head commoditization in saturated segments. Instead, the report identifies whitespace opportunities tied to specialized assays, simplified operational workflows, and regional partnership models that can accelerate commercial traction.
Inside the Report: Actionable Intelligence for 2026 Decision-Making
Designed for strategy, R&D, and commercial leadership, this study goes beyond top-line forecasts to address the operational questions that determine execution quality. The full research package includes:
- Market sizing and forecast architecture across historical baselines and forward-looking scenarios, with transparent methodology to support internal modeling and investment committees.
- Technology and workflow mapping that compares platform categories and their clinical fit, enabling organizations to assess where automation, software, and reagent integration will matter most.
- Application-level analysis covering the clinical domains shaping demand, including therapeutic monitoring, screening programs, hormone and hemoglobin testing, and adjacent utility areas.
- Competitive benchmarking of leading organizations, focused on portfolio strategy, product differentiation, and recent commercial and regulatory milestones.
- Regulatory and reimbursement context that ties classification decisions, clearance events, and coding updates to laboratory uptake and commercial viability.
- Strategic recommendations for segmentation targeting, pricing architecture, channel strategy, and partnership design, calibrated to the current competitive landscape.
Each section is structured to support immediate decision-making while also providing the foundational data needed for long-range planning. The emphasis is on interpretation over enumeration: the study highlights where attention should be allocated, what trade-offs are likely to emerge, and which indicators can serve as early signals of shift in adoption or competitive intensity.
Competitive Landscape and Strategic Positioning
The competitive field reflects a blend of broad-diagnostics scale, specialized mass spectrometry heritage, and increasingly integrated software-plus-hardware solutions. Several organizations stand out as reference points for understanding how portfolios are being shaped:
Thermo Fisher Scientific continues to anchor its clinical mass spectrometry strategy in quantitative workflows, emphasizing solutions designed for biomarker verification, quantitative clinical analysis, and precision medicine pipelines. Its platform-oriented approach highlights the growing importance of software-enabled quantification in real laboratory environments.
MALDI-TOF Mass Spectrometer Market
Waters Corporation has focused on analytical performance for therapeutic drug monitoring, biomarker testing, and TDM applications, with FDA-cleared systems reinforcing its emphasis on clinically validated workflows. This orientation illustrates the strategic value of regulatory clearance in building institutional trust and expanding access to routine use cases.
Bruker Daltonics GmbH & Co. KG has extended its presence through systems and software aimed at microorganism identification and differentiation from clinical samples. Recent regulatory clearance for its clinical mass spectrometry microorganism identification and differentiation system, classified as Class II with special controls under 21 CFR 866.3378, underscores the expanding role of mass spectrometry in infectious disease diagnostics and the importance of clear regulatory pathways for adoption.
Roche Diagnostics International AG has been moving aggressively to expand an automated mass spectrometry menu for routine clinical use. With a cobas-based mass spec solution, Ionify reagent packs covering antibiotics, steroid hormones, and vitamin D metabolites, and a broad IVD menu aligned with CE Mark recognition, the company has been positioning mass spectrometry as part of a broader, automation-friendly diagnostic offering. Recent milestones include CE Mark approval for antibiotic drug monitoring reagents and FDA classification of steroid assays as moderate-complexity under CLIA, both of which expand the potential scope of deployment in standard laboratory settings.
Taken together, these profiles reveal a market in which differentiation is increasingly tied to operational simplification, regulatory readiness, and clinically relevant assay breadth. The complete study provides deeper comparative analysis, including how each organization’s strategy intersects with purchasing criteria, laboratory workflow priorities, and regional adoption patterns.
Regulatory, Reimbursement, and Operational Signals Shaping Strategy
Recent developments are shifting the operational baseline for clinical mass spectrometry and, by extension, the commercial strategy required to capture demand:
Clinical Mass Spectrometry Market
- Regulatory approval and clearance events are broadening the practical scope of mass spectrometry in routine diagnostics, particularly where automation and reagent integration reduce hands-on complexity.
- Complexity reclassification is lowering the operational barrier for certain assays, extending access beyond specialized laboratories and creating new pathways for volume expansion.
- Reimbursement coding updates continue to evolve, with procedure-level frameworks such as CPT 82542 influencing how laboratory testing is documented and reimbursed. Because payer coverage and analyte-specific reimbursement can vary widely, test selection and commercial planning increasingly depend on reimbursement intelligence rather than technical feasibility alone.
- Industry engagement remains active, with sector conferences and professional bodies contributing to standards discussion, best-practice sharing, and technology adoption signals that can inform timing and positioning decisions.
For companies planning multi-year investments, the strategic implication is that product excellence is necessary but no longer sufficient. Commercial success depends on orchestrating regulatory alignment, reimbursement readiness, service models, and evidence generation in a coordinated way. The report translates these dynamics into practical checkpoints for decision-makers evaluating product roadmaps, partnership opportunities, and market entry timing.
Strategic Takeaways for 2026 Planning
As organizations finalize strategy for 2026, the clinical mass spectrometry market offers both clear opportunity and sharper competitive contrast. The most relevant implications include:
- Prioritize workflow value over instrument specifications. Decision-makers are increasingly weighing total solution benefits, including software enablement, reagent integration, and operational burden, rather than isolated analytical performance metrics.
- Use regulatory milestones as competitive moats. Clearance, classification, and approval events can shape adoption speed and laboratory eligibility. Mapping these milestones to commercial messaging and launch sequencing is becoming essential.
- Tailor regional and application strategies to real adoption conditions. Maturity levels differ across geographies and clinical applications. A disciplined approach to where, how, and with whom to scale can improve return on commercial investment.
- Plan for concentration dynamics. With a relatively consolidated revenue base among leading players, expanding firms should define defensible differentiation and identify partnership or specialization routes that reduce exposure to undifferentiated competition.
- Embed reimbursement intelligence early. Because coverage and coding realities influence laboratory purchasing and test volume, commercial models that account for reimbursement uncertainty are better positioned to withstand budget constraints and payer scrutiny.
Secure the Complete Strategic Intelligence
This overview is designed to demonstrate the strategic depth and decision relevance of PW Consulting’s Clinical Mass Spectrometry Market research without diluting the proprietary segmentation analysis and scenario detail that executives need. The full report provides the regional and application-level breakdowns, forecast trajectories, competitive benchmarking, and operational recommendations necessary to convert market visibility into measurable advantage.
For leadership teams preparing capital allocation, product roadmap reviews, partnership evaluations, or regional expansion plans, the complete analysis offers a structured basis for de-risking choices in a fast-evolving environment. To access the full dataset, segmentation detail, and executive recommendations, request the comprehensive study and make 2026 planning decisions with a stronger foundation.
For detailed analysis of this topic, please visit the official page: Clinical Mass Spectrometry Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com