

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Silicon Wafer Market to Hit $209.6M by 2032, 6.5% CAGR

Strategic Imperatives in the Silicon Wafer Market: 2026 Outlook and Beyond
The silicon wafer remains the foundational substrate upon which the modern semiconductor industry is built. As chip architectures grow more complex and demand surges from artificial intelligence, automotive electrification, and high-performance computing, the wafer market has transitioned from a commoditized supply chain component to a strategic bottleneck. PW Consulting's latest market research on the Silicon Wafer Market offers a comprehensive lens into this evolving landscape, providing enterprise leaders with the intelligence required to navigate the period from 2026 through 2032.
This report is not merely a collection of statistics. It is a strategic toolkit designed to inform capital allocation, supply chain resilience planning, and competitive positioning. In an environment defined by geopolitical friction, capacity expansions, and rapid technological shifts, understanding the macro trajectory and the nuanced dynamics of the supply base is critical. The following insights preview the depth of analysis available in the full study, highlighting why this intelligence is essential for decision-makers in 2026.
Market Trajectory and Growth Vectors
The silicon wafer market has demonstrated resilient growth over the past half-decade, recovering from pandemic-era disruptions and capitalizing on the digital transformation boom. Our analysis tracks revenue performance from 2020 through the base year of 2025, establishing a robust historical baseline. The market has expanded steadily, reflecting the insatiable demand for integrated circuits and the gradual recovery of solar applications. Looking forward, the forecast period from 2026 to 2032 projects a compound annual growth rate of 6.5%. This growth is not linear; it is punctuated by cycles of capacity addition, technological node transitions, and regional policy interventions.
Revenue projections indicate a clear upward path, with market size expected to surpass significant milestones by the end of the decade. The acceleration is underpinned by the proliferation of advanced packaging, the adoption of wider diameters for cost efficiency, and the specific requirements of logic and memory manufacturers pushing the boundaries of performance. However, growth rates vary across segments and regions, influenced by local industrial policies and capacity utilization rates. The full report dissects these variations without losing sight of the overarching trend: the silicon wafer market is entering a phase of sustained expansion driven by structural demand rather than temporary cyclical upticks.
Silicon Wafer Market
Stakeholders must recognize that these figures represent more than headline numbers. They reflect the aggregate outcome of investment decisions made by major producers, the timing of fab constructions, and the interplay between supply constraints and demand elasticity. For instance, recent shipment data from industry bodies indicates continued momentum in square inch deliveries, corroborating the revenue growth trajectory observed in financial metrics. This alignment between physical volume and monetary value reinforces the reliability of the forecast model employed in this study.
Segmentation Dynamics: Type, Application, and Regional Nuances
A superficial view of the market obscures the critical divergences that dictate profitability and strategic risk. The silicon wafer market is segmented by type, application, and region, each presenting distinct challenges and opportunities. Our research provides a granular breakdown of these segments, analyzing share contributions and growth rates to identify where value is being created and where competition is intensifying.
Product Type and Technology Transitions
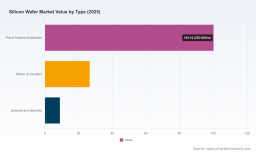
The market is anchored by established substrate types, yet innovation in specialized wafers is reshaping the competitive landscape. Prime polished substrates continue to command the largest share, serving as the workhorse for general-purpose semiconductor manufacturing. However, the growth premium is increasingly found in Silicon on Insulator and Epitaxial and Specialty wafers. These high-value products are essential for advanced logic, radio frequency applications, and power management devices.
The shift toward wider diameters, particularly the dominance of 300 mm wafers in leading-edge logic and memory production, drives efficiency gains for manufacturers but requires substantial capital investment. Meanwhile, 200 mm wafers retain relevance in automotive, analog, and mature node applications. The report evaluates the capacity mix across these types, highlighting how leading producers are reallocating resources to capture high-margin segments. For example, the expansion of epitaxial capabilities by key players signals a strategic bet on the convergence of AI workloads and high-performance power devices. Understanding the balance between standard and specialty wafers is crucial for forecasting margin profiles and supply security.
Application Drivers and Demand Centers
Demand for silicon wafers is heterogeneous, driven by diverse end-use applications. Integrated Circuits remain the dominant consumption center, reflecting the pervasiveness of semiconductors in electronics, computing, and communications. However, other applications are gaining traction. Solar Cells, while subject to policy fluctuations and technology shifts, continue to represent a significant volume segment, with wafer requirements tied to global renewable energy targets. The "Others" category encompasses niche but high-growth areas such as MEMS and RF devices, which often demand specialized wafer specifications.
The report analyzes how application mix influences regional demand patterns. For instance, regions with strong automotive manufacturing bases exhibit different wafer consumption profiles compared to hubs focused on consumer electronics or data center infrastructure. By mapping application demand to regional production and trade flows, the study reveals potential vulnerabilities in supply chains. Companies relying on wafers for specific applications must assess whether their suppliers are adequately exposed to those end markets or if portfolio diversification offers a buffer against sector-specific downturns.
Regional Landscape and Policy Influence
Geography plays a pivotal role in the silicon wafer market, shaped by manufacturing concentration, proximity to logic fabs, and government incentives. Asia Pacific stands as a colossal region in terms of market size, reflecting the dense concentration of semiconductor fabrication in East and Southeast Asia. North America and Europe, while smaller in aggregate volume, are experiencing renewed strategic interest due to onshore manufacturing initiatives and supply chain security concerns. Latin America and the Middle East and Africa represent emerging or niche markets with specific growth potentials tied to local industrial development or investment inflows.
Policy interventions are reshaping regional dynamics. Regulations and incentives are altering the calculus for capacity location. In China, targets for domestic usage of advanced silicon wafers by major chipmakers signal a push for self-sufficiency that could impact global trade flows and pricing dynamics. Concurrently, in the United States, preliminary terms under the CHIPS and Science Act for major wafer suppliers indicate support for constructing new 300 mm facilities, aiming to bolster domestic supply for critical industries. These policy-driven shifts create both opportunities for suppliers aligned with national strategies and risks for those exposed to trade barriers or subsidy-driven distortions.
Semiconductor Silicon Wafer Market
The full report provides detailed regional analysis, including market size estimates and growth projections for each area, while respecting the complexity of local market structures. It avoids oversimplification, instead offering a nuanced view of how regional policies, infrastructure, and talent pools interact to shape competitive outcomes. Decision-makers can use this analysis to evaluate market entry strategies, partnership opportunities, and risk exposure in specific geographies.
Competitive Landscape: Incumbents, Strategies, and Moves
The silicon wafer industry is characterized by high barriers to entry, significant capital intensity, and technological expertise. Market concentration is substantial, with the top three companies commanding a large share of global revenue and the top five consolidating an even greater portion. This concentration underscores the importance of monitoring the strategic moves of key players. PW Consulting's report profiles the major companies shaping the market, analyzing their product portfolios, geographic footprints, and recent developments.
Shin-Etsu Chemical Co., Ltd. and SUMCO Corporation, both headquartered in Tokyo, remain titans in the global arena. Shin-Etsu produces a comprehensive range of 300 mm prime, epitaxial, SOI, and annealed silicon wafers for logic, memory, and power devices, maintaining a broad technology base. SUMCO manufactures high-quality polished and epitaxial silicon wafers, with production sites spanning Japan, Malaysia, and the United States, reflecting a globalized operational model. Siltronic AG, based in Munich, specializes in 300 mm prime, epitaxial, and power device wafers, with manufacturing capabilities in Germany, Singapore, the United States, and Asia. Recent announcements, such as the inauguration of a new 300 mm epitaxial wafer fabrication facility in Singapore, highlight the ongoing investment in advanced capacity and customer qualification efforts.
GlobalWafers Co., Ltd., headquartered in Hsinchu, Taiwan, supplies 200 mm, 300 mm, and SOI silicon wafers for leading-edge logic, memory, and automotive applications, with facilities in Taiwan, Japan, and the United States. Its involvement in CHIPS Act-related discussions underscores the strategic importance of wafer supply in national security contexts. SK Siltron Co., Ltd., located in Gumi, South Korea, produces 200 mm and 300 mm silicon wafers primarily for memory, logic, and power devices, leveraging proximity to key memory manufacturers.
Wafer Works, based in Taipei, manufactures 150 mm, 200 mm, and 300 mm polished and epitaxial silicon wafers for IC, MEMS, and RF applications, catering to a diverse set of device requirements. Zhonghuan Advanced Semiconductor Materials Co., Ltd., in Yixing, China, produces 150 mm, 200 mm, and 300 mm silicon wafers for semiconductor and related industries, representing the expanding domestic capabilities in the region. Okmetic Oyj, headquartered in Vantaa, Finland, manufactures 150 mm, 200 mm, and 300 mm silicon wafers for MEMS, RF, power, and logic applications, adding a European dimension to the supply base.
Beyond company profiles, the report analyzes recent developments that signal shifts in strategy or market conditions. Shipment forecasts from the SEMI Silicon Manufacturers Group indicate growth trajectories driven by AI-related demand for advanced epitaxial and HBM wafers, with updates showing increases in square inch volumes through late 2025 and into 2026. However, not all news is positive; structural shifts in the global semiconductor market have led to delays in construction projects for some major producers, illustrating the volatility and cyclical nature of capacity planning. These events provide critical context for understanding near-term supply availability and competitive responses.
Strategic Applications of the Report
PW Consulting's Silicon Wafer Market report is designed to be actionable. It equips stakeholders with the insights needed to address pressing strategic questions.
- Capital Investment and Capacity Planning: Evaluate the timing and scale of capacity expansions against demand forecasts. Assess the risk of overcapacity or shortages in specific wafer types or regions, and align investment decisions with long-term growth vectors.
- Supply Chain Resilience: Identify dependencies on concentrated suppliers or regions. Analyze the impact of geopolitical policies, such as domestic usage targets or subsidy programs, on supplier viability and trade routes. Develop strategies to mitigate disruption risks.
- Competitive Benchmarking: Compare your organization's position against key competitors in terms of product coverage, geographic presence, and technological capabilities. Understand the strategic priorities of market leaders to anticipate moves in pricing, capacity, or customer engagement.
- Segment and Application Focus: Determine which wafer types and applications offer the most attractive growth and margin profiles. Align product development or procurement strategies with the segments driving value creation, while monitoring the dynamics of mature or cyclical segments.
- Policy and Regulatory Navigation: Understand the landscape of industrial policy affecting the silicon wafer market. Assess how regulations and incentives might alter market structure, influence supplier behavior, and create new opportunities or constraints for market participants.
The report synthesizes macro data with micro-level analysis, providing a holistic view that supports scenario planning and risk assessment. By integrating shipment data, facility announcements, and policy developments, the study offers a dynamic perspective on market evolution. It helps leaders move beyond static assumptions and prepare for a range of possible futures.
Conclusion: Navigating the Next Phase of Growth
The silicon wafer market stands at a critical juncture. The convergence of technological advancement, capacity expansion, and geopolitical realignment is reshaping the industry's structure and competitive dynamics. With a projected compound annual growth rate of 6.5% through 2032 and a market size on a clear upward trajectory, the sector offers significant opportunities for those equipped with the right intelligence. However, success requires more than optimism; it demands a deep understanding of the factors driving growth, the segments where value is shifting, and the strategic actions of key competitors.
PW Consulting's comprehensive research provides the foundation for informed decision-making. It reveals the data and analysis necessary to navigate the complexities of the silicon wafer market with confidence. We invite industry leaders, investors, and supply chain professionals to explore the full report to access the detailed segmentation data, regional breakdowns, and competitive intelligence that will inform their strategies for 2026 and beyond. In a market where information is a strategic asset, this report delivers the clarity needed to act decisively.
For detailed analysis of this topic, please visit the official page: Silicon Wafer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com